


Generac Holdings (GNRC) drew fresh attention after its recent share move, with the price closing at US$206.95. Investors are weighing this level against the company’s current earnings profile and broader return history.
Recent trading has been choppy for Generac Holdings, with the share price slipping 2.48% on the day, even after a 7 day share price return of 3.78% and a 1 month gain of 11.64%. This sits against a 90 day decline of 18.09% and a 1 year total shareholder return of 23.27%, which points to long term investors still being ahead while shorter term momentum has cooled slightly.
Scan how Generac Holdings stacks up against other power and industrial players by reviewing the hand picked 39 power grid technology and infrastructure stocks in this space.
Generac Holdings has a broad energy hardware and software footprint and a share price that has already moved sharply in recent months. The real question now is whether that business quality is fairly reflected in today’s valuation.
Most Popular Narrative: 29% Undervalued
On the most followed valuation view, Generac Holdings has a fair value of $292.38 against the recent $206.95 close, which puts a lot of weight on future data center demand and margin recovery.
Accelerating demand for backup power solutions in data centers driven by AI adoption and global digitalization has resulted in a structural supply deficit for large commercial generators. Generac's rapid entry and a backlog greater than $150 million position it to capture significant revenue growth and operating leverage over the next several years, with further potential upside as the company expands capacity to address 2027+ demand.
See why 26 investors see Generac Holdings as 29% undervalued.
Result: Fair Value of $292.38 (UNDERVALUED)
Still, Generac Holdings faces real pressure if the residential solar contraction drags on or if the Amazon linked data center build out delivers less revenue than expected.
Find out about the key risks to this Generac Holdings narrative.
Another View On Generac Holdings Valuation
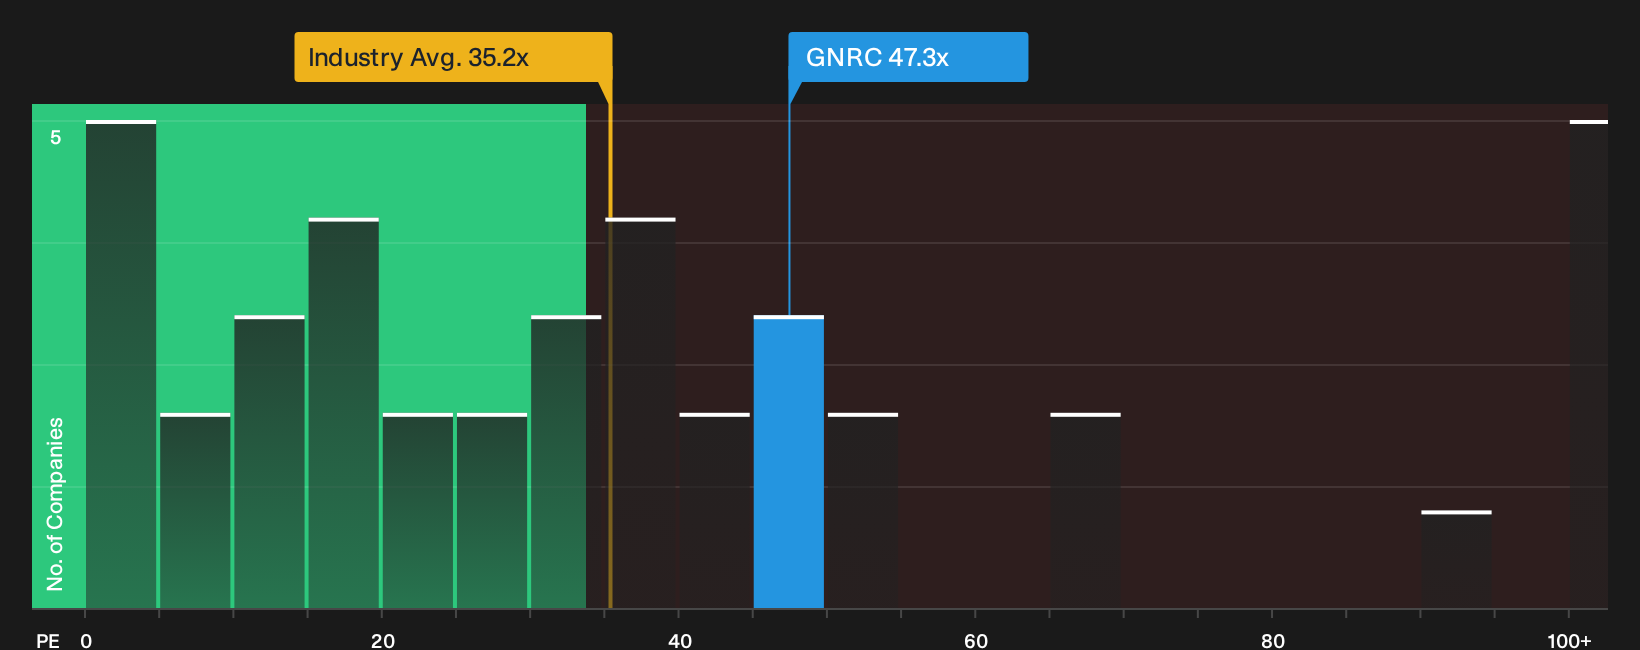
There is a catch. While the narrative fair value points to Generac Holdings trading below its estimated worth, the current P/E of 47.3x is higher than both the US Electrical industry at 35.2x and a fair ratio of 40.8x. This implies investors are already paying up for the story. Where does that leave your margin of safety?
To see how that premium looks through a different lens, take a closer look at our detailed valuation breakdown. This includes how earnings, peers and the fair ratio compare in practice, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
All of this leaves a clear question for you. If sentiment around Generac Holdings feels compelling, move quickly to inspect the underlying data and stress test the upside case in the 3 key rewards.
Ready For More Investment Ideas Beyond Generac Holdings?
If Generac Holdings sits on your radar, do not stop there. Broaden your watchlist with other focused ideas that could suit very different portfolio roles.
- Target resilient payouts and cash flow strength by reviewing a hand picked set of income candidates in the 7 dividend fortresses.
- Hunt for pricing gaps where quality and value meet by scanning the curated 31 high quality undervalued stocks.
- Secure potential ballast for your portfolio by searching through the disciplined 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com