


Key Points
Nvidia management has approved a $150 billion increase in share repurchase authorization.
Nvidia's terrific growth and cheap valuation are likely why management is making this move.
Nvidia's historic move is a signal for investors to buy the stock, especially given that it could double over the next two and a half years.
Artificial intelligence (AI) pioneer Nvidia (NASDAQ:NVDA) has just announced that it will increase its share repurchase authorization by a whopping $150 billion, taking its total remaining authorization under the ongoing program (which will end in fiscal 2028) to $235 billion.
Nvidia management notes that this is the largest increase in share buyback authorization in history. Founder and CEO Jensen Huang pointed out that the company's cash-generation capacity has put it in a solid position to return capital to shareholders, adding that the historical increase in the share buyback program "reflects our confidence in the long-term opportunity ahead."
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's look at the reasons why Nvidia may have made this historic move, and check what it means for this high-flying AI stock.

Image source: The Motley Fool.
Nvidia's $150 billion buyback plan indicates that the stock is undervalued
Undervaluation is a key reason why companies choose to buy back their own stock. A closer look at Nvidia's growth and earnings multiples will make it clear why management is choosing to significantly increase its share repurchase authorization.
Nvidia trades at just 29 times trailing earnings, lower than the tech-laden Nasdaq Composite index's average earnings multiple of 39. The forward earnings multiple of 25 is even more attractive. These multiples clearly indicate that Nvidia stock trades at a discount considering its red-hot growth. The company reported a 120% year-over-year increase in non-GAAP earnings per share in the second quarter of fiscal 2027 (which ended July 26).
Notably, Nvidia's earnings growth surged from the 54% year-over-year increase it reported in the same quarter last year. Even better, Nvidia expects to sustain robust growth levels going forward. It expects $108 billion in revenue for the current quarter, up by 89% over the year-ago period. So, don't be surprised to see Nvidia delivering a big pop in earnings in the current quarter as well.
Moreover, Nvidia expects its robust growth to continue in fiscal 2028, forecasting 70% revenue growth. That's quite impressive for a company whose revenue is on track to jump by 90% in fiscal 2027 to $411 billion, according to consensus estimates. Moreover, the strong jump in Nvidia's revenue will filter down to the bottom line.
Its earnings per share are poised to nearly double in fiscal 2027 to $9.31. The forecast for the next couple of years points toward healthy increases in its bottom line.
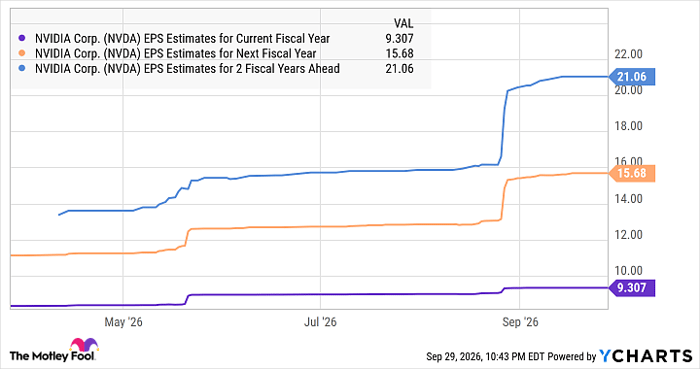
NVDA EPS Estimates for Current Fiscal Year data by YCharts
As such, it is easy to see why Nvidia management has decided to increase share repurchase authorization right now. The company has delivered robust growth, and the fiscal 2028 guidance suggests its impressive growth trajectory is here to stay. What's more, Nvidia could sustain its impressive growth beyond fiscal 2028, as evident from the chart above.
That's not surprising, as the company estimates that annual AI infrastructure spending could soar to $3-$4 trillion in 2030, well above the $1.5 trillion forecast for 2026, according to Gartner. Nvidia's status as the dominant AI chip designer, with an 80% market share, puts it in a solid position to capitalize on this lucrative growth opportunity.
All this explains why Nvidia deserves to trade at a premium valuation, which it isn't right now. The massive buyback authorization could inject investor confidence in the stock, as it suggests that management is buying back shares while they are cheap. If that's indeed the case, I won't be surprised to see Nvidia stock doubling from here.
Why I think that Nvidia may double
The chart in the previous section indicated that Nvidia's earnings per share could reach $21.06 in fiscal 2029, more than 4x its fiscal 2026 earnings of $4.77 per share. That translates into a healthy three-year compound annual growth rate (CAGR) of 64%. Nvidia, therefore, could command a higher valuation, especially as the increased buyback authorization reduces the share count and props up earnings per share.
Assuming Nvidia trades at a conservative 25 times earnings at the end of fiscal 2029, in line with its forward earnings multiple, and its earnings per share increase to $21.06 (based on the chart in the previous section), its stock price could jump to $526. That's 132% higher than Nvidia's stock price today, suggesting the stock could double over the next two and a half years.
Harsh Chauhan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Nvidia. The Motley Fool recommends Gartner. The Motley Fool has a disclosure policy.