


ATI (ATI) raised its 2026 adjusted free cash flow guidance to a range of $550 million to $600 million, supported by higher adjusted EBITDA and improved operations tied to aerospace and defense demand.
ATI shares trade at $189.40 after a mixed few months, where the 30-day share price return declined 7.25%, the year-to-date share price return is 58.89%, and the 1-year total shareholder return of 128.17% points to strong longer-term momentum as investors react to upgraded cash flow guidance and solid aerospace and defense demand.
Scan other aerospace and defense suppliers riding similar free cash flow and earnings momentum to ATI by reviewing the hand-picked 31 resilient stocks with low risk scores alongside this update.
ATI has already rewarded investors with a sharp run and a richer free cash flow outlook. The question now is whether the current valuation already captures that shift or still leaves meaningful upside.
Most Popular Narrative: 31% Undervalued
ATI closed at $189.40 while the most followed narrative anchors fair value at $275, so the market view of its future cash and earnings power is critical.
The decarbonization drive across aviation and other industries, with airlines and manufacturers seeking lighter and more fuel-efficient planes, translates directly into heightened long-term demand for ATI's advanced titanium and nickel alloys, supporting higher average selling prices and increasing net margins due to their differentiated, high-value product mix.
Ongoing heavy investment in capacity expansion and process debottlenecking, both upstream in melt assets and downstream in finishing and inspection, enables ATI to capture increasing volumes as aerospace production rates climb, unlocking further operating leverage and contributing to sustained earnings acceleration over the next several years.
See why 4 investors see ATI as 31% undervalued.
Result: Fair Value of $275 (UNDERVALUED)
Still, ATI’s reliance on a concentrated aerospace customer base and ongoing heavy capital investment could quickly challenge this upbeat narrative if demand or execution falters.
Find out about the key risks to this ATI narrative.
Another View on ATI’s Valuation
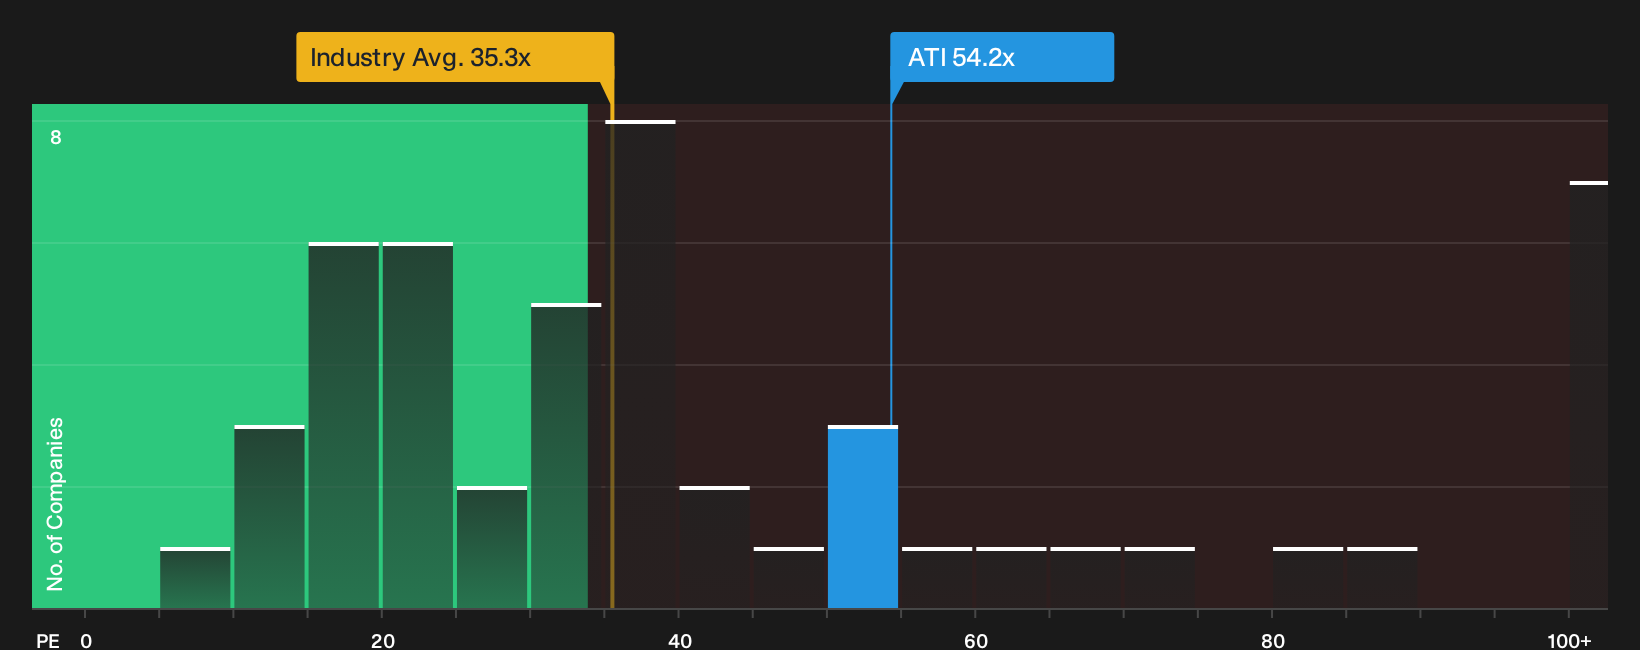
On the bullish narrative, ATI screens as undervalued with a fair value of $275. The P/E picture tells a different story. The stock trades on 54.2x earnings versus 35.3x for the US Aerospace & Defense group and a fair ratio of 31.9x, which points to a rich tag that could matter if sentiment cools.
Investors using this earnings multiple lens are effectively paying up today and counting on strong execution to close that gap. The question is whether that premium feels like justified growth pricing or a margin of error that has already been used up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on ATI is split, which makes this an interesting moment to act quickly and test the numbers against personal expectations. To weigh both sides of the story directly, review the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond ATI?
ATI gives a useful reference point, but your next move comes from lining up a few fresh candidates side by side and pressure-testing them against the same framework.
- Pinpoint potential mispricings by scanning the 31 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Lock in income-focused opportunities by checking the 7 dividend fortresses that aim to pair higher yields with resilient underlying businesses.
- Strengthen your watchlist with the list of solid balance sheet and fundamentals (25 results) so you are not caught off guard when conditions turn and weaker finances get exposed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com