


Ollie's 700th store puts expansion in focus
Ollie's Bargain Outlet Holdings (OLLI) has crossed a key threshold with the opening of its 700th store in Maplewood, Minnesota, a fresh data point for investors tracking its brick and mortar expansion.
Against that store-opening backdrop, Ollie's Bargain Outlet Holdings has had a mixed run in the market, with the share price up 18.4% over the past month and 15.4% over 90 days, yet down 23.1% year to date and delivering a 33.7% decline in total shareholder return over the past year. At the same time, longer three and five year total shareholder returns of 17.8% and 37.2% suggest the recent weakness follows a more constructive multi year stretch.
Scan Ollie's Bargain Outlet Holdings alongside other brick and mortar retailers that are showing strong fundamentals using our curated list of list of solid balance sheet and fundamentals (25 results)
Ollie's Bargain Outlet Holdings is clearly still building stores and sales, but after the sharp recent rebound in the share price, are you paying a fair price for that strength or stretching on valuation?
Most Popular Narrative: 13% Undervalued
On Simply Wall St, the leading narrative for Ollie's Bargain Outlet Holdings pegs fair value at $98.78 against a last close of $85.65, so the story framing that investors are watching is about a discount rather than a premium.
Ollie's reported its second quarter of fiscal 2027 on September 2, 2026, posting comparable store sales of -1.8% against what management called "one of the toughest comparisons we've had as a company." The headline earnings beat, adjusted EPS of $1.42, up 43%, was substantially powered by IEEPA tariff refunds that added 380 basis points to gross margin, a nonrecurring item that management both celebrated and immediately began caveating.
See why 2 investors see Ollie's Bargain Outlet Holdings as 13% undervalued.
Result: Fair Value of $98.78 (UNDERVALUED)
Still, the Ollie's Bargain Outlet Holdings story leans on tariff refund benefits and softer comparable sales, and any reset to comparable sales expectations could quickly reframe that perceived undervaluation.
Find out about the key risks to this Ollie's Bargain Outlet Holdings narrative.
Another View: Multiples Put Ollie's In A Different Light
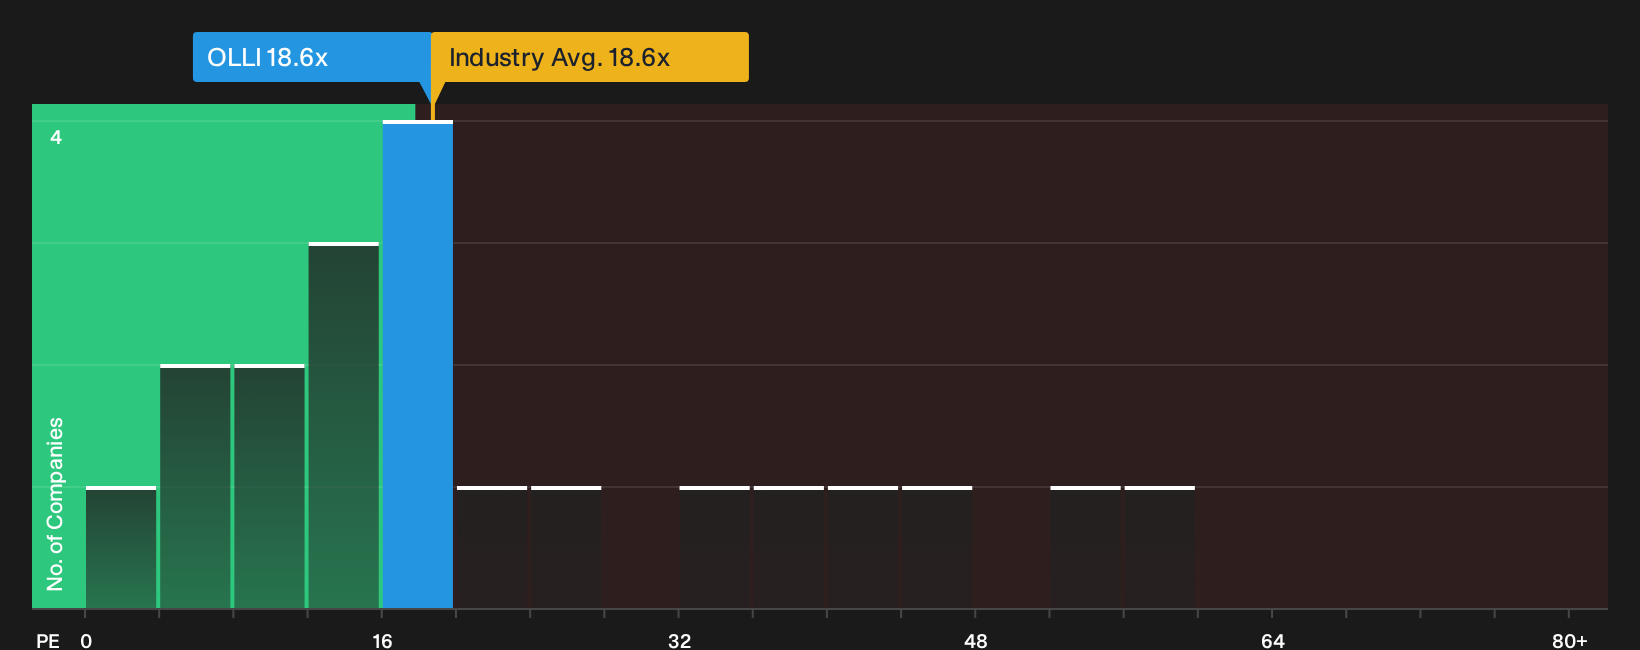
While the leading Simply Wall St narrative tags Ollie's Bargain Outlet Holdings as 13% undervalued at $98.78 fair value, the P/E snapshot points a different way. The stock trades on 18.6x earnings versus a 13.5x fair ratio, which implies investors are paying a premium that could compress if sentiment cools.
The same 18.6x P/E is also slightly above both the peer average at 18.4x and the global Multiline Retail group at 18x. This suggests limited room for error if growth or margins soften. How comfortable are you paying above the fair ratio when the recent share price record has already been choppy?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Ollie's Bargain Outlet Holdings story is mixed, so treat it as a prompt to move fast, inspect the underlying numbers, and decide where you stand. To see what optimism is already priced in, review the 3 key rewards.
Looking for more Ollie's ideas and beyond?
If Ollie's Bargain Outlet Holdings has your attention, do not stop here. Broaden your watchlist with fresh ideas that could reshape how you think about opportunities.
- Target potential value candidates before they move by scanning companies on the 31 high quality undervalued stocks.
- Prioritise resilience and capital protection by reviewing a 31 resilient stocks with low risk scores that filters for sturdier business profiles.
- Spot lesser-known opportunities with strong fundamentals by working through a set of 19 high quality undiscovered gems that many investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com