


Disney (DIS) shares are in the spotlight after the entertainment conglomerate announced its latest wave of job cuts, terminating about 300 corporate roles, mostly in the human resources (HR) and tech divisions.
This marks Disney’s third round of layoffs in 2026, following earlier downsizing in April and July that eliminated over 1,300 roles across ESPN, Pixar, and National Geographic, alongside a voluntary retirement package.
Versus the start of this year, Disney stock is down about 10% at the time of writing.
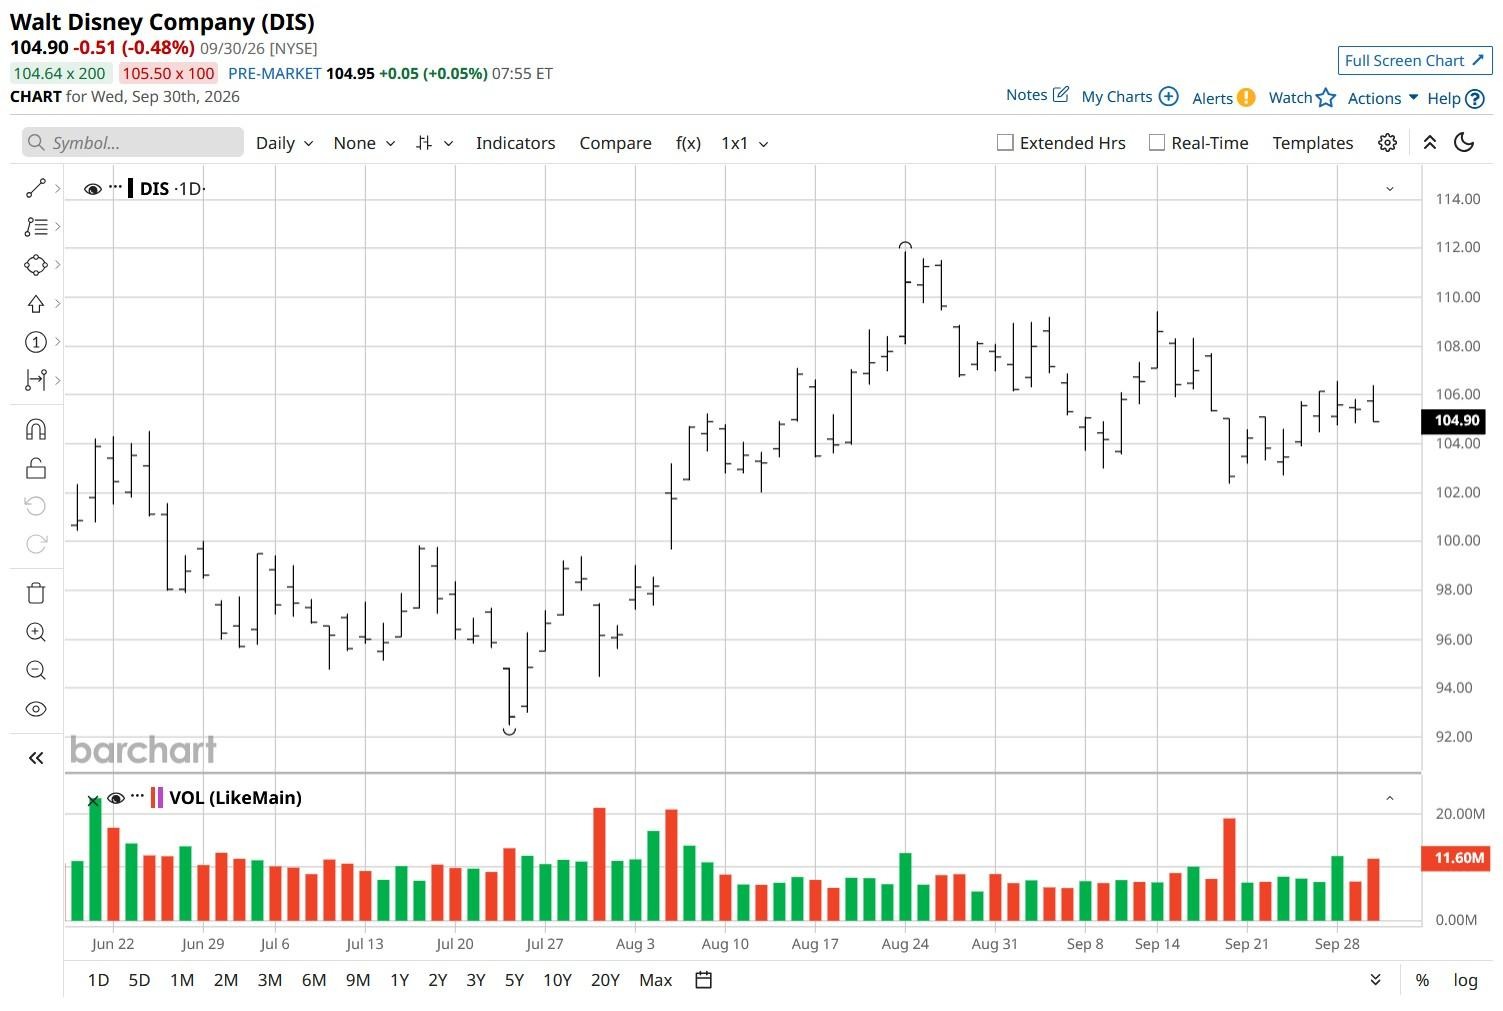
What the Layoffs Mean for Disney Stock
The latest round of layoffs highlights management’s focus on operational efficiency and aggressive margin expansion across non-core corporate functions.
By insulating creative divisions like Disney Entertainment Television and motion picture studios to target internal administrative and tech support layers instead, CEO Josh D’Amaro is attempting to streamline overhead without stifling media output.
For investors, these recurring operational cuts showcase an earnest commitment to lowering selling, general, and administrative (SG&A) expenses, directly supporting the company’s ambitious cash flow targets and expanded share buyback program of at least $9 billion for fiscal 2026.
Over the medium term, leaner corporate structures should protect net profit margins against macro headwinds and rising content production costs, positioning DIS shares to benefit from improved operating leverage once broader advertising markets fully recover.
Should You Invest in DIS Shares Today?
Investing in Disney shares presents a “compelling value opportunity” for patient investors, though short-term volatility remains part of the picture.
Trading at about 15x forward earnings with a 1.43% dividend yield, the company has successfully transformed its direct-to-consumer streaming segment into a consistently profitable engine while generating record revenue from its parks and experiences division.
Disney's unmatched intellectual property portfolio, burgeoning streaming margins, and disciplined capital allocation make DIS an attractive long-term hold for growth and value investors alike.
How Wall Street Recommends Playing Disney
Wall Street analysts also recommend owning DIS stock for the long term.
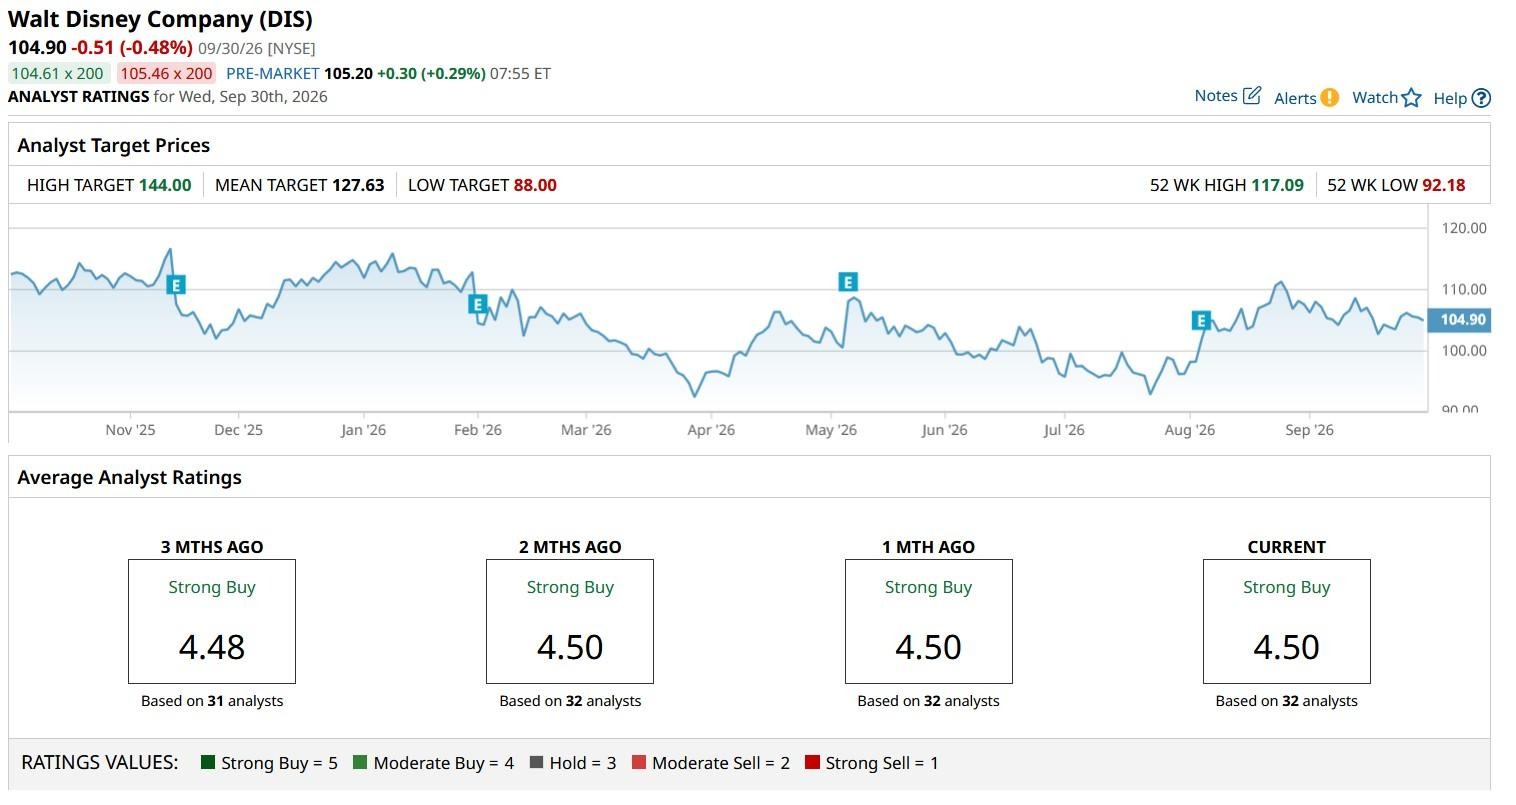
According to Barchart, the consensus rating on Disney sits at “Strong Buy” currently, with the mean price target of nearly $128 indicating potential upside of more than 20% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.