


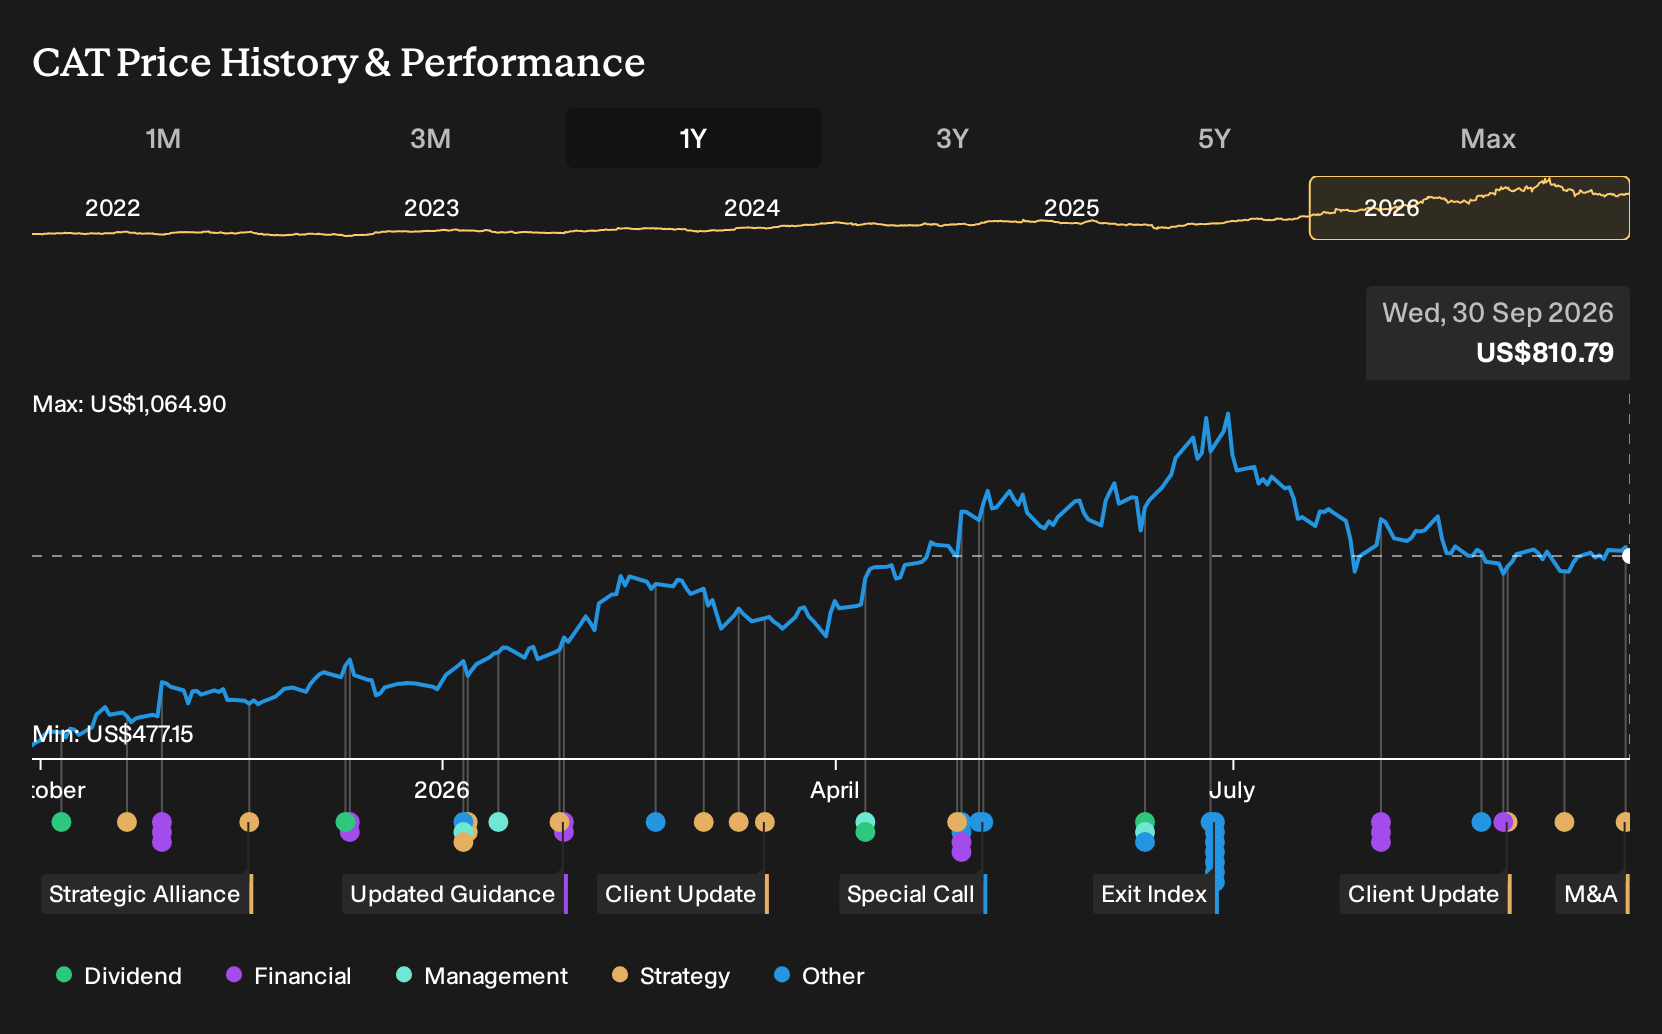
If you only skimmed the headlines about tariffs, decarbonization pressure and an aging machinery giant, Caterpillar might have looked like a stock to avoid. Holding Caterpillar over the past year would have returned 70.1%, including dividends. If you had been deciding on 30 September 2025, with analysts split between AI-fueled upside and structural margin risk, what should have mattered more: the record backlog story or the fear of long-term erosion in its core markets?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Caterpillar. See which of 39 power grid technology and infrastructure stocks may still merit a closer look.
The Two Caterpillar Stories Investors Had To Weigh
The shares cost US$477 at the start of the period, and anyone looking at Caterpillar then had to decide which of two very different stories sounded more reasonable.
On the bullish side, the Urbanization And Digitalization Will Unlock Long-Term Opportunity narrative put Fair Value at US$512, or 7% above the start price. That view leaned on an elevated backlog, lean dealer inventories, and the idea that digital tools like predictive maintenance could lift high-margin service revenue.
The opposing Rising Tariffs And Decarbonization Will Crimp Long-Term Margins narrative argued for Fair Value of US$308, or 36% below the start price. This camp focused on a US$1.3b to US$1.5b tariff headwind and the risk that global decarbonization would shrink demand for traditional heavy equipment.
What The Evidence Did To The Caterpillar Argument
Caterpillar reported Q2 2026 revenue of US$20.5b versus US$16.6b a year earlier, with net income rising from US$2.2b to US$3.6b and net margin moving from 13.2% to 17.5%. A record backlog above US$70b tied to AI data center power orders and higher construction sales clearly supported the urbanization and digitalization story more than the margin-crimping bear case.
The key lesson is where to focus. When narratives hinge on backlog quality and margin resilience, track whether reported order books, segment demand and net margin actually move in the same direction as the story you are being asked to believe.
What Caterpillar's Run Now Prices In
Caterpillar trades at US$811 today after a 70.1% gain over the past year, while the selected cautious Narrative places its Fair Value below the current price based on multiple valuation cross checks.
The Narrative centers on a mature, cyclical business with strong profitability and disciplined capital use. Anyone paying US$811 is assuming that earnings power and capital returns stay robust, so the question is how the cited mean reversion in multiples might challenge that belief.
"Caterpillar is a very mature company in a cyclical industry. Its competitive advantages and Wide Moat rating shows on its high operating margin. It grows its revenues around economy growth rate, justified by the maturity of the business, and its dividends a little above it around ~6%."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Caterpillar
Caterpillar links you directly to concrete, steel and earth. AI infrastructure shifts the story into sealed rooms full of humming racks.
Those racks now concentrate enough computing power that air cooling struggles. Heat increasingly needs to move through liquid instead of air alone.
A separate specialist designs power systems and thermal hardware that keep these dense facilities running. Its equipment helps operators move electricity in and push heat out, reliably.
As more AI capacity gathers in these sites, that quiet plumbing gains importance. You decide whether this behind-the-scenes role belongs on your watchlist.
Could this be another way into the opportunity? → Explore the AI infrastructure opportunity and its 41% discount to one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com