


- Illumisoft Lighting Corp. recently engaged Capgemini, including its frog and Synapse units, to advance SaniLux from technology stage to a designed, engineered, and manufacturable product line through coordinated work on design, engineering architecture, supply chain, and commercialization.
- This SaniLux engagement gives Capgemini another complex product development mandate that leans on its cloud, data, and AI-led engineering capabilities, reinforcing how real-world clients are using the group for end to end digital and hardware transformation.
- We will now look at how Capgemini's SaniLux development mandate might influence the broader investment narrative around its digital capabilities.
Scan for other IT and AI-focused consultancies that could capture similar client mandates by running a quick screen of 90 AI infrastructure stocks as this Capgemini news puts digital engineering back in focus.
Capgemini Investment Narrative Recap
To own Capgemini, you need to believe the consulting and engineering mix in cloud, data, and AI can translate into steadier bookings and healthier margins over time. The SaniLux mandate fits that story by showing clients still turning to Capgemini for complex, full stack work. It is helpful evidence, but not a game changing pivot on its own.
The more immediate swing factors remain demand in Europe, pricing pressure as clients push for Gen AI driven savings, and the cost of ongoing restructuring. Any slowdown in manufacturing or consumer exposed sectors, or further margin drag from workforce actions, would matter more to the near term earnings path than this single Illumisoft engagement.
The recent sale of Capgemini Government Solutions to ITC Federal is the announcement that sits closest to the current setup. It tidies the portfolio, reduces exposure to a specific public sector niche, and lets management concentrate on global commercial work where cloud, data, and AI led deals like SaniLux live.
That streamlining cuts both ways. A leaner footprint can sharpen execution around growth areas and help support margins, yet it also removes a revenue stream at a time when parts of Europe remain fragile and net profit margins already sit near 5.9%. For you, the question is whether this refocus tightens Capgemini’s prospects for turning its AI and engineering pipeline into more stable earnings.
Capgemini's current earnings sit at €1.4b, with analyst consensus pointing to €2.1b by 2029, a rise of about €0.7b. Revenue forecasts of €26.9b in that same year rest on the assumption of 4.7% yearly top line growth over the next few years.
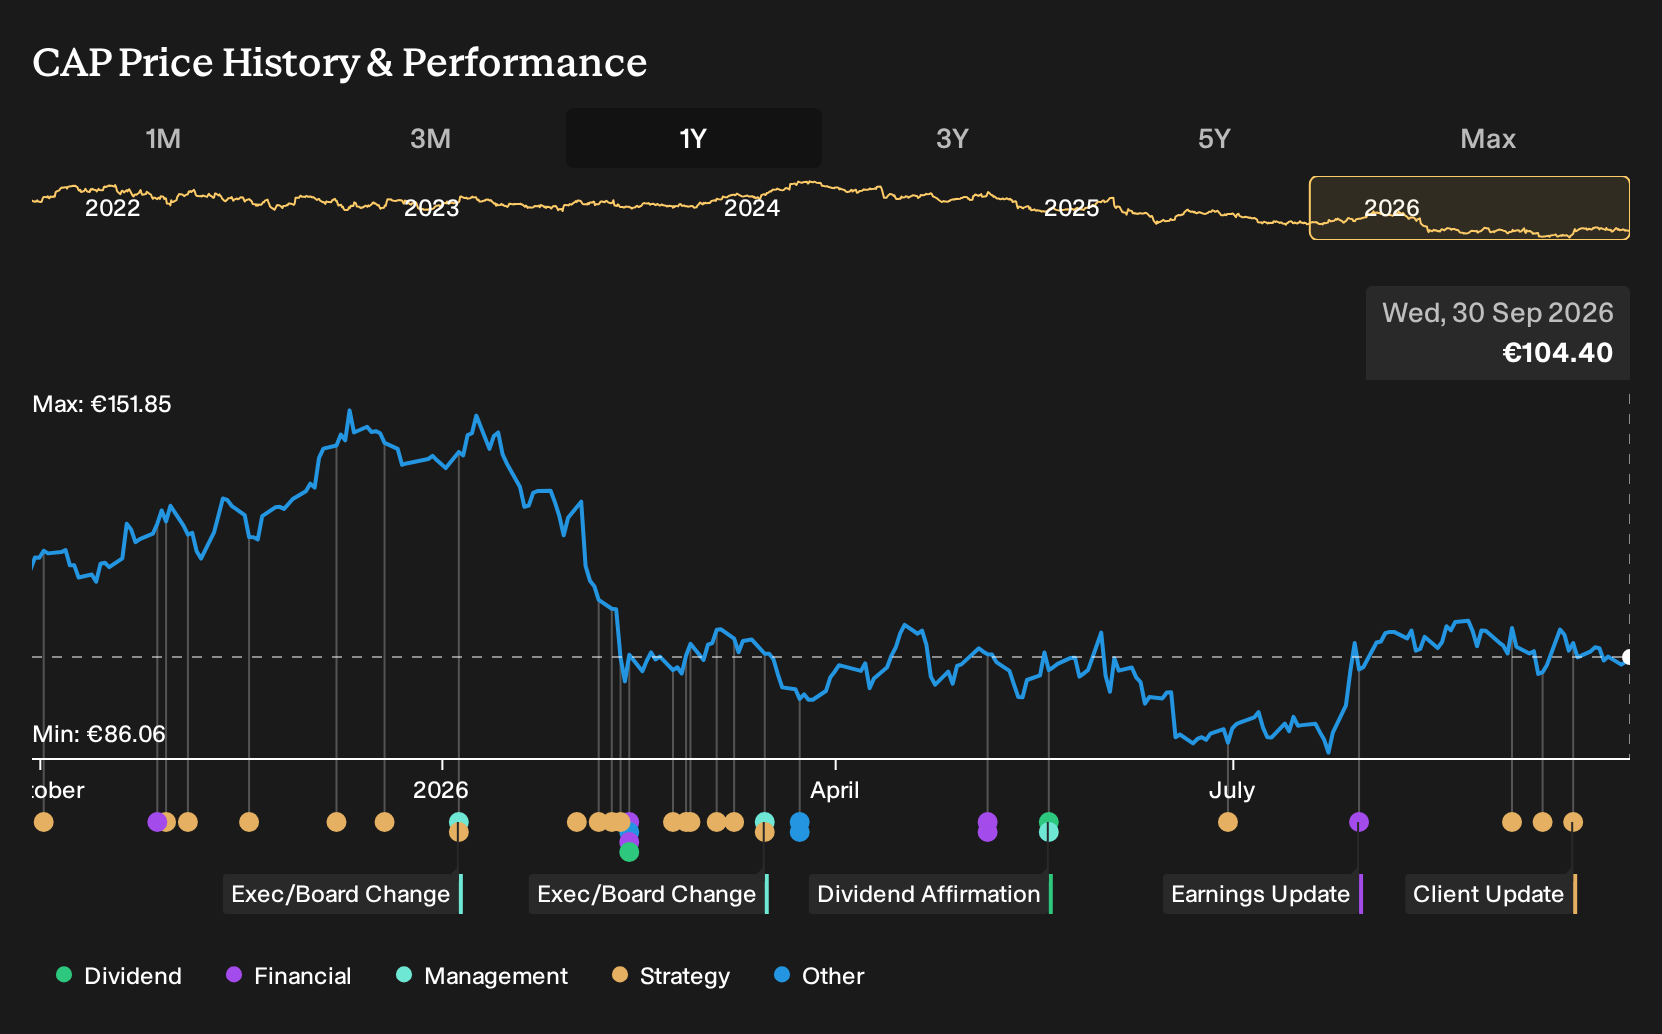
Uncover why Capgemini's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Capgemini focuses on a much stronger AI demand story. The most optimistic analysts were already working with about €28.7b of revenue and €2.5b of earnings by 2029, compared with consensus at €26.9b and €2.1b. You can read this SaniLux news and decide which set of expectations feels closer to your own.
Explore 3 other Capgemini fair value estimates, including one that suggests potential upside of as much as 58% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capgemini research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capgemini. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capgemini's overall financial health at a glance.
Looking For More Investment Ideas Beyond Capgemini?
If the Capgemini story has you thinking more broadly about where to put fresh capital to work, it can help to scan a wider field of opportunities using the Simply Wall St screener before making any decisions.
- For investors who care most about quality at a sensible entry point, consider starting with 196 high quality undervalued stocks that already combine solid fundamentals with pricing that may look relatively undemanding.
- If capital preservation is high on your list, focus on companies with steadier profiles by filtering through 222 resilient stocks with low risk scores that score well on financial strength and volatility checks.
- For readers hunting for underfollowed opportunities rather than the usual large caps, scan 617 high quality undiscovered gems that pair robust metrics with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com