


Lam Research has delivered a powerful run over the past several years, and the share price now puts a clear question in front of investors who focus on earnings. With the stock recently closing at US$328.51, the issue is whether that level is adequately supported by the company’s profit engine.
- Over the past 5 years the stock has returned very roughly 7x. This makes it important to test whether that kind of move is matched by Lam Research’s earnings power.
- Recent commentary around demand for semiconductor equipment tied to memory and AI infrastructure, along with expectations for strong wafer fab and packaging activity, can support the view that Lam Research’s future profit stream may be more heavily front loaded than in past cycles.
- Your read on Lam Research is one view; the desks covering it have another. See what analysts think Lam Research's shares could be worth.
The stock’s next move may depend on whether the current price can be explained by Lam Research’s earnings when judged against the Fair Ratio benchmark.
If you want a second reference point alongside Lam Research for how earnings stories line up with current prices, run the same Fair Ratio lens across 90 AI infrastructure stocks.
Is Lam Research Getting Expensive on Earnings?
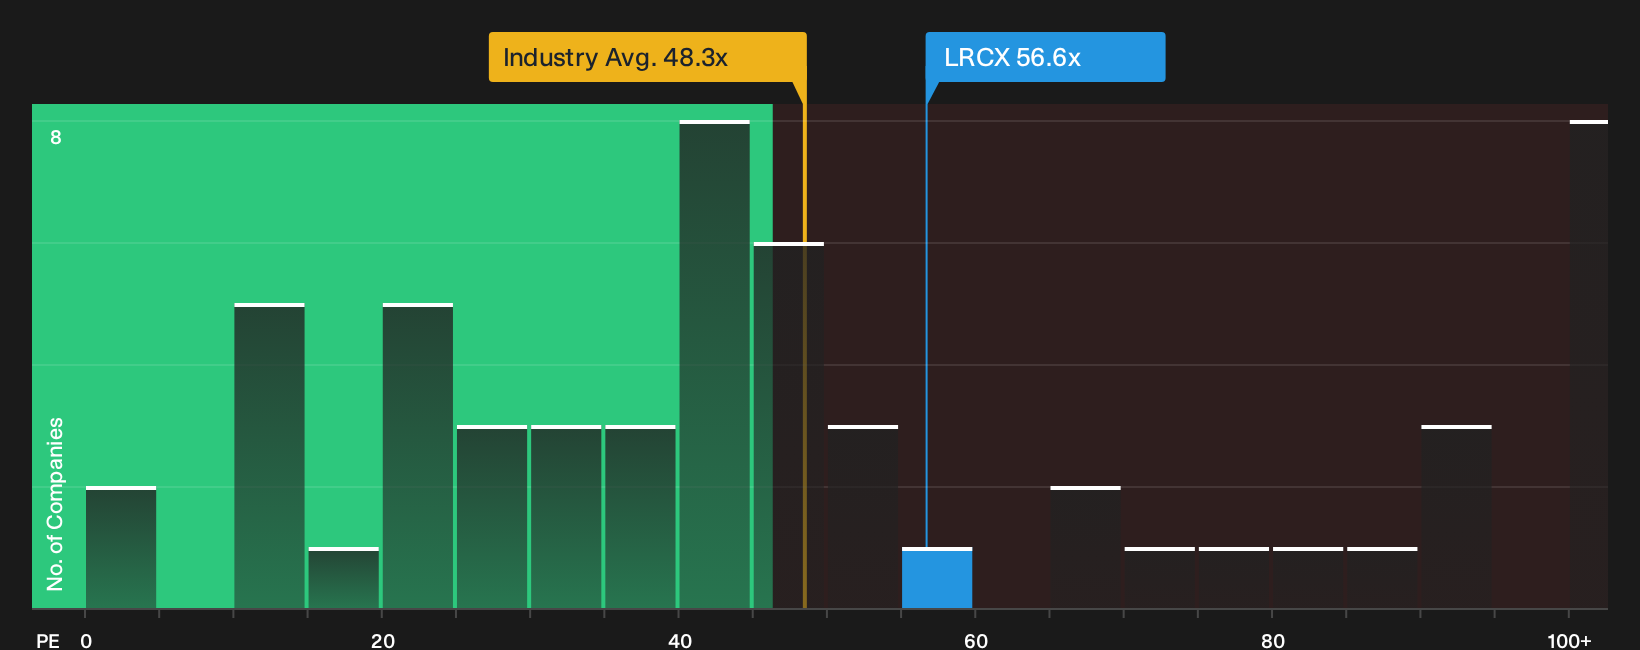
The P/E ratio fits Lam Research because earnings are the main anchor for how investors frame the story here. On that lens, the stock trades at about 56.6x earnings, which is higher than both the semiconductor sector average near 48.3x and the peer group around 49.0x. Against that backdrop, the Fair Ratio model, which estimates the multiple you might expect given Lam Research’s growth profile, margins, size and risk, sits below the current P/E, so the shares screen as overvalued on this framework.
Recent commentary that Lam Research could benefit from heavier spending on AI related wafer fab and packaging equipment helps explain why investors are willing to pay a premium multiple. Yet even with that enthusiasm, the P/E still comes in above the tailored Fair Ratio benchmark. For you as a shareholder or potential buyer, the key question is whether the earnings outlook and cash generation you expect are strong enough to justify that richer tag on profits. Explore the numbers behind Lam Research's P/E valuation.
The Lam Research Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Lam Research pick up where the valuation puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the stock to appear meaningfully cheaper or more expensive than it does today on the screen. Each narrative links its number to a specific view on how Lam Research's growth, margins and risk profile could evolve, giving you a reference point you can return to as new information appears.
Community views on Lam Research are split between investors who see a memory driven opportunity and those focused on policy and margin risks.
Bull case: 22% undervalued
"Lam has greater operating leverage to memory and layer-count growth than any of them, and it owns the specific process steps…"
Discover why this Narrative puts Lam Research at 22% undervalued.
Bear case: 13% overvalued
"The increasing risk of deglobalization and stricter export controls on semiconductor tools, particularly concerning China, could severely constrain Lam Research's future revenue growth…"
Explore why this Narrative puts Lam Research at 13% overvalued.
Before acting on Lam Research's valuation, there is one more angle to check
Price and earnings frame the Lam Research story, but the people deciding how to allocate capital, set priorities and reward themselves can tilt that story in your favor or against you. See who runs Lam Research and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com