


Konami Group (TSE:9766) has put income investors back on alert after declaring a total dividend of $0.70 per share, with the ex-dividend date on 29 September 2026.
Konami Group’s latest dividend headline lands while the share price has climbed 21.22% over the past 90 days and the 3-year total shareholder return sits near triple the original investment, signalling momentum that income holders will want to weigh against that rapid long term gain.
Scan how Konami Group compares with other income ideas by reviewing our curated list of 19 dividend fortresses for yield-focused portfolios.
That sharp 90 day rise in Konami Group raises a simple tension. Is the market catching up with the underlying business, or has sentiment run ahead of what the current valuation can justify?
Price-to-Earnings of 26.6x: Is it justified?
Konami Group currently trades on a P/E of 26.6x, which sits slightly below an estimated fair P/E of 26.9x but above peer levels, so income holders are being asked to pay a premium multiple on recent earnings while the stock price sits at ¥22,140.
The P/E ratio compares the share price with earnings per share. For a business like Konami Group that generates profits from digital entertainment, gaming systems and sports facilities, this metric helps you see how much investors are willing to pay for each unit of current profit.
Earnings growth has been strong, with profit rising 49.6% over the past year and averaging 19.4% per year over five years. Forecasts point to earnings expanding 9.32% per year, slightly ahead of the wider JP market at 9.2% per year. That helps explain why the stock is judged good value against an estimated fair P/E of 26.9x, even if the absolute multiple is not low. The level the market could move towards, based on that fair ratio, is only marginally above where the shares trade now.
On peer comparisons the picture is tougher. Konami Group screens as expensive on a P/E basis versus the peer average of 22.3x and also compared with the broader JP Entertainment industry at 16.6x, so anyone buying here is accepting a higher entry price than the sector norm for the earnings on offer.
Explore the SWS fair ratio for Konami Group.
Result: Price-to-Earnings of 26.6x (ABOUT RIGHT)
Still, if Konami Group disappoints on profit growth or the recent share price strength cools quickly, that premium P/E could unwind fast.
Find out about the key risks to this Konami Group narrative.
Another View on Konami Group’s Value
The P/E points to Konami Group being roughly fairly priced, yet the SWS DCF model adds a different angle. On that basis, the shares at ¥22,140 sit about 2.7% below an estimated future cash flow value of roughly ¥22,766. That is a small cushion. Is it enough for you?
Look into how the SWS DCF model arrives at its fair value.
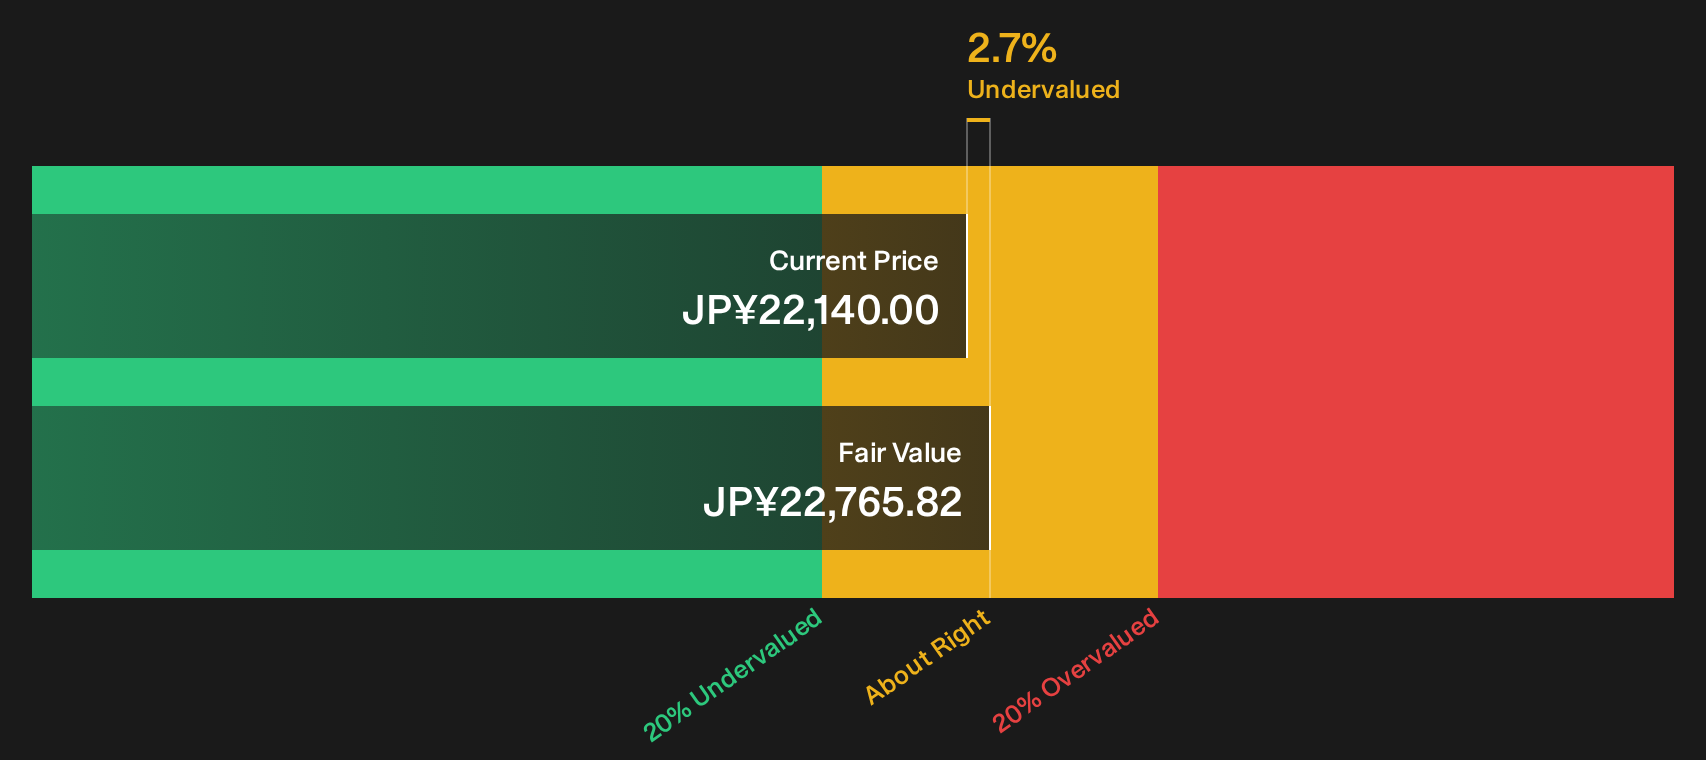
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Konami Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the balance of optimism and concern around Konami Group feel clear enough yet, or just raise more questions for you as an investor? Move quickly to test the numbers, stress test the story against your own expectations, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Konami Group style investment ideas?
Konami Group may already be on your radar, but you do not want your watchlist to stop here when other opportunities could be taking shape right now.
- Target resilient cash generators by scanning a 17 high quality undervalued stocks that combine quality earnings with prices that sit below many investors' expectations.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (23 results) that can better withstand shocks when conditions turn rough.
- Get ahead of the crowd by tracking a 76 high quality undiscovered gems before wider attention and fresh capital start to re-rate them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com