


Uniti Group has delivered a mixed ride for shareholders over the past few years, and the latest swings in the share price put a fresh spotlight on whether the current valuation lines up with what its earnings can support. With the business preparing to merge with Windstream and shift away from its REIT structure, the key issue is how this new setup should influence what investors are willing to pay for Uniti Group’s profit stream.
- Over the past 5 years the stock has fallen 45.8%. This puts long term holders squarely on the question of whether today’s earnings justify sticking with the story at the current price.
- The planned merger with Windstream and move away from a REIT model may reshape how investors think about Uniti Group’s earnings quality, future telecom cash flows and the capital needed to support that transition.
- The analysts covering Uniti Group have run their own numbers. See what analysts think Uniti Group's shares could be worth.
The issue now is whether Uniti Group’s current share price is justified by its earnings when viewed through this lens.
If you want to test the same earnings question you are asking about Uniti Group across a wider set of companies, take a look at 31 high quality undervalued stocks.
Is Uniti Group a Bargain on Earnings?
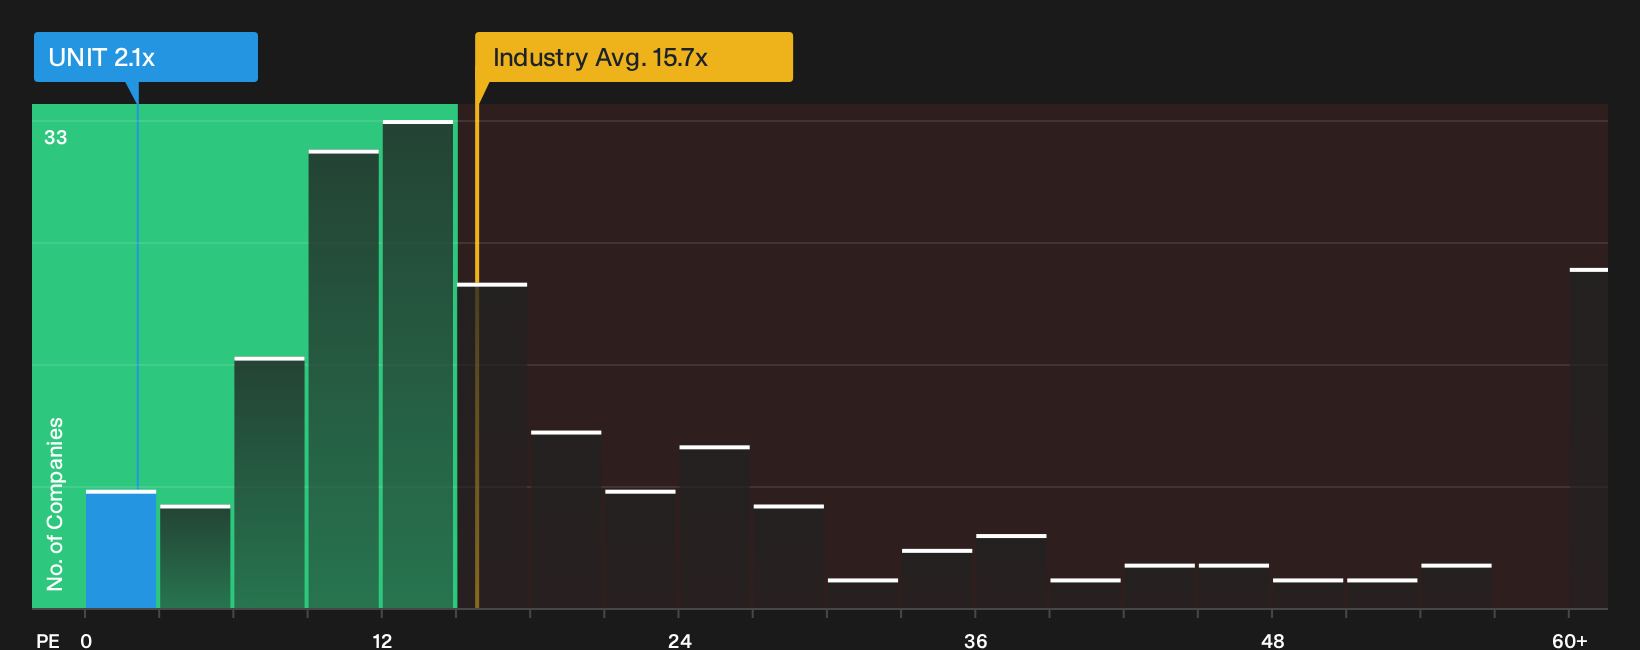
The P/E ratio is useful for Uniti Group because the merger and REIT exit put the focus squarely on what investors pay for each dollar of earnings. On this metric, Uniti Group trades at about 2.1x earnings, while the wider Telecom industry average sits near 15.7x and the peer group is around 7.8x. Relative to the fair P/E level implied by its own earnings profile, balance sheet and risk mix, the current multiple screens on the low side, which suggests that the stock may be undervalued on this framework.
Because the merger with Windstream pulls Uniti Group away from a REIT structure and toward a more conventional telecom profile, the gap between its 2.1x P/E and broader sector norms takes on added weight for investors trying to judge how much of that transition is already reflected in the price. In light of that pending shift, the earnings multiple still prices Uniti Group at a clear discount to both industry and peer benchmarks, leaving room for readers to question whether the current earnings stream is being fully credited. Explore the numbers behind Uniti Group's P/E valuation.
The Uniti Group Narrative: What Would Justify Today's Price?
Narratives for Uniti Group pick up where the valuation puzzle leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the current share price to look meaningfully high or low. Each one treats fair value as a thesis about how the business might develop that you can track over time, and they are available on Simply Wall St's Community page.
Community views on Uniti Group are split between a fiber buildout story that looks mispriced and a balance sheet that some think still carries a lot of risk.
Bull case: 18% undervalued
"Aggressive expansion of fiber-to-the-home coverage, with plans to reach 3.5 million homes passed and 75% fiber-based revenue by 2029, positions Uniti to capture accelerating demand..."
Discover why this Narrative puts Uniti Group at 18% undervalued.
Bear case: 20% overvalued
"Uniti's highly leveraged capital structure, with net leverage expected to remain between 5.5 and 6 times, leaves the company exposed to long-term increases in interest rates or tightening credit conditions..."
Explore why this Narrative puts Uniti Group at 20% overvalued.
The Uniti Group story is bigger than the share price alone
Valuation only tells part of what you need to know about Uniti Group, because separate checks on the business have thrown up caution flags that deserve a closer look before you decide what to do next. Take a closer look at 3 warning signs (3 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com