


Lattice Semiconductor’s Index Addition Sets The Stage
Lattice Semiconductor (LSCC) was recently added to the PHLX Semiconductor Sector Index, putting the roughly US$17.8b FPGA specialist in front of a wider pool of institutional investors and benchmarked funds.
Recent price action has been strong around these developments, with Lattice Semiconductor’s share price up 15.38% over the past month and 63.84% year to date, while its 1-year total shareholder return of 76.84% points to momentum that has extended beyond the latest index inclusion and product launches.
Scan other FPGA and chipmakers showing similar index-driven momentum with our curated list of 90 AI infrastructure stocks as capital chases the next wave of semiconductor infrastructure leaders.
Lattice Semiconductor now trades at US$128.86 after a sharp run, while analyst targets and intrinsic value estimates point to a wide band of outcomes. Where does fair value really sit in that spread?
Most Popular Narrative: 21.9% Undervalued
The most followed valuation view pegs Lattice Semiconductor’s fair value at $164.92, well above the recent $128.86 close. This puts a spotlight on whether the current price fully reflects its growth story and recent AMI acquisition.
The ongoing AI and edge computing boom is driving hyperscale data center spend and increasing Lattice's attach rate as a companion chip for AI accelerators, servers, and networking equipment, leading to higher ASPs and robust design wins. This should accelerate revenue growth and support gross margin expansion.
See why 25 investors see Lattice Semiconductor as 22% undervalued.
The narrative uses an 11.21% discount rate and factors in revenue growth assumptions of about 45% a year and a long term profit margin of roughly 26%. It then brings those projected cash flows back to today’s dollars to reach the $164.92 estimate.
Analyst forecasts in that framework also rely on earnings stepping up from $36.3m to $525.1m by around August 2029, with disagreement between the most optimistic and most cautious views. The fair value range therefore reflects a material spread of possible outcomes rather than a single precise point.
At today’s $128.86 level, the narrative implies investors are paying below that modeled fair value while still accepting a future P/E of about 68x, which is higher than the 50.9x used for the broader US semiconductor group in the same analysis.
Result: Fair Value of $164.92 (UNDERVALUED)
Still, the bullish script for Lattice Semiconductor can break if competition in low and mid range FPGAs undercuts pricing, or if China related regulations tighten further.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View: Lattice Semiconductor Looks Expensive On Sales
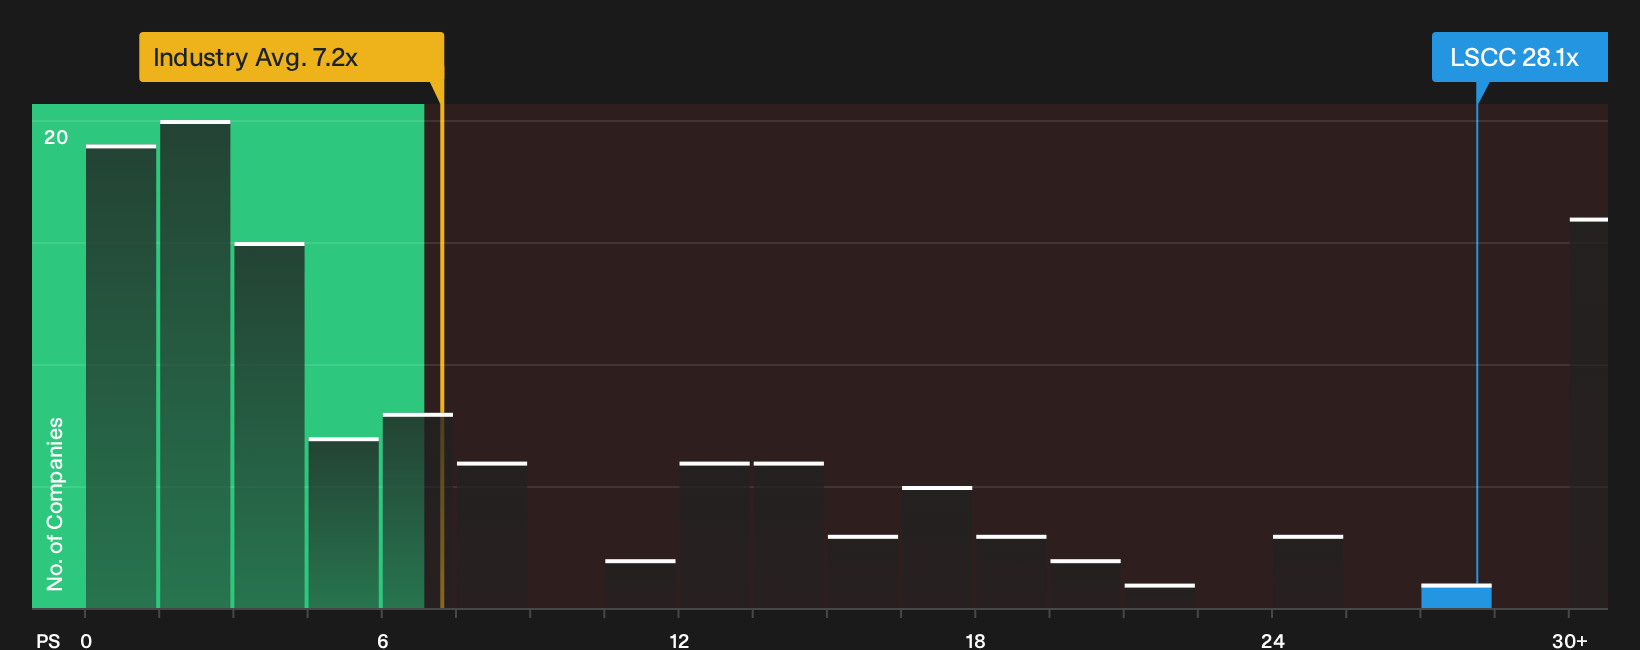
The story changes when the focus shifts from analyst fair value to what investors are paying for each dollar of Lattice Semiconductor’s revenue. On a P/S of 28.1x, the stock trades at roughly 4x the US semiconductor industry average of 7.2x and about 4x the peer group at 6.7x.
The fair ratio is 18x, so today’s gap suggests investors are already paying a heavy premium for growth and execution. The question is simple: how comfortable are you if the market decides that 18x sales is where Lattice Semiconductor should trade instead?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Lattice Semiconductor is split, with real enthusiasm meeting real concern. Consider moving quickly, reviewing the data, and weighing both sides by checking the 2 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Lattice Semiconductor?
If you stop with Lattice Semiconductor, you miss a bigger opportunity set. Use the Simply Wall St Screener to surface fresh ideas while others stay narrowly focused.
- Hunt for quality trading at a discount by scanning our curated pool of 27 high quality undervalued stocks that combine strong fundamentals with appealing prices.
- Strengthen your portfolio’s resilience with a targeted search across 31 resilient stocks with low risk scores designed to highlight businesses with more stable risk profiles.
- Spot under-the-radar potential by reviewing the 19 high quality undiscovered gems that the broader market may not be watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com