


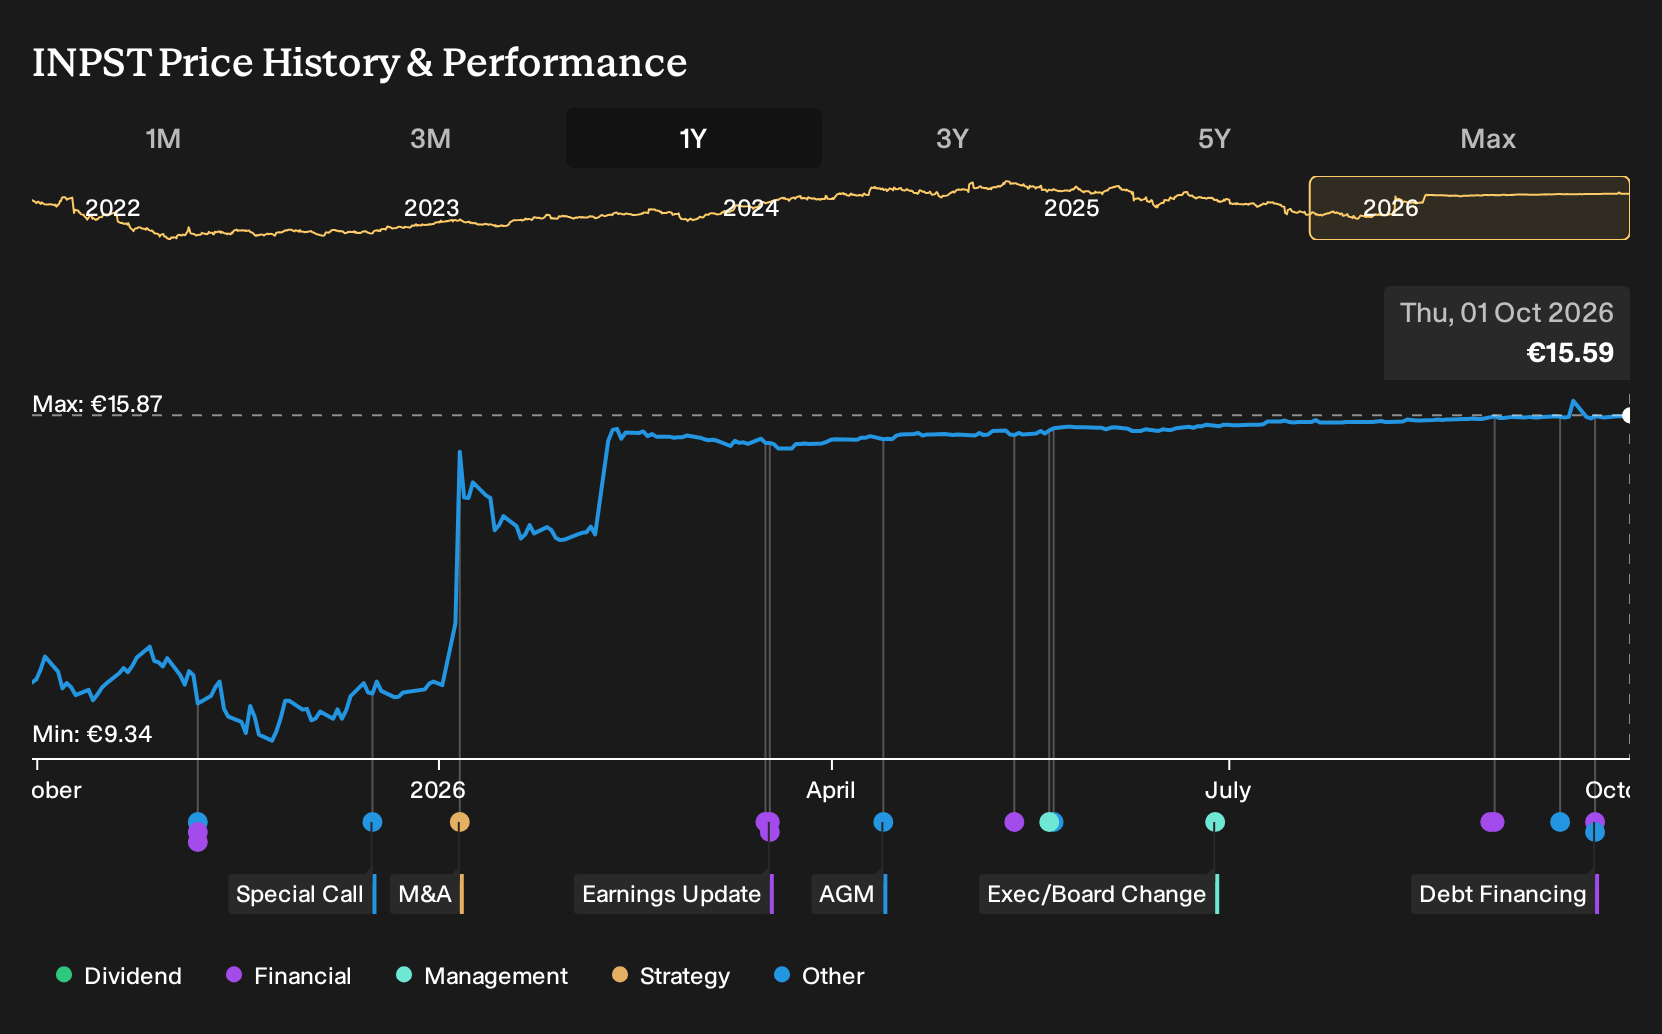
- InPost launched a cash tender offer and consent solicitation for its 4.000% Senior Notes due 2031, targeting up to €849,750,000 of Regulation S notes while excluding Rule 144A tranches unless exchanged into eligible securities.
- InPost was also removed from the S&P Global BMI Index, a shift that can reshape its investor base as index-tracking funds adjust holdings.
- This article examines how InPost's investment narrative is influenced by its index removal and the large-scale Senior Notes tender offer.
Compare how InPost is reshaping its capital structure with a curated shortlist of companies that pair strong finances with cleaner balance sheets using our list of solid balance sheet and fundamentals (207 results)
InPost Investment Narrative Recap
To own InPost, you need to be comfortable with a parcel locker focused model that leans on scale, route efficiency and cross border reach in Poland, the UK and eurozone markets. The key near term upside driver is still execution on network density and acquisition integration, which can influence parcel economics more than index membership changes.
The largest immediate risk remains capital intensity and the pressure that heavy investment and debt put on cash flow and interest cover. The cash tender for the 4.000% Senior Notes tweaks funding mix but does not change that core risk. Removal from the S&P Global BMI Index mainly affects who owns the shares, not how the business operates.
The tender offer for up to €849,750,000 of 4.000% Senior Notes due 2031 is the headline move that ties most directly into current catalysts. It relates to how InPost is managing funding while still supporting growth in lockers, technology and international parcels, where execution quality decides whether forecast revenue and earnings actually materialise.
Debt costs and interest coverage already sit on investor checklists as key watchpoints. This offer, together with the exclusion of certain Rule 144A notes unless exchanged, gives InPost more levers on maturities and structure. Investors still need to watch whether operating cash generation, margin trends and UK integration progress keep pace with the obligations that remain.
InPost's current analyst story assumes revenues reach PLN24.4b and earnings hit PLN2.4b by 2029, based on 16.1% yearly top line growth and an increase in profit from PLN482.8m today to PLN2.4b, roughly a fivefold rise in earnings.
Uncover why InPost's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame InPost’s debt story very differently. They focus on balance sheet capacity, pointing to forecasts that revenues could reach PLN29.0b and earnings PLN3.2b by 2029. Those projections were set before this tender offer and index removal, so that bullish script may be revisited.
Explore 5 other InPost fair value estimates, including one that suggests as much as 49% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your InPost research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for InPost. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InPost's overall financial health at a glance.
Looking for more investment ideas beyond InPost?
Once you have a view on InPost, it can help to compare it with other companies that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about resilience and capital preservation, consider a 223 resilient stocks with low risk scores that aims to keep drawdowns in check while still participating in market upside.
- If you want strong fundamentals without stretched balance sheets, scan a 617 high quality undiscovered gems that combines cleaner finances with business models the market may not fully appreciate yet.
- Income focused readers who prize consistent cash returns can review a 157 dividend fortresses that targets higher yields backed by financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com