


Bassett Furniture stock ripped higher, jumping about 9% today, yet the earnings story that fueled that move is more about repair than euphoria. The market is cheering a cleaner income statement after tariff refunds and tighter cost control, but the real swing factor is profit quality. Management produced Q3 basic earnings per share of about $0.24 on roughly $82.8 million of sales, and the emotion in the share price now hinges on whether that margin improvement feels repeatable or looks like a one quarter assist from refunds and aggressive expense cuts.
Is Bassett Furniture Industries flashing a genuine valuation gap or just wearing a temporarily inflated earnings mask after tariff refunds and aggressive cost cuts? Compare the 32.4% DCF discount with rich P/E multiples and margin pressure in our valuation analysis for Bassett Furniture Industries
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$82.838 million vs. US$80.103 million (up about 3.4%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$2.101 million vs. US$0.801 million (up about 162%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.244 vs. US$0.093 (up about 162%)
- Consolidated Gross Margin (Q3 2026 vs. Q3 2025): 57.5% vs. roughly 56.2% (an improvement of about 130 basis points, helped by cost control and tariff refunds)
Prefer clean charts instead of scrolling through dense earnings tables and footnotes? See Bassett Furniture Industries' full financial picture with an at-a-glance view of its valuation in our company report for Bassett Furniture Industries.
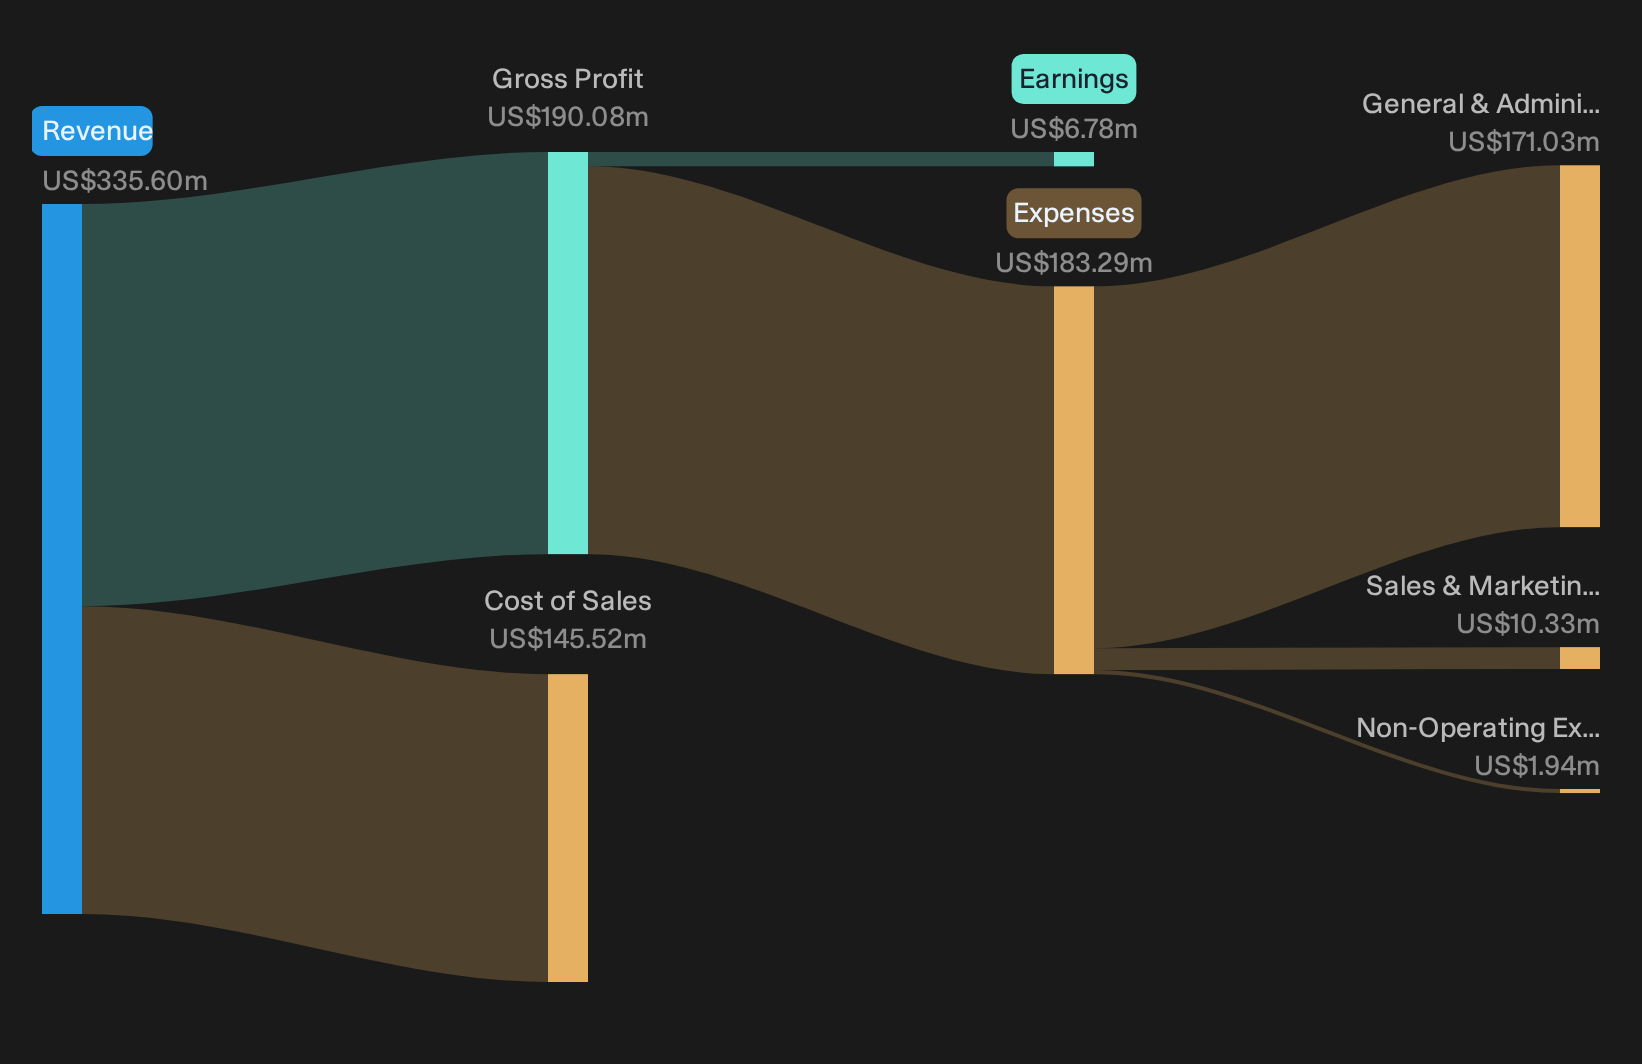
Bassett Furniture bull case meets real operating wins
Bulls argue Bassett Furniture can turn custom, omnichannel and cost discipline into richer earnings without outsized risk. Q3 gives them real checkpoints. Written retail orders rose 4.4% and wholesale written orders climbed 7.9%, which fits the story that Bassett Custom Studio and new assortments are pulling in better quality demand rather than just one off deals. E commerce written sales jumped 48% with website delivered sales up 42% and a 33% lift in average online order value, exactly the kind of higher ticket, upholstery heavy mix the thesis leans on. Gross margin reached 57.5%, helped by tariff refunds and stronger wholesale profitability, while SG&A eased to 53.9% of sales as planned expense reductions started to show up. A US$6.1m operating cash inflow and US$53.4m cash balance support the idea that incremental volume can translate to healthier free cash flow.
Bears focus on fragile margins and promo risk
The cautious view is that Bassett Furniture is leaning on refunds and discounts, not durable pricing power or volume. This quarter does not fully clear that worry. Retail gross profit slipped about 80 to 90 basis points because of heavier promotions on inline goods, even as written orders improved, which indicates that some of the traffic is being “bought” with deals rather than product pull. Tariff refunds of US$1.0m flowing through gross profit lifted reported margin, so the 57.5% consolidated figure does not purely reflect structural efficiency. Management also still describes consumers as cautious and big ticket decisions as slow, which keeps the risk of further discounting alive. Wholesale and Lane Venture shipments look healthy, yet that strength needs to offset any continued retail margin drag. The share price reaction, up about 9.1% today, arrives while these fault lines are still visible in the income statement.
Compare Bassett Furniture Industries' internal progress on orders, margins and cash generation with external expectations. See the consensus price target analysis for Bassett Furniture Industries to gauge whether analysts think this earnings reset supports the current 9.1% post earnings jump or points to a different path from here.
Take Control Of Your Next Move
If Bassett Furniture Industries' mix of tariff refunds, cost cuts and shifting margins has your attention, register for free with Simply Wall St and add it to a Watchlist to track price against fair value and wait for a setup that fits your plan. After you buy or if you already own it, use the Portfolio Command Center to cut through daily headlines and focus on the key updates that matter for your holdings. Over the longer haul, tap into crowd insights through the Community so you can see how other investors are thinking about the same risks and potential catalysts. By spotting both early warning signs and underappreciated drivers, you give yourself a better chance of staying ahead of the market instead of reacting to it late.
Curious About Alternatives Worth Exploring
Fresh ideas move first, and the stocks with real breakout momentum often fly before the crowd even looks up. Scan these under the radar lists while it matters and get in early.
- Chase early momentum in high cash flow businesses by scanning a curated set of underpriced opportunities using the 27 high quality undervalued stocks.
- Spot potential compounding machines with sturdy finances by reviewing the carefully filtered list of solid balance sheet and fundamentals stocks (25 results) before others get caught chasing late moves.
- Hunt for resilient growers with controlled downside by checking the hand picked group of 31 resilient stocks with low risk scores while they are still under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com