


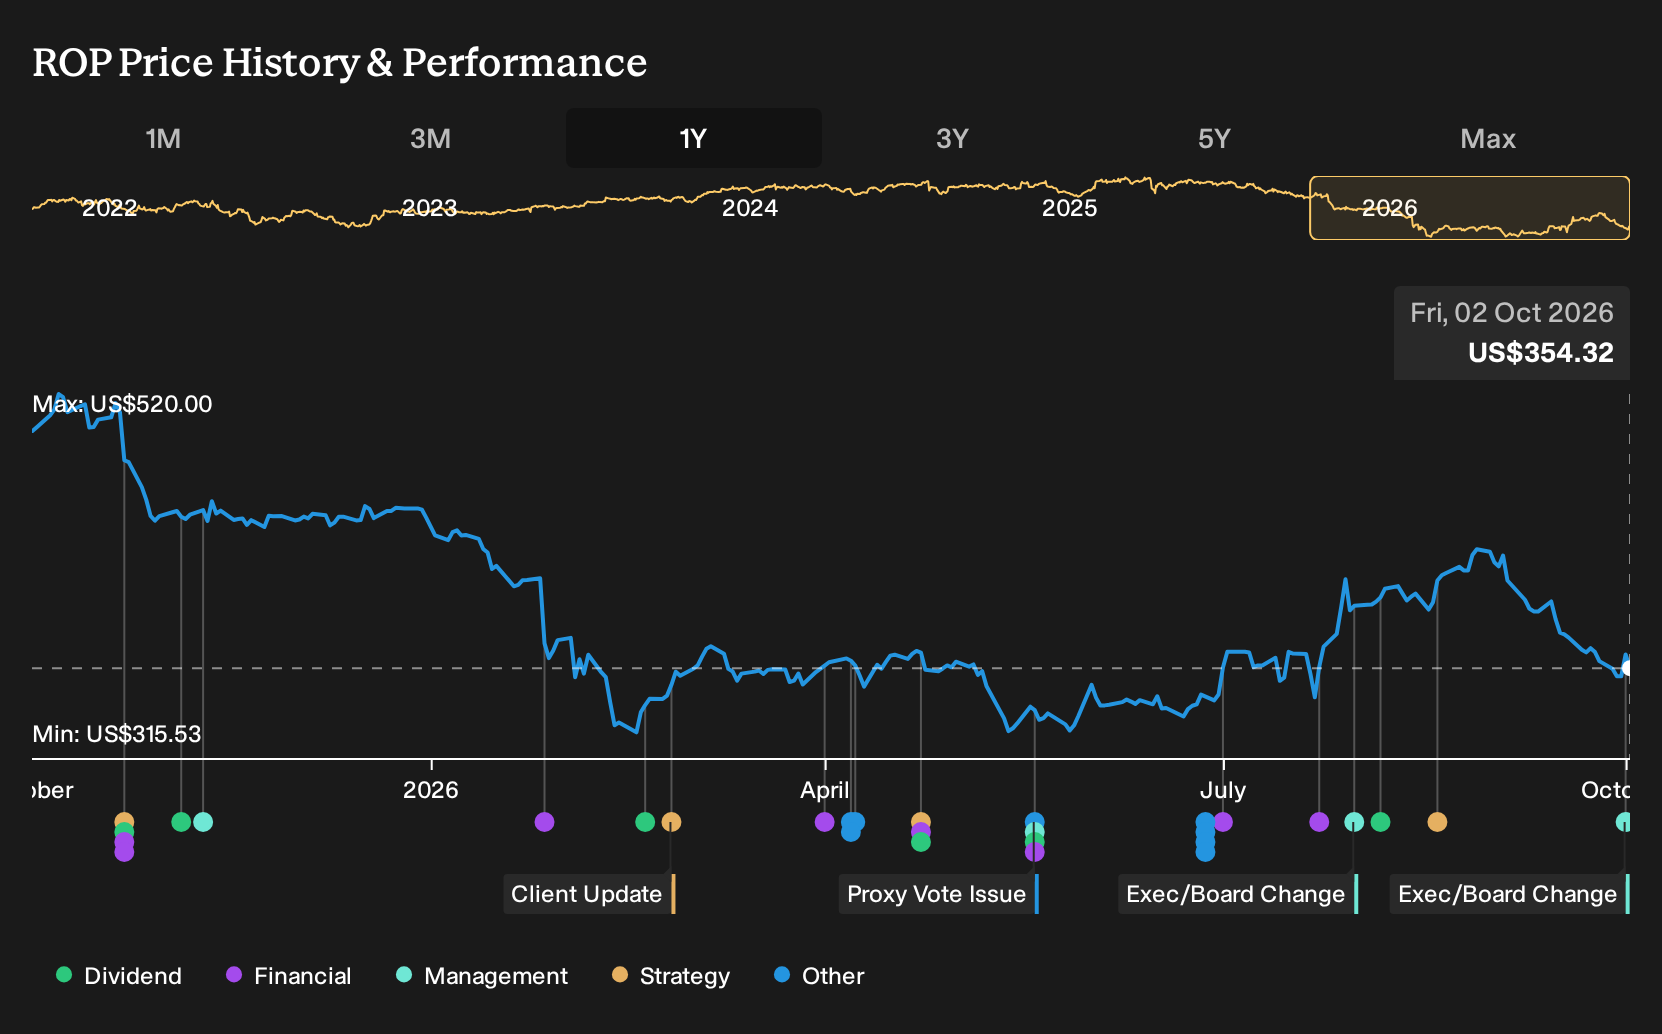
- Roper Technologies recently added Abhijit Dubey, Chief Executive Officer and Chief AI Officer of NTT DATA, to its Board of Directors for a term running until the 2027 Annual Meeting of Stockholders.
- By bringing in a director who oversees AI strategy and cloud focused transformations across a large global services group, Roper Technologies is signaling interest in refining how AI and software execution are integrated across its diversified vertical software portfolio.
- We will now look at how Roper Technologies' investment narrative could be influenced by adding an AI focused director to the board.
Scan how Roper Technologies' AI focused board move compares with other potential beneficiaries of this trend by reviewing the hand picked 37 profitable AI stocks that aren't just burning cash.
Roper Technologies Investment Narrative Recap
Owning Roper Technologies means believing its vertical software portfolio, AI Accelerator program and acquisition engine can keep turning a large, diversified revenue base into steady free cash flow, even as forecasts point to earnings declining about 6.8% a year over the next three years. The immediate swing factor is execution around software M&A and AI product rollouts, with Dubey’s appointment more of a long term capability upgrade than a near term catalyst.
The biggest near term risk still sits in acquisition quality and integration, plus softer demand in areas like government related software and freight exposed logistics tools. AI competition also hangs over the story. Dubey’s AI background may help Roper Technologies sharpen product and pricing decisions, but the impact on near term financials is uncertain and likely limited.
The upcoming third quarter 2026 earnings release on October 22 is the announcement that matters most next to the board change. This update should give you a clearer read on how Roper Technologies is handling weaker pockets of demand, the contribution from recent deals and whether the AI Accelerator is feeding into tangible product wins or usage trends.
That earnings call also arrives shortly after Dubey joins the board. This means any commentary on AI product pipelines, customer interest in automation or capital deployment toward earlier life cycle software assets will be watched closely. Investors focused on catalysts are likely to pay attention to organic growth in key platforms, any color on the US$5b acquisition capacity and how management frames AI disruption risk across its 29 businesses.
Roper Technologies' current analyst script points to revenue of US$10.0b and earnings of US$2.1b by 2029, built on 6.5% yearly revenue growth and an earnings decline of US$0.4b from US$2.5b today.
Discover how Roper Technologies' fair value points to a 26% potential upside to its current price, which could materialize more quickly than many investors anticipate.
Exploring Other Perspectives
Roper Technologies’ board change looks very different if you focus on AI commercialisation risk. The most optimistic analysts were already assuming around US$11.0b of revenue and US$2.3b of earnings by 2029, compared with consensus at US$10.0b and US$2.1b. Their pre news view relies on faster AI uptake, which may now be revisited.
Explore 3 other Roper Technologies fair value estimates, including one that suggests as much as 41% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Roper Technologies research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Roper Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roper Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Roper Technologies?
Once you have a view on Roper Technologies, it often helps to compare it with other opportunities that share similar qualities around quality, income or resilience. The Simply Wall St Screener can help you quickly surface a focused set of potential ideas that match the type of portfolio you want to build.
- If you care most about quality at a reasonable entry point, start with a 31 high quality undervalued stocks that may offer a margin of safety based on fundamentals.
- Income focused investors who want cashflow from their holdings can review a curated group of 7 dividend fortresses that prioritise stronger yields.
- For those who put balance sheet strength first, filter for a list of solid balance sheet and fundamentals (26 results) that can better withstand tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com