


Federal cabinet minister Evan Solomon recently pointed to ATS (TSX:ATS) as a key beneficiary of Ottawa’s new Productivity Mega Deduction, which lets businesses immediately expense eligible asset investments for tax purposes.
Despite the tax incentive spotlight, ATS’s share price has been under pressure. The 90 day share price return is down 34.72% and the year to date share price return is down 32.03%, while the 1 year total shareholder return has declined 30.65%. This suggests that investors are still reassessing its risk and growth profile even as policy support builds in the background.
Scan beyond ATS and compare how other automation and industrial specialists are pricing in similar policy tailwinds by reviewing our hand picked 90 robotics and automation stocks today.
After a slide this steep in ATS, the tax break and recent earnings profile pull investors in opposite directions. Does the current valuation still compensate you for the business risk you are taking on?
Most Popular Narrative: 31% Undervalued
On the most followed view, ATS screens as materially cheaper than its estimated fair value of CA$37.76, compared with the last close at CA$26.04. For that thesis to hold, the business needs to convert automation demand and margin ambitions into much stronger earnings power over time.
The shift toward services, digital solutions, and aftermarket consumables (as seen with products like Connected Care Hub and virtual reality training) is expanding ATS's recurring revenue base, offering more predictable cash flows and contributing to gradual gross margin and adjusted earnings growth.
See why 12 investors see ATS as 31% undervalued.
Result: Fair Value of CA$37.76 (UNDERVALUED)
Still, ATS carries real execution risk if heavy reliance on acquisitions, elevated leverage, and softer bookings keep order visibility and margin ambitions under pressure.
Find out about the key risks to this ATS narrative.
Another View On ATS Valuation
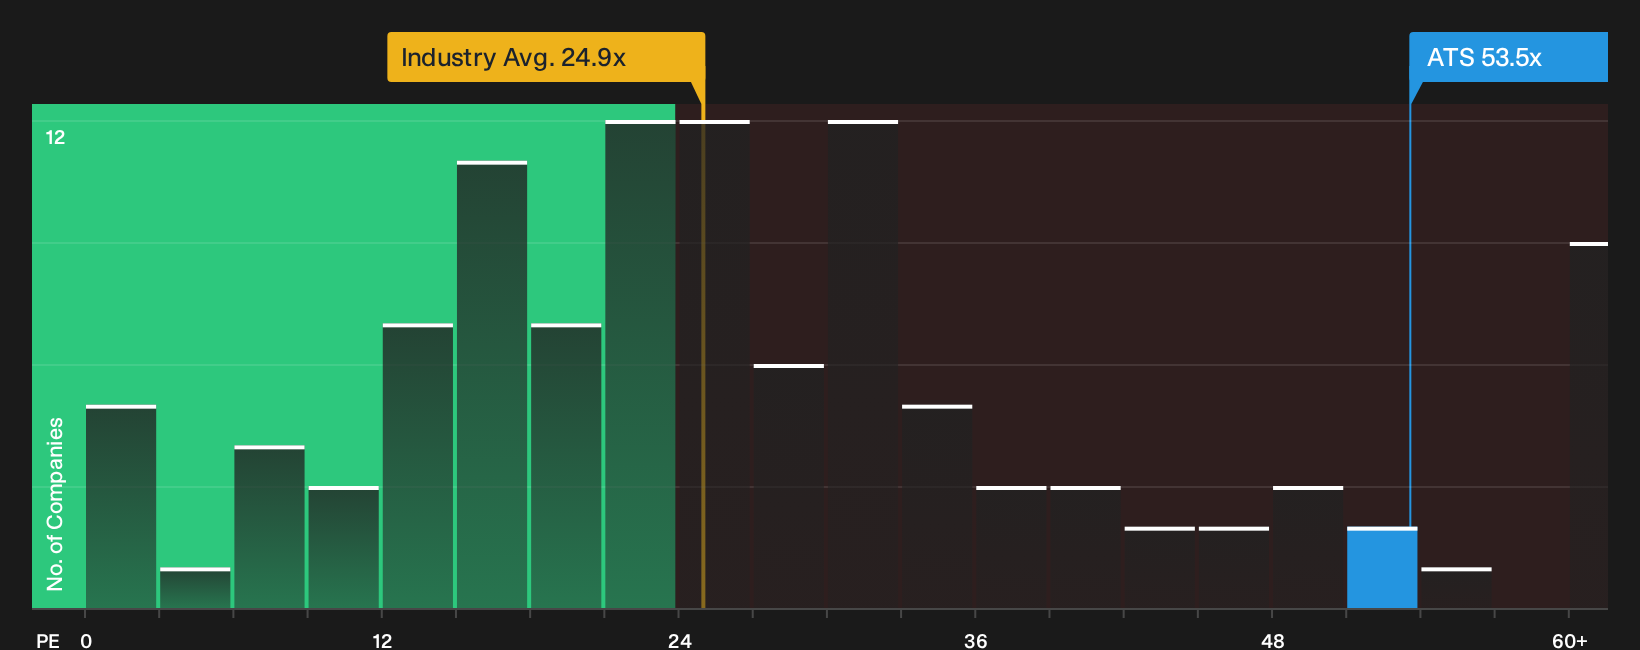
There is a catch. While ATS looks 33% below an estimated fair value on one model, the current P/E of 53.5x is more than double the North American Machinery average of 24x and still above a fair ratio of 59.1x that the market could move toward. That gap points to real valuation risk if earnings do not build as expected. How comfortable are you paying a premium multiple for a business with this recent track record?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around ATS does not have to leave you on the sidelines. Move quickly, assess the upside and downside, then weigh the 3 key rewards and 2 important warning signs.
Looking for more ATS investment ideas beyond this stock?
If ATS has your attention, do not stop here. Broaden your watchlist with a few targeted idea lists that could sharpen your next move.
- Zero in on quality at a discount by reviewing companies that currently screen as 6 high quality undervalued stocks and see which ones merit a closer look.
- Prioritize resilience and sleep better at night by scanning our 8 resilient stocks with low risk scores that focus on businesses with more measured risk profiles.
- Spot potential early movers before the crowd notices by combing through a carefully filtered 9 high quality undiscovered gems that many investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com