


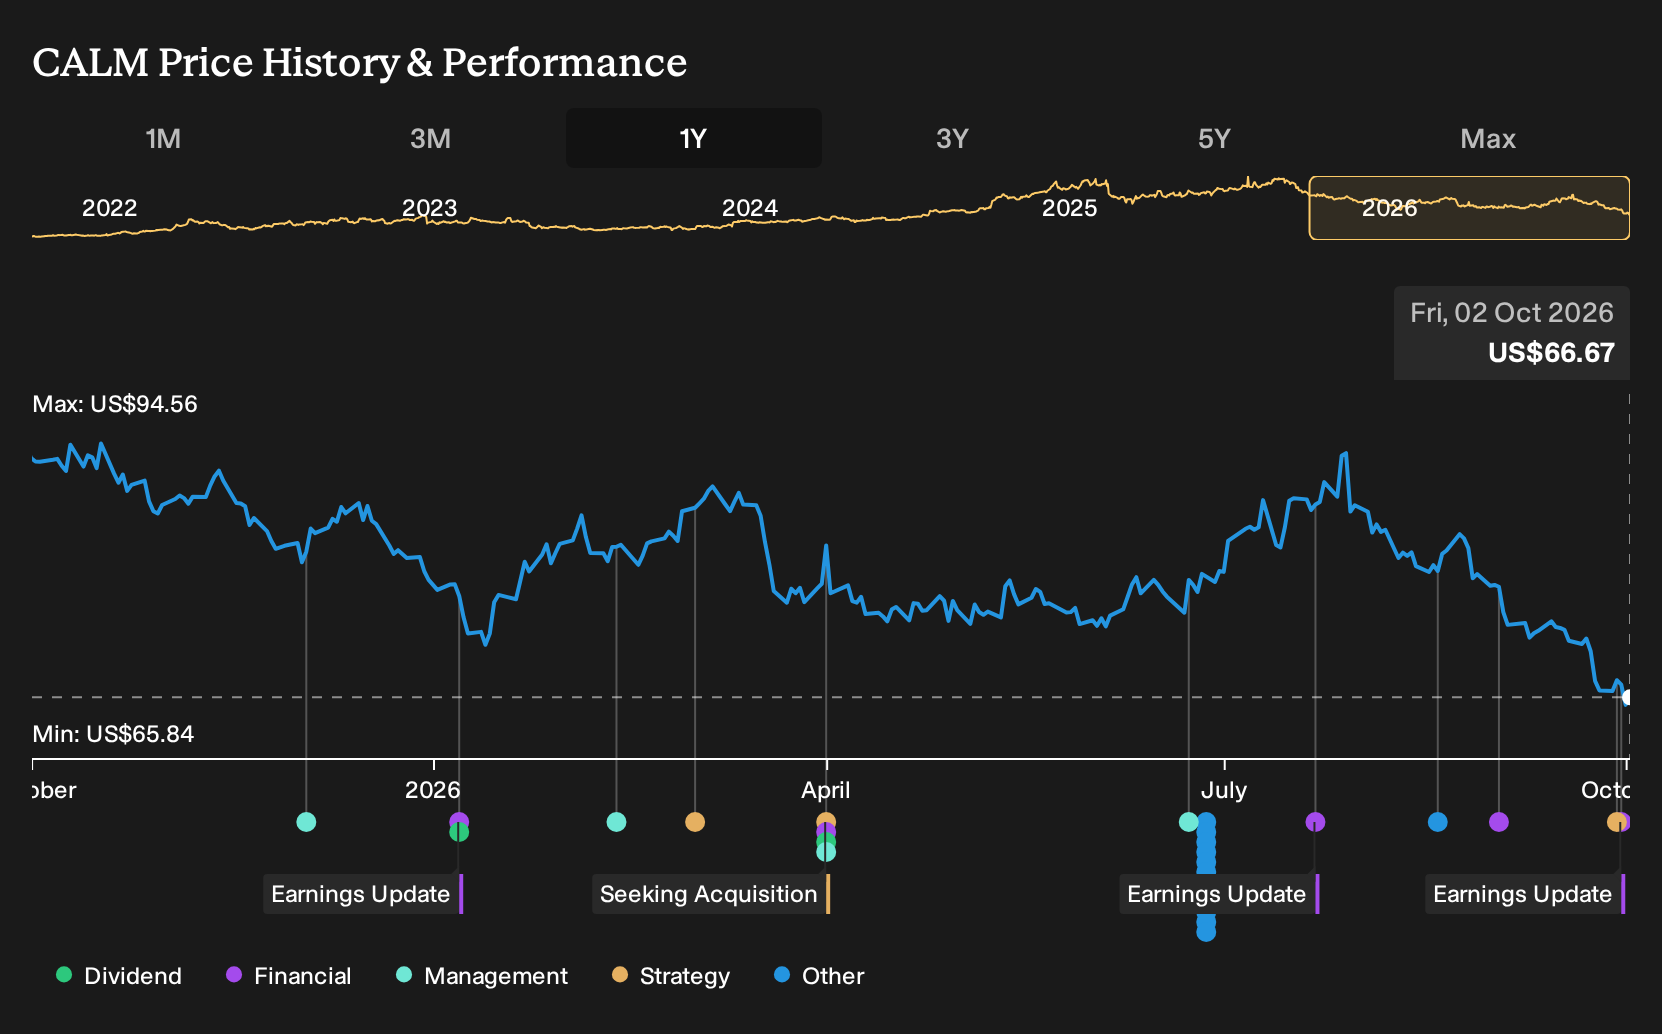
- Cal-Maine Foods reported first quarter fiscal 2027 sales of US$539.61 million and a net loss of US$58.62 million, with both revenue and earnings weaker than the same period a year earlier. Lower conventional shell egg demand and softer pricing pressured profitability and led to a suspended dividend.
- The business continued repurchasing shares and rolled out Amino from Speria MTech Systems to modernize flock and financial data flows. This signaled management focus on operational efficiency even as industry supply imbalances weighed on short term earnings.
- Next, the focus turns to how Cal-Maine Foods' loss and muted egg pricing reshape the investment narrative investors have been using.
Scan beyond Cal-Maine Foods and pressure from muted egg pricing by focusing on resilient balance sheets with the hand picked list of solid balance sheet and fundamentals (26 results) that may better handle similar shocks.
What Is Cal-Maine Foods' Investment Narrative?
To own Cal-Maine Foods, you have to be comfortable with a simple reality. This is an egg producer whose earnings are heavily tied to commodity pricing and flock productivity rather than smooth, predictable growth. The latest quarter underlined that. Revenue of US$539.61 million and a net loss of US$58.62 million reflect how quickly profitability can compress when conventional shell egg demand softens and pricing stays muted. The halted dividend and weaker margins put more weight on operational execution, including the Amino rollout and Prepared Foods capacity projects, as near term swing factors.
For a shareholder, the big picture still revolves around whether Cal-Maine Foods can convert its scale, specialty egg mix and processing footprint into steadier returns through the cycle. Share repurchases suggest management sees value in the equity. At the same time, a P/E of 53x against lower recent profitability and slower forecast revenue growth than the broader US market highlights real execution risk. The new earnings report feeds directly into that debate because it shows how sensitive net income is to small changes in pricing and costs when profit margins sit close to 2.3%.
That said, there is a less comfortable angle to this story that only really comes into focus when you look at...
There's only one way to know the right time to buy, sell or hold Cal-Maine Foods. Head to Simply Wall St's company report for the latest analysis of Cal-Maine Foods's Fair Value.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community span roughly US$16 to US$104, so you are looking at a very wide spread of opinions on Cal-Maine Foods. Those views were formed before the latest loss, suspended dividend and buyback progress, so revisit them and compare several viewpoints before relying on any single number.
Explore 5 other Cal-Maine Foods fair value estimates, including one that indicates as much as 76% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cal-Maine Foods research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cal-Maine Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cal-Maine Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cal-Maine Foods?
If this Cal-Maine Foods update has you rethinking where risk and resilience fit in your portfolio, it can help to scan for other businesses with traits that match your own comfort level. The Simply Wall St Screener lets you filter by financial strength, quality or income focus so you can build a watchlist that fits your approach rather than relying on a single stock story.
- For investors who want income that has some cushion behind it, start with dependable high yielders filtered through the 7 dividend fortresses that screens for payout strength as well as size.
- If capital preservation is front of mind after Cal-Maine Foods' latest results, narrow your search to companies highlighted in the 31 resilient stocks with low risk scores that score well on balance sheet robustness and overall risk profile.
- For readers hunting for quality that is not yet widely followed, broaden your opportunity set with the 19 high quality undiscovered gems that filters for solid fundamentals in under-the-radar stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com