


Rising global bond yields through 2026 have pushed borrowing costs higher, so investors are paying closer attention to companies that can grow from internal firepower rather than cheap debt. Fast growing Indian businesses where founders and executives hold meaningful stakes can be especially interesting, since management feels the impact of every decision. This article highlights three such high growth, high insider ownership stocks from our screener.
The three stocks covered next are just a small sample, and the full screen surfaced 105 more companies with similarly compelling growth stories and insider alignment that are not covered in this article.
If you want to move quickly from ideas to a focused watchlist, head straight into the Fast Growing Stocks With High Insider Ownership screener to identify, compare, and analyze the highest conviction opportunities that fit your own criteria.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical business that develops complex, higher margin formulations using proprietary RubiReten and RubiSRL drug delivery platforms.
Operations: Rubicon Research currently generates about ₹19,358 million in revenue from pharmaceutical products, including generics, specialty drugs, APIs, and related services.
Market Cap: ₹270b
Rubicon Research fits this fast growth and insider alignment theme through its focus on complex dosage forms that can support higher margins and more resilient earnings over time.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
What happens to Rubicon Research’s valuation premium if one key assumption about how this product mix evolves does not play out as expected?
If that assumption is wrong or accelerates faster than expected, read the full narrative for Rubicon Research to see how Rubicon Research’s mix could still reshape investor expectations.

Privi Speciality Chemicals (BSE:530117)
Overview: Privi Speciality Chemicals manufactures and exports specialty aroma and fragrance ingredients used in personal care, home care, and fine fragrance products.
Operations: The business generates about ₹26,711 million in revenue from aromatic chemicals, primarily serving fragrance driven consumer goods applications.
Market Cap: ₹139.5 billion
Privi Speciality Chemicals fits this fast growing, insider aligned theme through its focused fragrance ingredients portfolio. Export demand, capacity expansion, and management confidence all point in the same growth direction.
"Acceleration in fragrance and FMCG demand globally and in India, supported by rising consumption of deodorants, detergents, shampoos and other aroma driven products, may support double digit volume growth and revenue compounding relative to current expectations."
The real swing factor for Privi Speciality Chemicals is how one quiet pressure on future profitability shapes the next leg of that growth story.
That quiet pressure is exactly what the full narrative for Privi Speciality Chemicals unpacks, showing where Privi Speciality Chemicals could see earnings power accelerating rather than stalling.

Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects delivers turnkey EPC solutions for extra high voltage transmission lines and power distribution networks across India and overseas.
Operations: The business generates about ₹27,508 million in revenue from power transmission and power distribution EPC projects and related infrastructure.
Market Cap: ₹18.9b
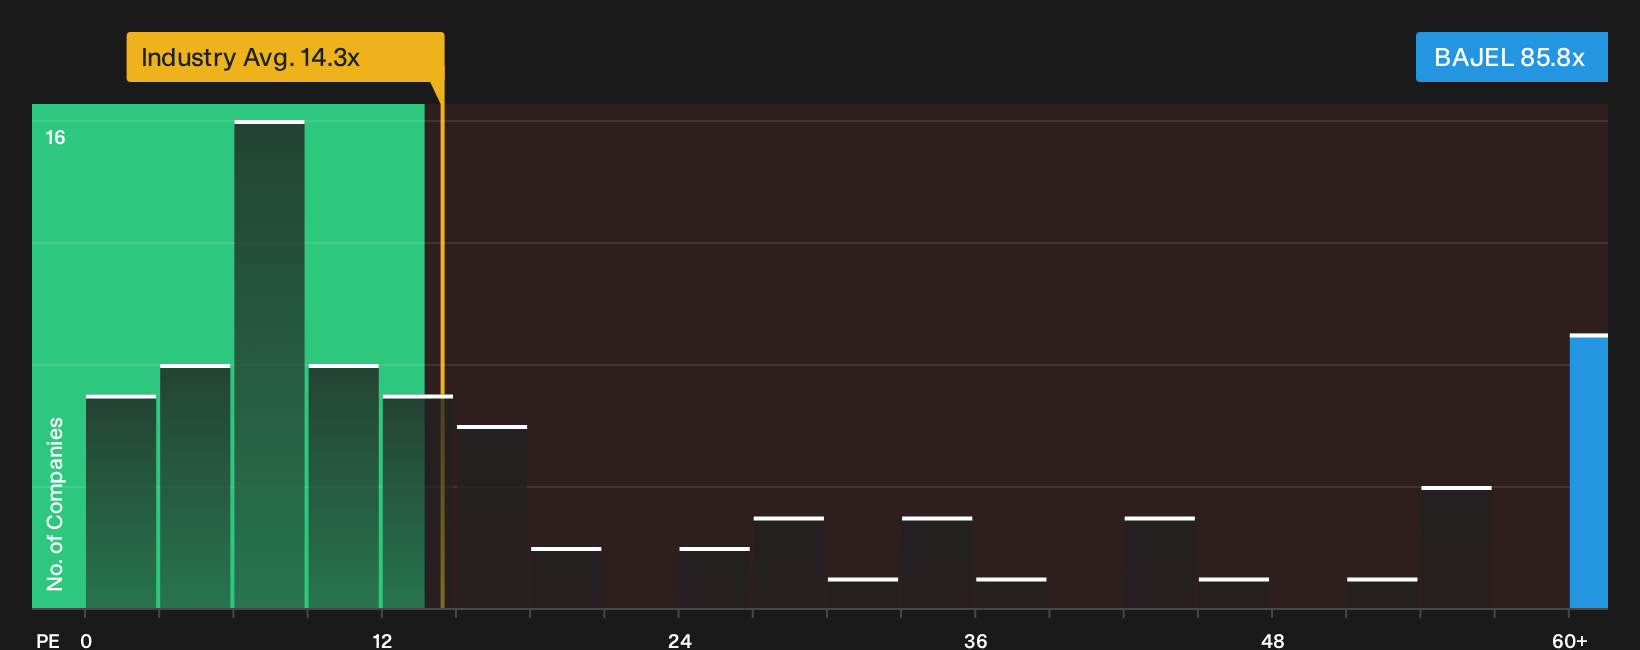
Bajel Projects combines rapid earnings growth, a visible EPC order book in EHV transmission work and high insider alignment. However, it trades on a very rich P/E multiple that already reflects aggressive forecasts, so future returns may hinge on what happens if a single key assumption about project profitability or funding costs shifts even slightly.
That single assumption is where Bajel Projects really gets interesting. Head to the analysis report for Bajel Projects to see how rich expectations could decouple from reality.
Seeking Alternatives Before The Crowd
Fresh ideas move first, and slow money often gets caught chasing momentum once prices start flying. Scan under the radar for now, before information decay bites, and act now.
- Spot potential breakout quality and filter for robust balance sheets using the curated list of solid balance sheet and fundamentals (206 results) while it still sits outside the crowd’s spotlight.
- Ride early momentum in income ideas and track payout durability with the hand picked 168 dividend fortresses before yields start dropping on wider attention.
- Position ahead of possible secular shifts and map future facing infrastructure with the focused 90 AI infrastructure stocks while these opportunities remain quietly priced in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com