


Ambarella has had a mixed stretch in the market, with the stock at US$68.65 after a multi year period where the share price decline over 5 years raises questions about how its cash flows stack up against today's valuation. For anyone following semiconductor designers, the real issue is whether the current quote lines up with what the business can realistically generate in cash over time.
- Over 5 years the share price has fallen 55.5%, which puts the focus squarely on whether the cash the business can produce still supports even the current level.
- The company depends heavily on converting chip design wins into steady cash generation, so any shift in pricing power or development spending can meaningfully change the stream of future cash flows investors are paying for today.
- If you'd rather focus on sales, this one's for you. See why Ambarella's 7.3x P/S tells a different valuation story.
The issue now is whether Ambarella's recent share price, after a weaker year that included a 18.4% decline over 12 months, is properly explained by the cash flows implied in its intrinsic value estimate.
If you are weighing whether Ambarella's price properly reflects its cash flows, it can help to compare that question across a wider group of 31 high quality undervalued stocks
Is Ambarella a Bargain on Cash Flow?
The Discounted Cash Flow model looks at what Ambarella might produce in future free cash and then discounts that back to today. On recent numbers the group generated about $9.98 million in free cash flow over the last twelve months, so the valuation hinges on how that modest base could change as current chip designs move into higher volume production.
Analyst projections used in the DCF assume that free cash flow recovers from a weak 2027 figure into materially higher levels by 2031 and beyond. This implies a shift from tight cash conditions to far more robust inflows if the forecasts play out. Those same projections, when discounted, leave the model’s estimated intrinsic worth meaningfully above the current US$68.65 share price. This suggests the market price does not fully reflect the long term cash generation implied in the DCF inputs. Find out what Ambarella could be worth using our Discounted Cash Flow (DCF) estimate.
The Ambarella Narrative: What Would Justify Today's Price?
Ambarella's valuation story only starts with the DCF puzzle, because the real question is which future path on growth, margins and earnings would actually make the current share price look conservative or stretched. Narratives on Simply Wall St's Community page turn that into concrete scenarios, with each one tying its number to a specific view on where Ambarella's expansion potential, profitability profile and key risks might move next. This gives you something you can revisit as fresh information emerges.
Community views on Ambarella split between those who see edge AI momentum as underappreciated and others who think recent enthusiasm already prices in the story.
Bull case: 23% undervalued
"Sharply increasing demand for AI-powered edge devices, including portable video, robotics, and edge infrastructure, has led to a rapid expansion of Ambarella's addressable markets..."
Discover why this Narrative puts Ambarella at 23% undervalued.
Bear case: 6% overvalued
"Heavy reliance on volatile consumer-facing edge AI markets and single-region supply chains heightens Ambarella's exposure to cyclical downturns and geopolitical risks..."
Explore why this Narrative puts Ambarella at 6% overvalued.
One more Ambarella question that could change the picture
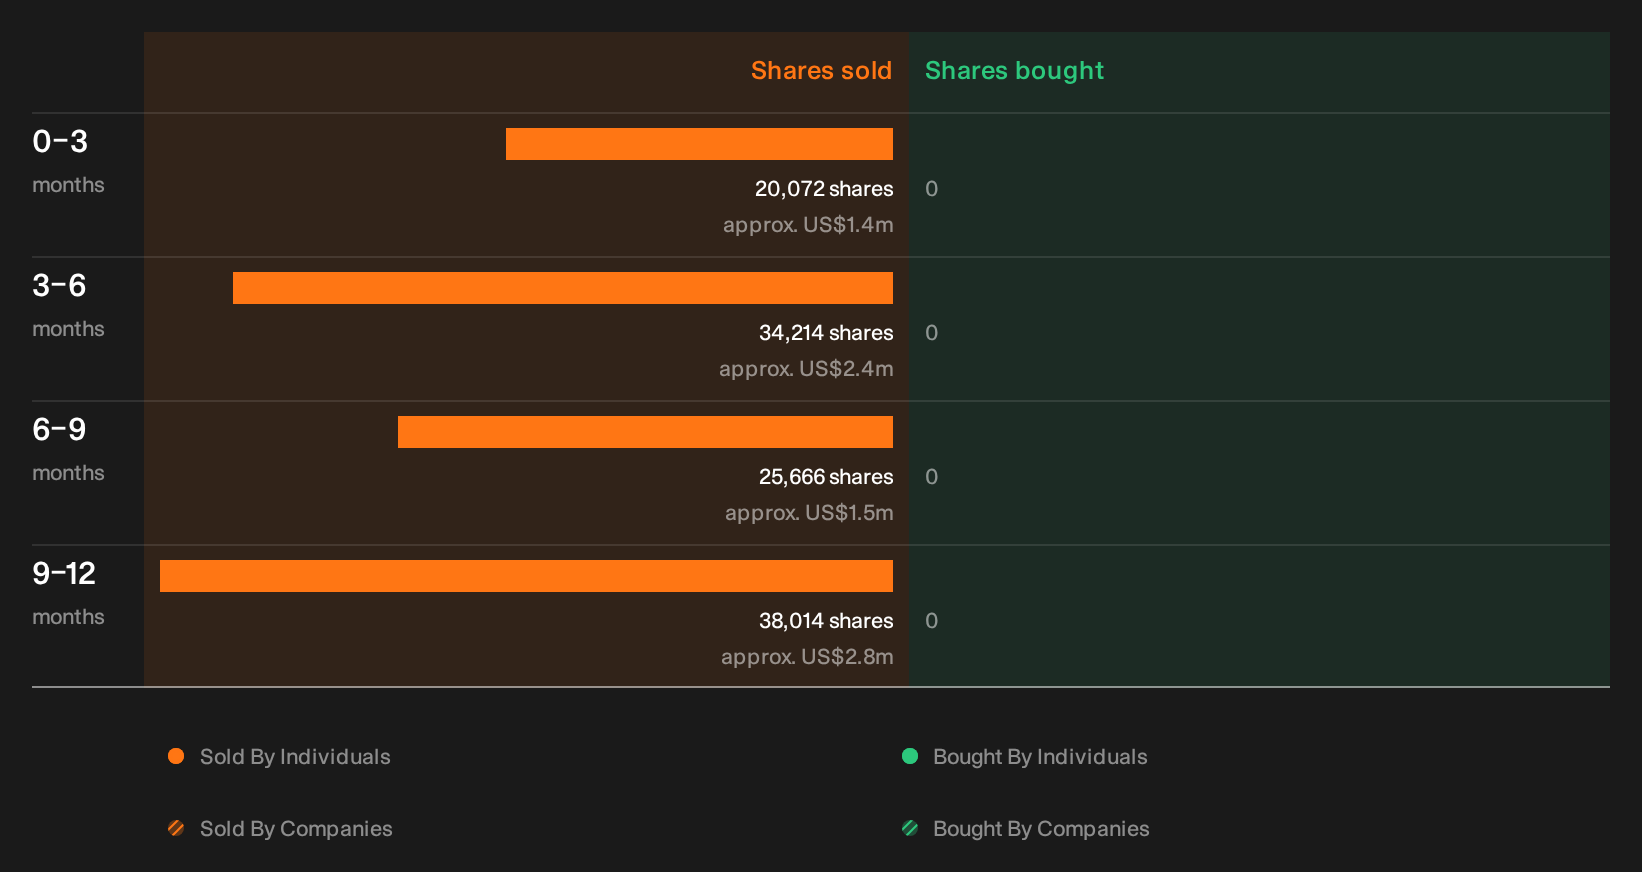
There is one area the cash flow models do not touch. Recent transactions by Ambarella insiders have been flagged by our checks, and the specific executives involved, the sizes, and what they might signal are still for you to review. See the recent insider selling flagged for Ambarella.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com