


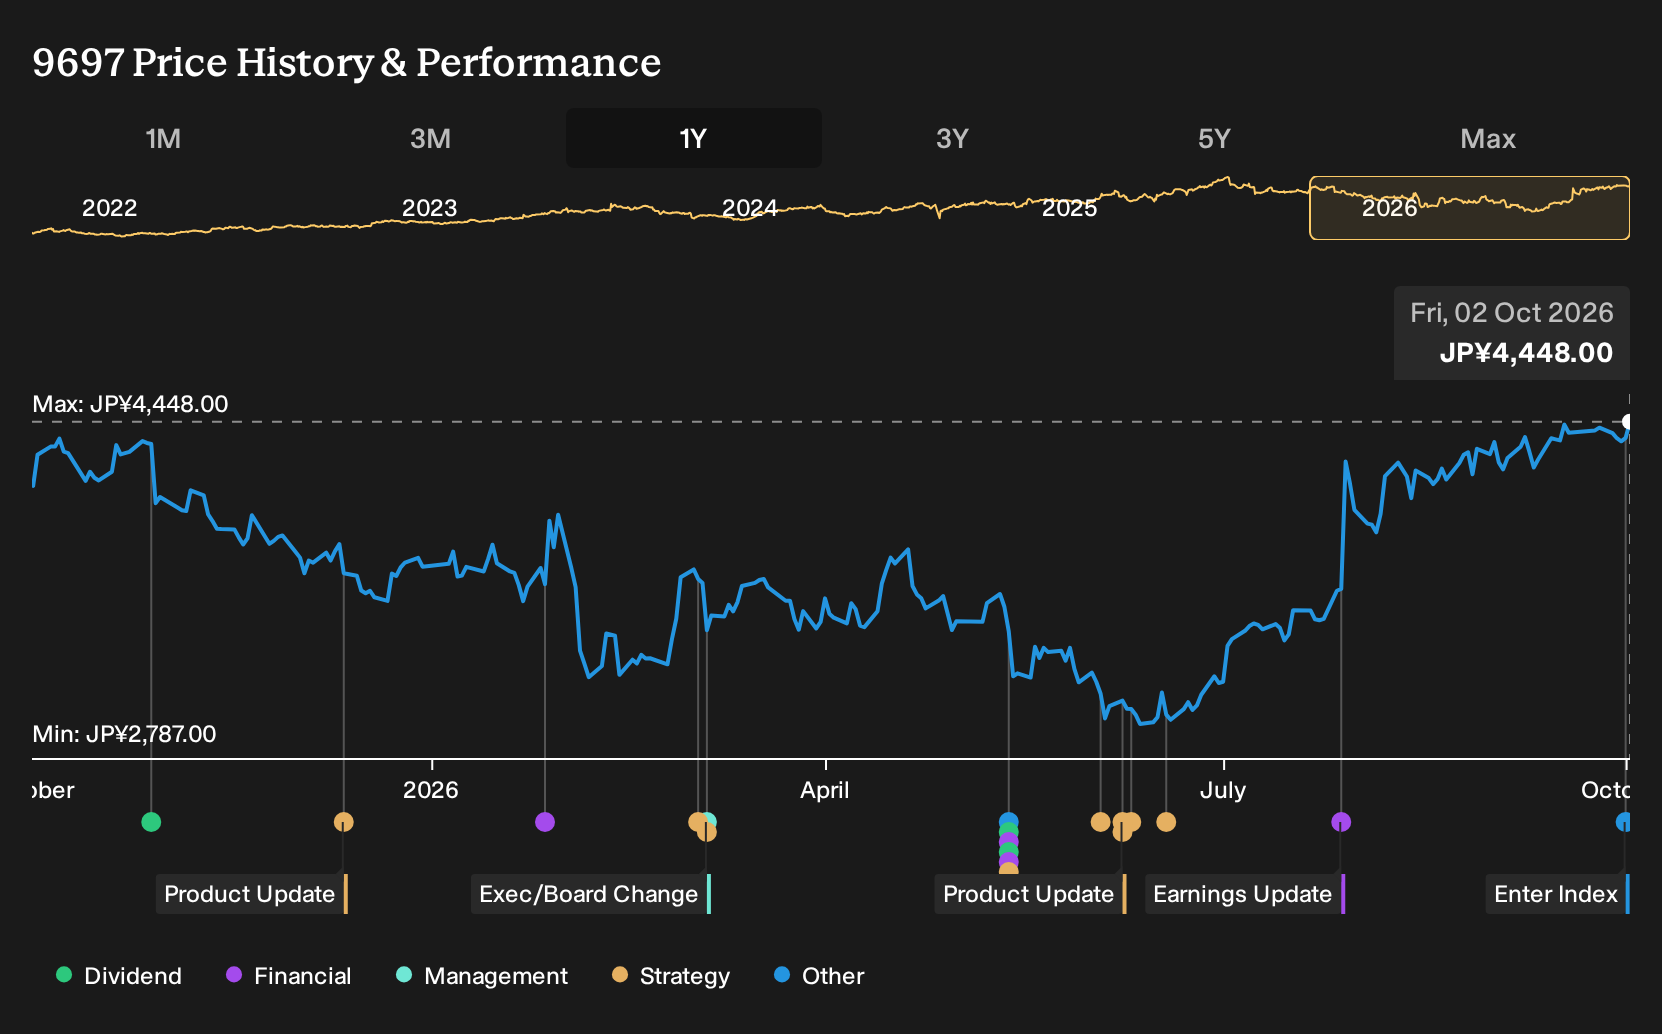
- Capcom Co., Ltd. was added to the Nikkei 225 Index in October 2026, marking its inclusion in one of Japan's key equity benchmarks.
- This index entry can reshape Capcom's investor base by drawing in passive index trackers, which may influence trading liquidity and ownership concentration.
- We will now look at how Capcom's investment narrative could be affected by its fresh inclusion in the Nikkei 225 Index.
Compare how Capcom's Nikkei 225 inclusion stacks up against other potential benchmark entrants by reviewing a curated set of 75 high quality undiscovered gems.
Capcom Investment Narrative Recap
To own Capcom, you need to be comfortable with a publisher that leans heavily on a few global franchises while pushing deeper into digital distribution and international markets. The Nikkei 225 inclusion can raise the profile of that story but does not directly change whether the game pipeline, catalog performance, and digital mix keep earnings moving.
The most immediate swing factor is execution on large AAA titles, since escalating development costs mean any delay or softer reception can quickly affect results. The biggest risk is still franchise fatigue and cost inflation. Index membership does not materially reduce those pressures, even if it may broaden the shareholder base.
There are no fresh operational announcements tied directly to the Nikkei 225 move, so the most relevant information is still the existing earnings profile. Capcom reports revenue of ¥220.3b and net income of ¥66.5b, with net profit margins around 30.2%. That level of profitability gives the business some cushion if single projects underperform.
Analysts expect revenue to grow about 7.3% a year and earnings about 8.4%, with return on equity forecast near 20.8%. The stock trades on a P/E of roughly 28x, which sits above both peer and industry averages. For you, the key question is whether that current pricing fairly reflects execution risk on future titles and ongoing investment needs.
Capcom Forecasts Behind the Nikkei 225 Story
Capcom's narrative projects ¥271.7b revenue and ¥83.5b earnings by 2029. This implies 7.2% yearly revenue growth and an earnings increase of about ¥17.0b from ¥66.5b today.
Uncover why Capcom's fair value indicates results that are roughly in line with its current price.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly ¥3,360 to ¥6,317, so some retail investors see Capcom as much cheaper than others do. You have rising development costs, franchise concentration, and index inclusion all in the mix. Expect wide opinion gaps and explore several competing viewpoints before forming your own stance.
Explore 3 other Capcom fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capcom research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Capcom. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capcom's overall financial health at a glance.
Looking for more ideas beyond Capcom?
If Capcom's Nikkei 225 entry has sharpened your interest in where to hunt for the next opportunity, it can help to scan other companies that line up with your preferred mix of quality, risk and income. The Simply Wall St Screener lets you filter by fundamentals in minutes so you can build a watchlist that genuinely matches how you like to invest.
- If you want potential mispricings with solid business quality on your radar, start with a curated set of 17 high quality undervalued stocks that already combine earnings strength with balance sheet support.
- For investors who care most about resilience and capital preservation, focus on companies in the 23 resilient stocks with low risk scores that score well on financial health and volatility checks.
- If steady cash returns are your priority, scan the 24 dividend fortresses to find income ideas offering yields above 5% that may fit a more payout focused approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com