


Why the CyberFlood CF50 launch matters for Viavi Solutions
Viavi Solutions (VIAV) triggered fresh interest after unveiling the CyberFlood CF50, a compact platform aimed at testing application performance, security controls, AI inference and large language models at up to 100G.
Recent trading suggests investors are reassessing Viavi Solutions with fresh optimism, with a 30-day share price return of 35.11% and a year-to-date share price gain of 159.50%, while the 1-year total shareholder return of 270.28% points to powerful momentum already in play.
Scan how Viavi Solutions fits into the broader AI and security testing theme by weighing it against a curated group of 90 AI infrastructure stocks.
Bulls point to Viavi Solutions rapid CF50 rollout and strong recent returns, while bears focus on the current loss and rich expectations already in the price. Which case does the valuation math lean toward next?
Most Popular Narrative: 23% Undervalued
Viavi Solutions last closed at $47.10 while the most followed narrative pegs fair value at about $61.43, so the story investors are reacting to leans on a sizeable valuation gap supported by aggressive earnings and margin expectations.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T, enabling multi-year upgrade cycles and expanding its total addressable market. This is expected to drive structural revenue growth through 2026 and beyond. The rapid proliferation of fiber broadband deployments for both hyperscale data interconnect and traditional carrier networks, coupled with aggressive announced spending by North American fiber operators, points to a significant near-term acceleration in fiber-related test equipment orders, supporting higher future revenues.
See why 14 investors see Viavi Solutions as 23% undervalued.
Result: Fair Value of $61.43 (UNDERVALUED)
Still, Viavi Solutions depends on cyclic telecom and cable spending, and any prolonged weakness there or integration issues from recent deals could quickly undermine this upbeat narrative.
Find out about the key risks to this Viavi Solutions narrative.
Another View: What Viavi Solutions Looks Like On Sales
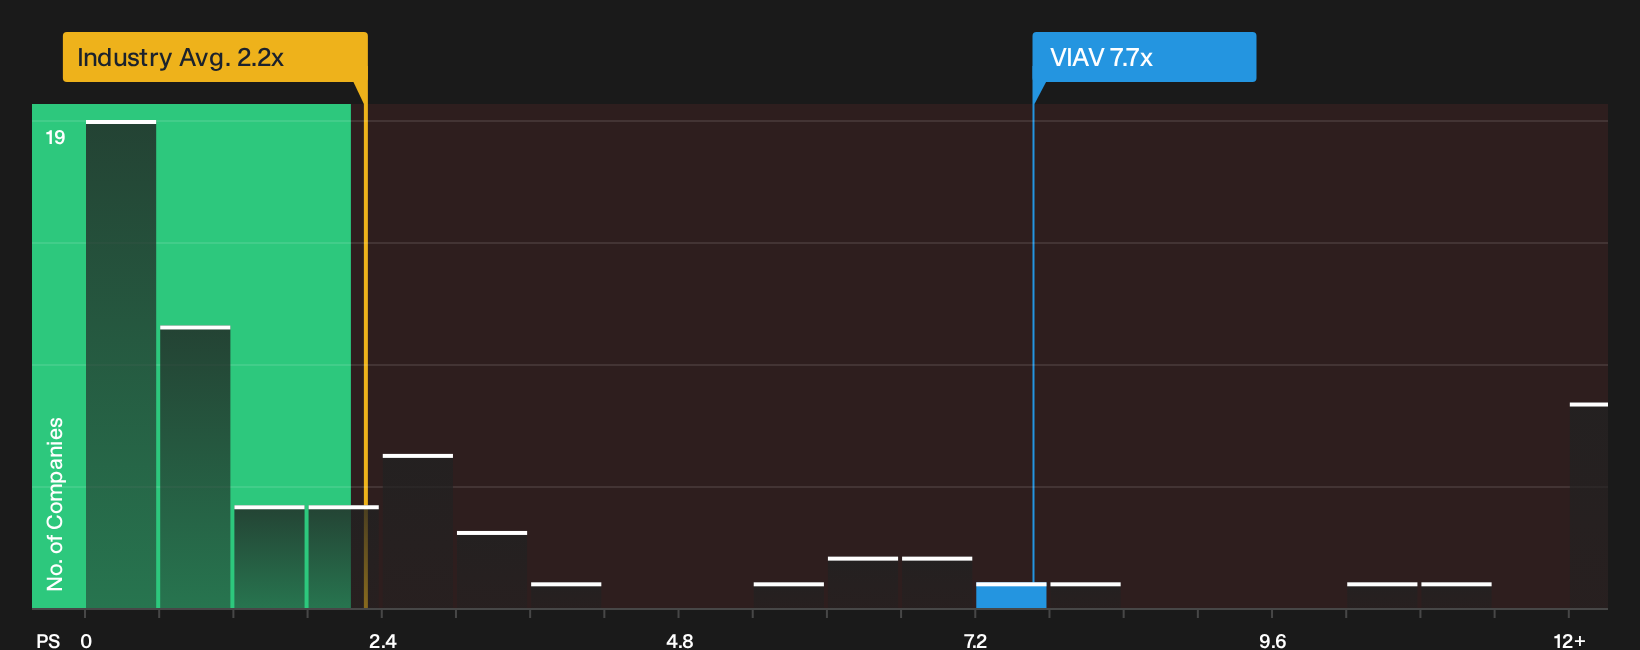
There is a sharp contrast between the popular “23% undervalued” story and what the current price is implying. Viavi Solutions trades on a P/S ratio of 7.7x, which is much richer than the US Communications industry at 2.2x and still above the peer average of 8.9x.
The estimated fair ratio sits at 8x, only slightly higher than where the shares are now. That suggests less room for multiple expansion and more dependence on future revenue and margin delivery. If sentiment cools, how comfortable are you owning a stock where most of the uplift relies on the story playing out perfectly?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed on whether the current optimism around Viavi Solutions is justified or overstretched. Move quickly, review both the upside and the red flags, and weigh the 2 key rewards and 2 important warning signs.
Looking for more Viavi Solutions style ideas?
If Viavi Solutions caught your eye, do not stop here. Broader opportunities often sit just outside the headline story, and ignoring them can cost you real upside.
- Target potential mispricings by scanning a 31 high quality undervalued stocks that filters for quality businesses trading below their implied worth.
- Strengthen your income game by reviewing a 7 dividend fortresses that focuses on higher yielding payers with staying power.
- Prioritise resilience by reviewing a 31 resilient stocks with low risk scores designed to highlight companies with more defensive profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com