


- Endeavour Mining reported record free cash flow of US$1.156b in FY2025 and US$761m in H1 2026, keeping a net cash balance sheet and supporting a US$301m shareholder payout that included an interim dividend of about US$0.95 per share.
- The group now holds roughly C$1.78b of cash while funding five operating mines and advancing projects such as Assafou and the Sabodala-Massawa expansion, which sharpens the trade off between growth investment, geopolitical risk in West Africa and ongoing cash returns to investors.
- This article examines how Endeavour Mining's investment narrative is influenced by record free cash flow supporting sizable dividends and growth projects.
Scan beyond Endeavour Mining and line up other cash rich producers by running the curated 36 elite gold producer stocks, which share a focus on balance sheets and shareholder returns.
Endeavour Mining Investment Narrative Recap
To own Endeavour Mining, you need to believe the business can keep turning strong cash generation into both new mines and regular cash returns. The recent record free cash flow and net cash position support that view in the near term, since they give management more room to fund growth and still pay shareholders.
The short term catalyst is progress on Assafou and the Sabodala-Massawa expansion, because these projects shape how production and unit costs might look over the next few years. The biggest risk remains West African country exposure, where tax, security or permitting changes could quickly eat into cash flow and delay projects.
The most relevant recent development is Endeavour Mining flagging a final investment decision on Assafou by the end of 2026. That timeline now sits alongside a much larger cash pile and record free cash flow, which makes funding options more flexible and reduces the need to lean on higher risk external borrowing.
For you as a shareholder, the question is whether Assafou and Sabodala-Massawa can offset reserve depth and cost pressure at mature assets such as Houndé, Ity and Mana, without stretching the balance sheet. Execution on these builds, alongside managing VAT recoveries and country risk, will likely drive how confident the market feels about the current dividend level.
Endeavour Mining's current narrative is built around analysts expecting revenue to compound at 9.4% per year and earnings to reach $1.9b by 2029, compared with earnings today of $839.9m. This implies an increase of about $1.1b, supported by forecasts that put 2029 revenue at $6.2b.
Uncover why Endeavour Mining's fair value indicates an 18% potential upside to its current price that could narrow quickly.
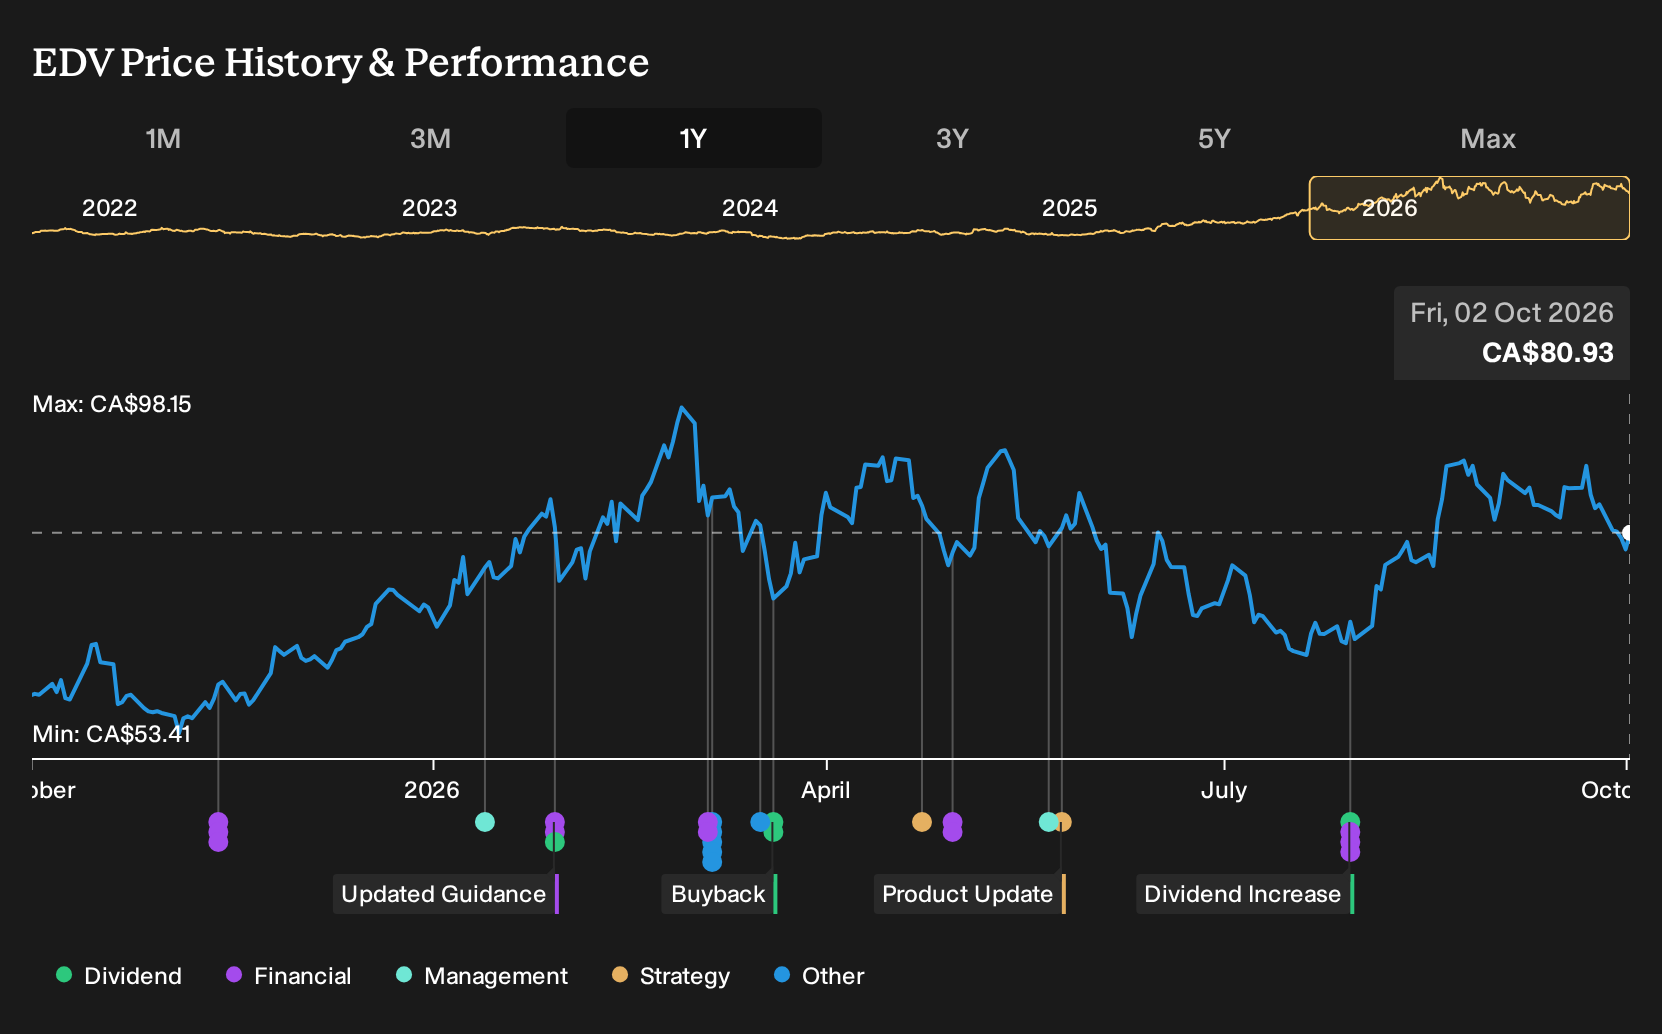
Exploring Other Perspectives
One alternate view focuses on tax and royalty risk rather than project growth. The most bearish analysts saw governments taking a larger slice, which could leave 2029 revenue nearer US$5.4b and earnings around US$1.4b, not US$1.9b. That is a very different story. Use these gaps as a prompt to explore several competing forecasts.
Explore 3 other Endeavour Mining fair value estimates, including one that suggests it could be worth just CA$95.74.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Endeavour Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Endeavour Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Endeavour Mining's overall financial health at a glance.
Looking For More Ideas Beyond Endeavour Mining?
If you want to put Endeavour Mining in context, it helps to line it up against other opportunities that fit different portfolio goals. Use the Simply Wall St Screener to source a wider watchlist and compare quality, income potential and risk across a broader set of companies.
- For investors who want income to feel more predictable, scan for higher yielding payers that our filters flag as sturdier, balance focused options using the 1 dividend fortresses.
- If capital protection matters just as much as upside, narrow your search to companies with stronger financial cushions by running the 8 resilient stocks with low risk scores.
- When hunting for fresher opportunities that receive less attention, build a watchlist around financially sound outliers by starting with the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com