


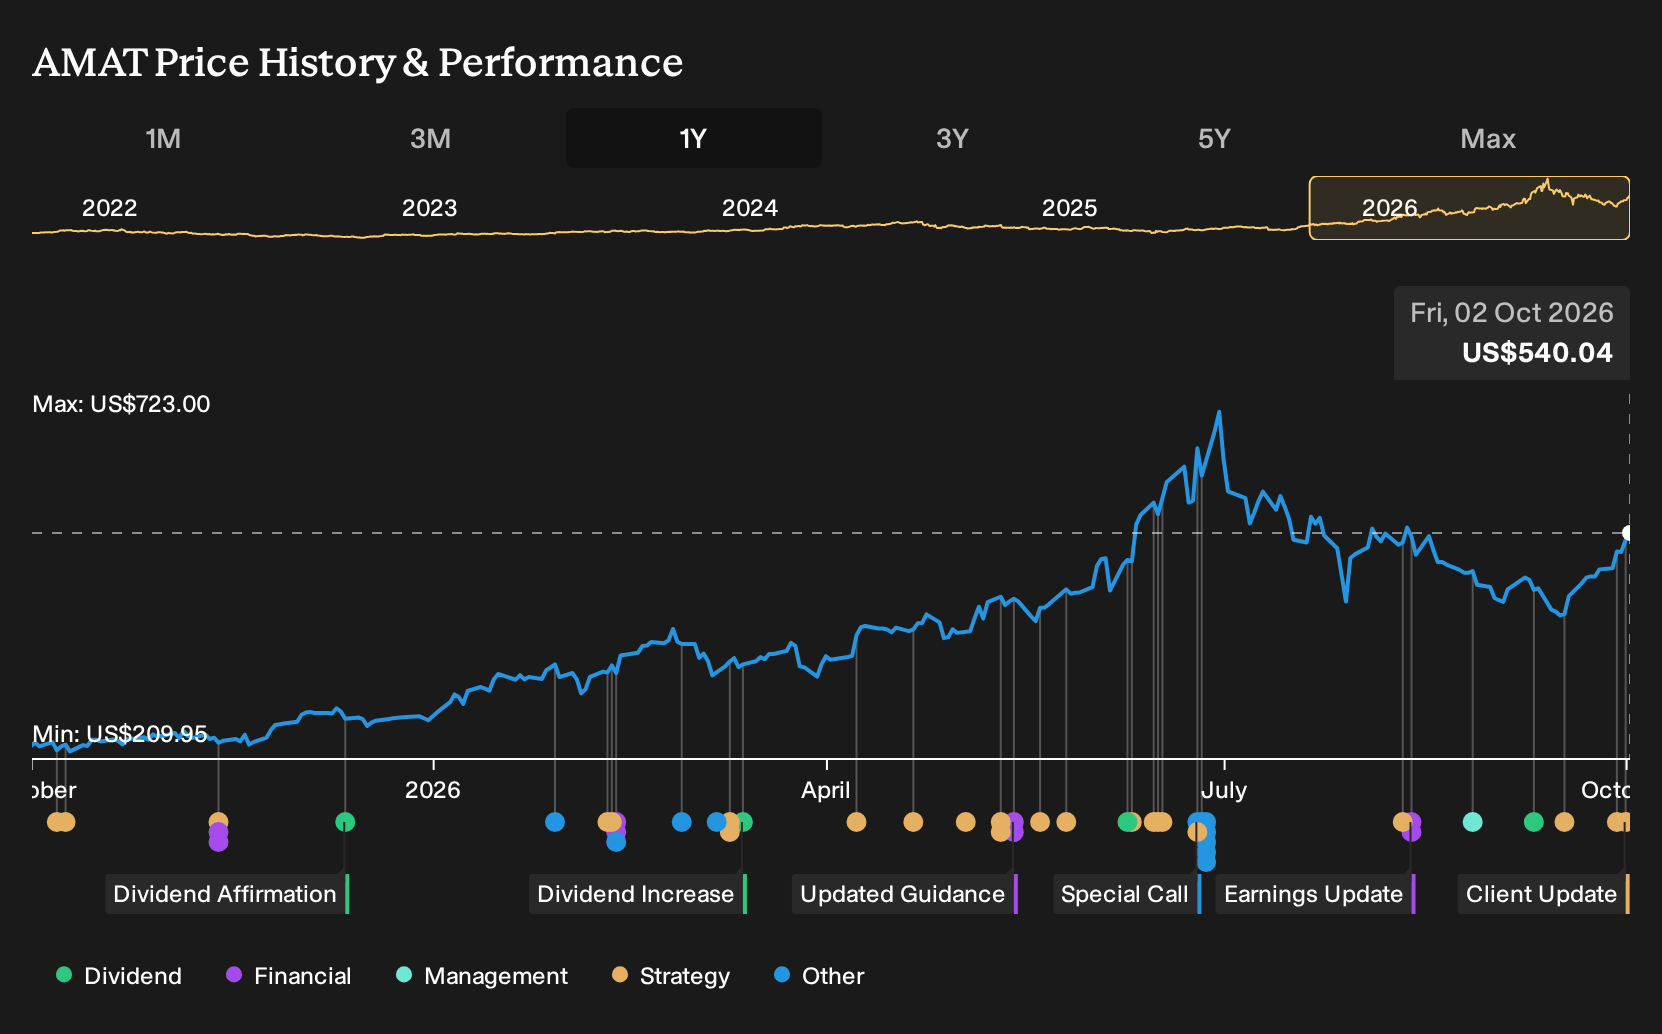
- Applied Materials reported expanded collaborations with BE Semiconductor Industries and KIOXIA, bringing both partners into its EPIC Center to co-develop advanced packaging and memory technologies for AI-focused chips.
- This deeper, in-house co-engineering model tightens Applied Materials’ role inside customers’ R&D roadmaps. It can influence tool selection, process standardization and long-term demand visibility across advanced packaging flows.
- We will now assess how Applied Materials' expanded EPIC Center co-development on advanced packaging could reshape the company's wider investment narrative.
Applied Materials Investment Narrative Recap
To own Applied Materials, you need to believe AI driven chip complexity keeps pulling more value into materials engineering and advanced packaging, where the company is already deeply embedded with leading customers. The expanded EPIC Center partnerships with BE Semiconductor and KIOXIA strengthen that story but do not change the near term focus on execution against existing tool backlogs and customer capex timing.
The biggest short term catalyst is still delivery against upcoming earnings and order visibility, especially with analysts expecting strong profit growth and a P/E that already prices in robust progress. Key risks remain heavy China exposure, concentrated customers and rising R&D commitments that could pressure margins if advanced nodes or packaging ramps slow or get delayed.
The KIOXIA EPIC Center announcement feels most relevant here because it ties Applied Materials directly into next generation AI memory architectures, where density and stacking are critical bottlenecks for data hungry workloads. Working side by side on multi chip stacking, advanced packaging and materials engineering keeps Applied inside the problem solving loop as customers define their next memory roadmaps.
For you as an investor, the KIOXIA partnership reinforces the idea that EPIC is not just a cost center but a potential execution engine for future tools that address AI memory demand. The potential upside is better R&D productivity and earlier production wins. The operational risk is straightforward: higher spending without timely high volume adoption would weigh on returns and could challenge today’s valuation.
Applied Materials' current analyst script points to US$53.0b in revenue and US$17.0b in earnings by 2029, built on an assumed 22.2% yearly revenue growth rate. That path implies earnings today of US$8.5b would need to roughly double, with an earnings increase of about 2x by 2029.
Uncover how Applied Materials' fair value indicates a 16% potential upside to its current price before the discount gap closes.
Exploring Other Perspectives
One bearish twist on Applied Materials centers on the risk that all this EPIC Center packaging excitement simply fails to translate into the earnings curve you are implicitly paying for. The most cautious analysts were penciling in about US$54.0b of revenue and US$18.6b of earnings by 2029 before this news. That is actually higher than the consensus US$53.0b and US$17.0b path, yet they argued the stock already priced in too much success and used a lower 25.5x P/E to justify a US$432.54 fair value. Your takeaway is straightforward: smart people can look at the same AI packaging story and reach very different conclusions, so it is worth exploring both the upbeat and the skeptical forecasts and asking how this new KIOXIA and Besi news might shift either camp.
Explore 9 other Applied Materials fair value estimates, including one that suggests as much as 48% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Applied Materials research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Applied Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Materials' overall financial health at a glance.
Looking For More Ideas Beyond Applied Materials?
If the Applied Materials story has you rethinking how AI infrastructure, capital intensity and balance sheet strength fit together in your portfolio, it can help to scan a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who care most about sturdy financial foundations and low leverage, start with a list of solid balance sheet and fundamentals (25 results) that can handle stress without forcing rushed decisions.
- If resilience and a smoother ride matter more to you than chasing every AI headline, filter for 31 resilient stocks with low risk scores that score well on stability metrics and business durability.
- Those hunting for under-the-radar potential can cast a wider net across 19 high quality undiscovered gems that pair solid fundamentals with relatively little market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com