


- Guidewire Software announced a multi-year deal for Guidewire Cloud and PolicyCenter with a top 10 US insurer, moving this carrier into its top 10 customers by fully ramped annual recurring revenue and leaving previously issued quarterly and full-year guidance unchanged.
- The new agreement highlights how large personal lines insurers are committing core policy administration to Guidewire Software's cloud platform, reinforcing the role of long-term recurring contracts in the business model as AI tools like ProNavigator embed more deeply into underwriting and claims workflows.
- We will now look at how Guidewire Software's investment narrative could shift as recurring cloud revenue deepens with a top-tier insurer.
Guidewire Software Investment Narrative Recap
To own Guidewire Software you need to believe that more P&C insurers will keep moving core systems and workflows onto its cloud and AI products, and that the firm can turn that mix into steadier, higher margin recurring revenue. The latest top 10 US carrier deal fits that story, but management keeping guidance unchanged signals limited near term financial impact.
The key short term catalyst is evidence that large cloud wins go live on time and expand into adjacent modules and data products. The biggest risk is execution. Complex migrations, climate related claims volatility at customers, and foreign exchange swings could all disrupt ARR conversion even with high quality earnings today.
The multi year Guidewire Cloud and PolicyCenter agreement with a top 10 US insurer looks most relevant. It concentrates more of Guidewire Software's future ARR in a single, sophisticated buyer. That buyer can be a powerful reference account for other carriers watching cloud migrations and AI infused workflows play out in production.
The Lititz Mutual rollout of Guidewire ProNavigator shows how those workflows extend into day to day underwriting and claims decisions. That kind of AI adoption can support the catalyst around higher value subscriptions, yet it also raises delivery risk. These customers expect reliable performance, tight integrations, and consistent answers inside critical insurance processes.
Guidewire Software's current narrative points to forecast revenue of US$2.2b and consensus earnings of US$294.1m by 2029, based on analyst assumptions of 15.3% yearly revenue growth and an earnings increase of about US$134.3m from US$159.8m today.
Uncover why Guidewire Software's fair value indicates a 39% potential upside to its current price, which could close faster than many investors expect.
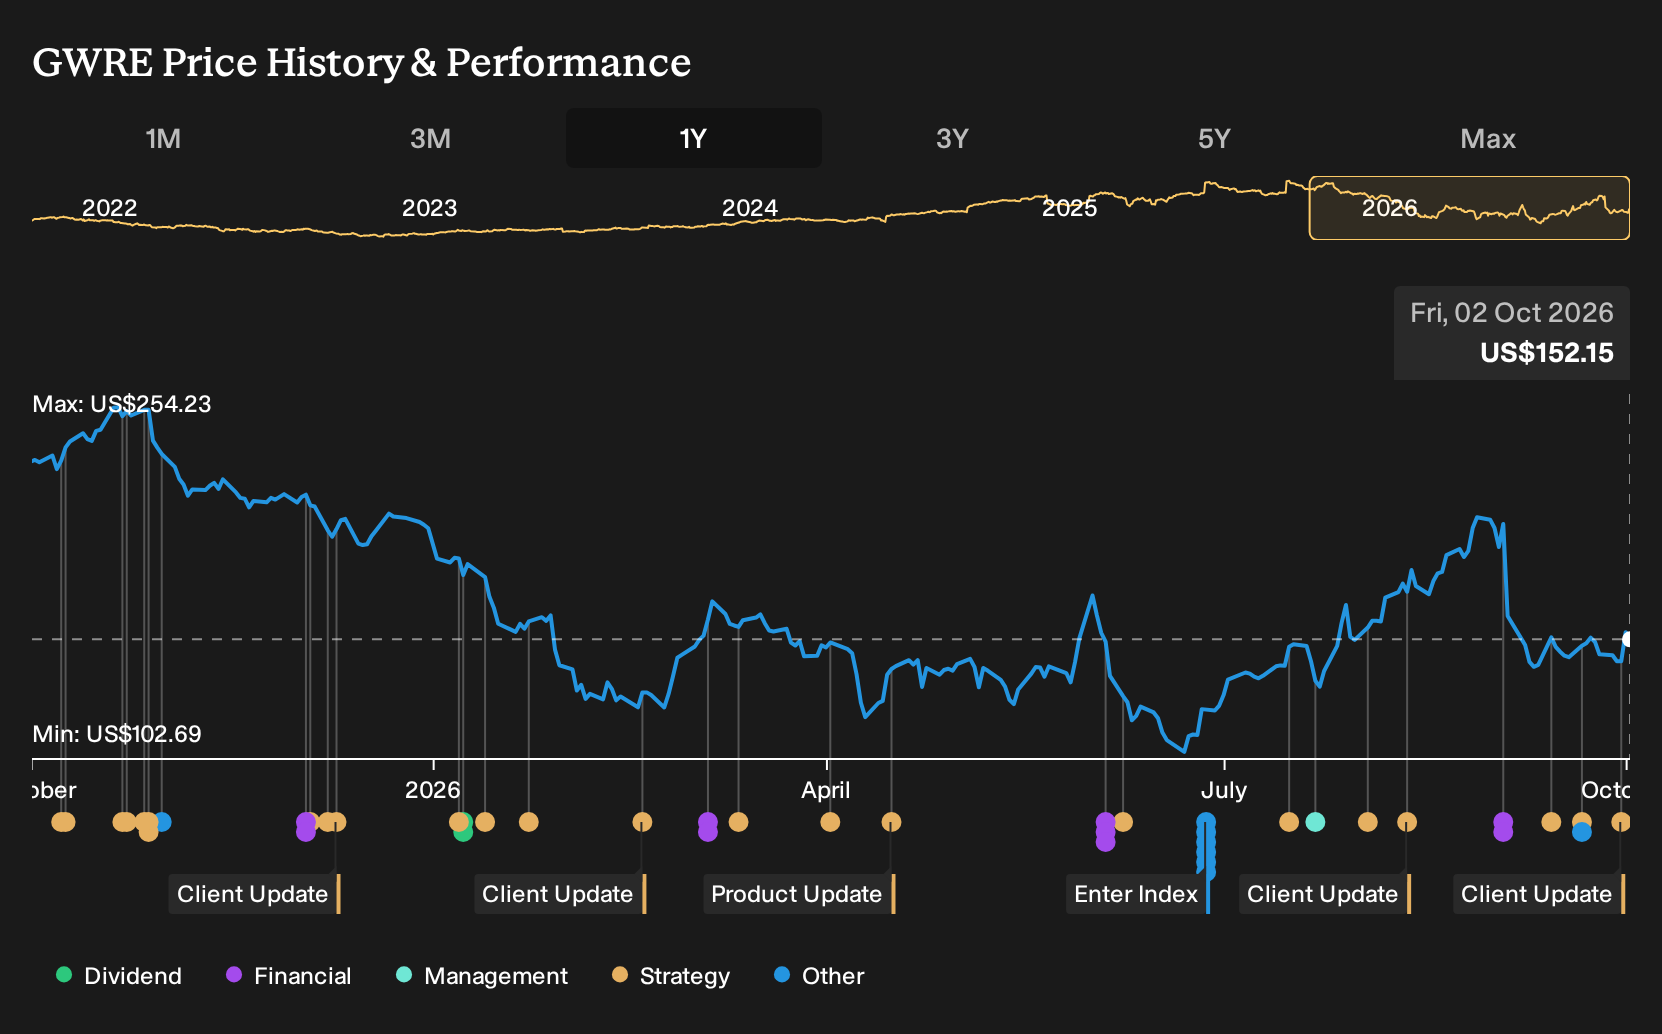
Exploring Other Perspectives
One alternate Guidewire Software story you might explore focuses less on cloud wins and more on customer concentration risk. The most optimistic analysts were already penciling in revenue of about US$2.3b and earnings of US$310.1m by 2029 before this deal. That camp sees big contracts as upside, but also as a source of fragility. It is a useful reminder that smart people can look at the same facts and reach very different conclusions, so it pays to study several narratives and then decide which fits your own view as new information like this contract filters into forecasts.
Explore 3 other Guidewire Software fair value estimates, including one that suggests as much as 70% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Guidewire Software research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Guidewire Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guidewire Software's overall financial health at a glance.
Looking For More Investment Ideas Beyond Guidewire Software?
If this Guidewire Software story has you thinking about what else might fit a similar playbook, it can help to scan for other companies with resilient balance sheets, repeatable cash flows, or overlooked potential using the Simply Wall St Screener.
- For investors who care most about financial strength and durability, start with a list of solid balance sheet and fundamentals (25 results) that can handle shocks without constant refinancing risk.
- If capital preservation matters and you prefer steadier profiles, focus on 31 resilient stocks with low risk scores that screen well on volatility and fundamental risk factors.
- When you want something less crowded yet still grounded in fundamentals, hunt through 19 high quality undiscovered gems that the wider market may not be paying full attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com