


- United Airlines Holdings recently received its first Airbus A321XLR equipped with Pratt & Whitney GTF Advantage engines, which are designed for longer time on wing, higher takeoff thrust, and easier integration with existing GTF-powered aircraft.
- This step in fleet modernization could support United Airlines Holdings' push toward a larger premium footprint by aligning aircraft capability with longer range, higher yielding routes and more consistent operational performance.
- This article examines how United Airlines Holdings' premium focused transformation is influenced by the new A321XLR with GTF Advantage engines.
United Airlines Holdings Investment Narrative Recap
To own United Airlines Holdings, you need to believe its premium focused overhaul and United Next fleet plan can outweigh high leverage and industry volatility. The near term swing factor is execution on capacity and pricing, especially on long haul and premium heavy routes. The new A321XLR delivery is directionally helpful but not a standalone catalyst.
The biggest risk remains debt funded expansion in a sector exposed to demand shocks, labor costs, and regulatory pressure on emissions. Any stumble on reliability at congested hubs, or weaker premium demand, could matter more to the story than incremental engine efficiency gains from this single aircraft.
The delivery of United Airlines Holdings' first A321XLR with GTF Advantage engines connects directly to the premium and long haul capacity narrative. Higher thrust and longer time on wing, if achieved in service, could support more efficient deployment on transatlantic or deep leisure routes that fit the carrier's premium tilt.
This matters most where catalysts and risks intersect. A more efficient narrowbody capable of long range can support operating leverage and network flexibility, yet it sits against a balance sheet already carrying significant debt and exposure to fuel and regulatory costs. Execution on reliability, utilization, and maintenance planning around these engines will likely determine whether this news becomes financially meaningful or stays operationally incremental.
United Airlines Holdings is currently modeled off analyst assumptions that revenues reach US$74.9b and earnings reach US$4.2b by 2029. This implies 6.0% yearly top line growth and an earnings increase of about US$0.7b from the US$3.5b reported today.
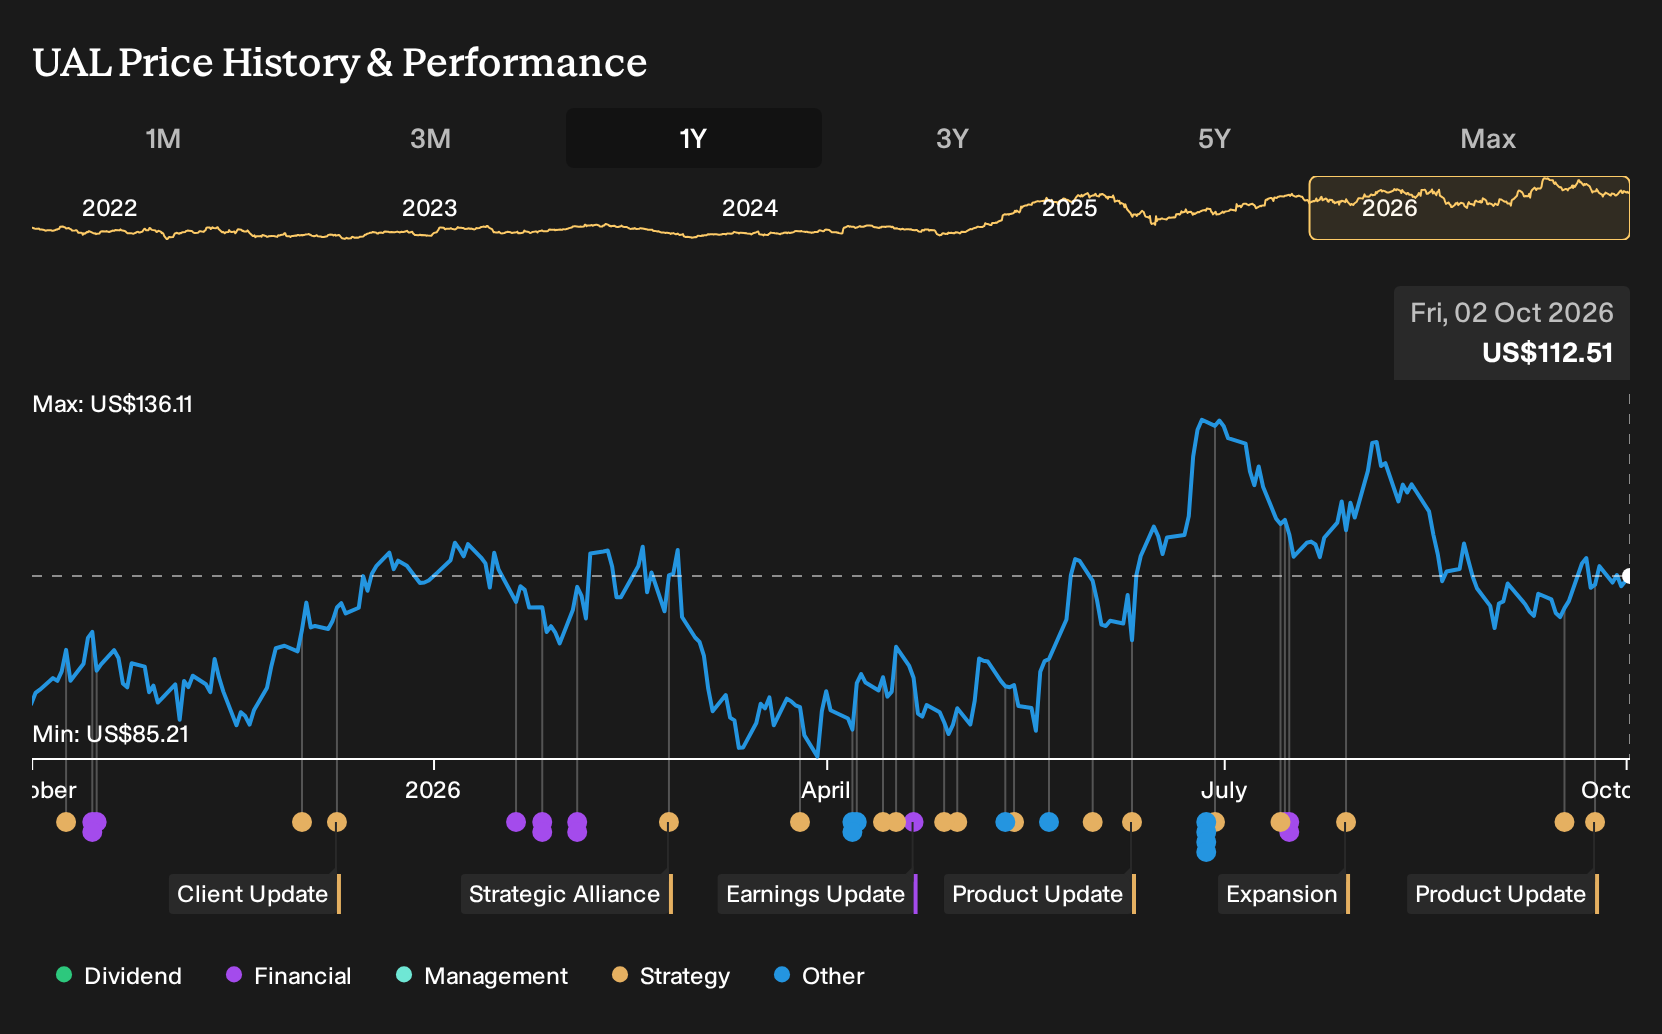
Uncover why United Airlines Holdings' fair value indicates a 39% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest United Airlines Holdings analysts focus on regulatory and cost risk instead of premium upside. They were penciling in about US$69.0b of revenue and earnings of roughly US$4.7b by 2029 before this A321XLR engine news. That more cautious script could shift, so compare several narratives before deciding how you view United.
Explore 3 other United Airlines Holdings fair value estimates, including one that suggests it could be worth just $115.10.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Airlines Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Airlines Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Airlines Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Airlines Holdings?
If you want to stress test your view on United Airlines Holdings against what else is on the market, broadening your watchlist with a few focused stock groups can help you see where risk and quality really sit in your portfolio.
- If capital preservation is high on your list, start with companies that screen for lower overall risk profiles through the 31 resilient stocks with low risk scores.
- If you want balance sheet strength to anchor your returns, look at businesses that pass the list of solid balance sheet and fundamentals (25 results).
- If you are searching for underfollowed opportunities with solid fundamentals, scan the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com