


Australian treasurer Jim Chalmers has warned that global turmoil is squeezing budgets at the same time inflation pressures stay stubborn, which puts a premium on hard cash rather than hopeful stories. When policymakers talk cuts, investors often seek out businesses that already throw off solid cash and still trade below what careful modelling suggests they are worth. This article highlights three such Australian stocks that screen as undervalued on future cash flows.
The three stocks below are a sample, while the full screen surfaced 6 more Australian businesses with similarly cash rich stories that are not covered here. To go straight to the source, use the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the highest conviction ideas for your own watchlist.
Qualitas (ASX:QAL)
Overview: Qualitas is an Australian real estate investment manager that focuses on private credit loans generating interest income from commercial and residential projects.
Operations: The group earns about A$15 million mainly from Funds Management, with smaller Direct Lending income, all currently sourced in Australia.
Market Cap: A$657 million
Qualitas taps into the Undervalued Stocks Based On Cash Flows theme by turning secured real estate loans into relatively steady interest streams that can be modelled. This can be particularly relevant when cash generation and loan quality matter more than blue-sky growth stories.
"Banks have continued to move away from commercial property lending since 2009, and private credit’s share of Australian real estate debt has grown from 15% in 2019 to 26% today, with forecasts of 35% by 2030."
The real question for investors is how any quietly building pressure in this lending market will shape those future cash flows.
That pressure point is exactly where the story gets interesting, and the full narrative for Qualitas explains how Qualitas could turn shifting real estate debt into accelerating cash generation potential.
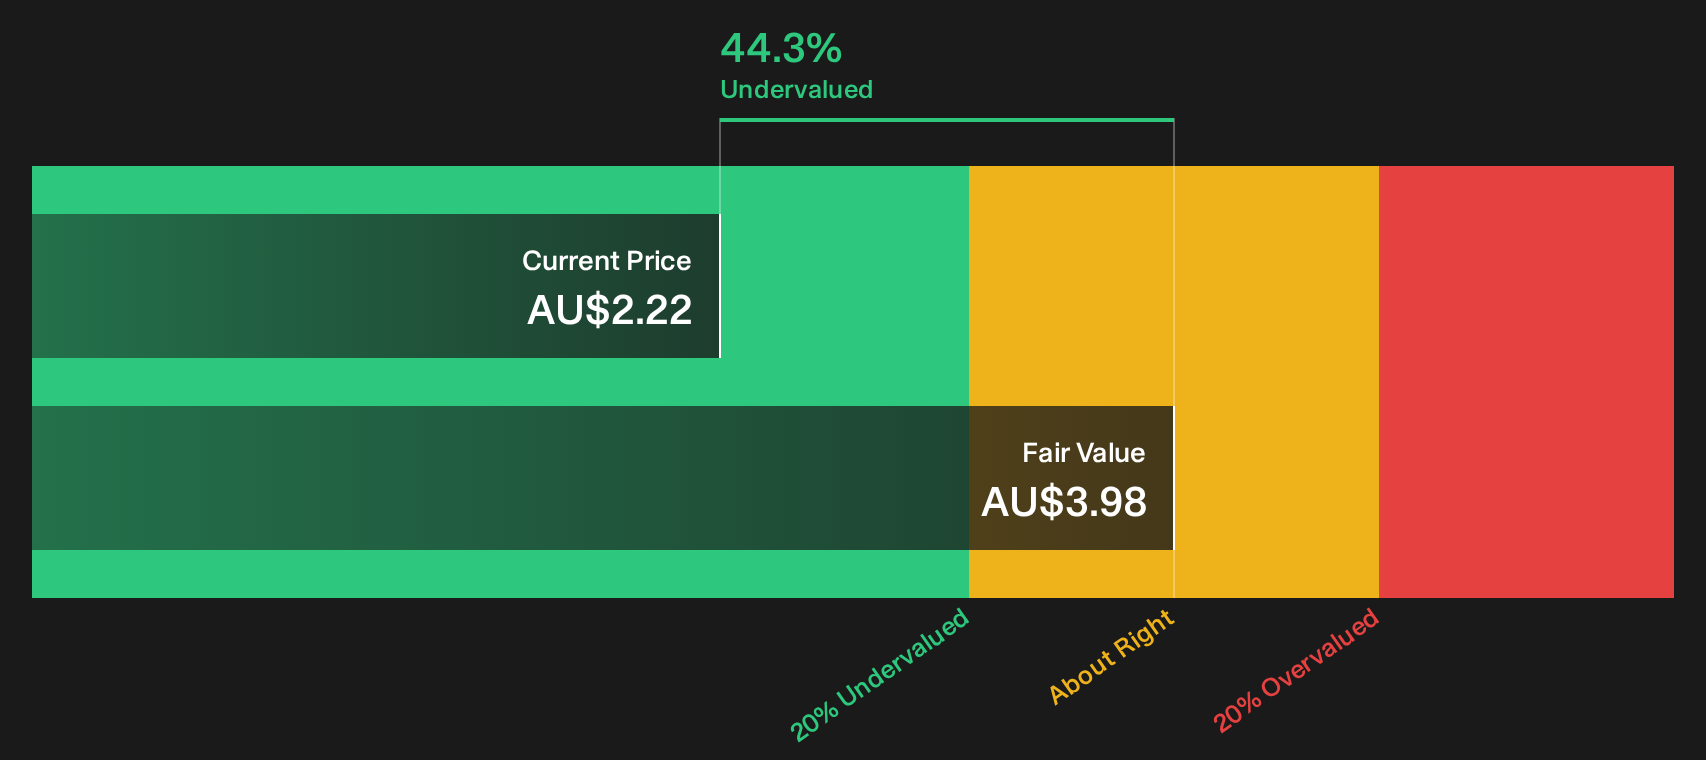
MotorCycle Holdings (ASX:MTO)
Overview: MotorCycle Holdings runs a network of motorcycle dealerships and accessory outlets, selling bikes plus higher margin servicing, parts and add-ons.
Operations: The group generates about A$560 million from Motorcycle Retailing and A$272 million from Motorcycle and Accessories Wholesaling, almost entirely in Australia.
Market Cap: A$187 million
MotorCycle Holdings matters for a cash flow focused investor because its Motorcycle Retailing arm converts one off bike sales into repeat servicing and accessories income that can support a more model friendly stream of cash over time.
"Market share in new vehicles is now close to 20% with record half year unit sales in both new and used bikes. This positions the group to capture a larger share of category spend as demand channels through its network, supporting revenue and gross profit."
The real swing factor for MotorCycle Holdings now is whether one unseen pressure on operating efficiency helps margins or quietly erodes them.
If that pressure is the real story, the full narrative for MotorCycle Holdings examines whether MotorCycle Holdings’ scale is quietly masking risk or positioning the company for stronger cash generation.

NobleOak Life (ASX:NOL)
Overview: NobleOak Life is an Australian life insurer providing recurring premium life, income protection, TPD, trauma and related cover that generates long-duration, contract-backed cash inflows.
Operations: NobleOak Life records about A$399 million from Strategic Partnerships, A$106 million from Direct and A$15 million from Genus, all in Australia.
Market Cap: A$119 million
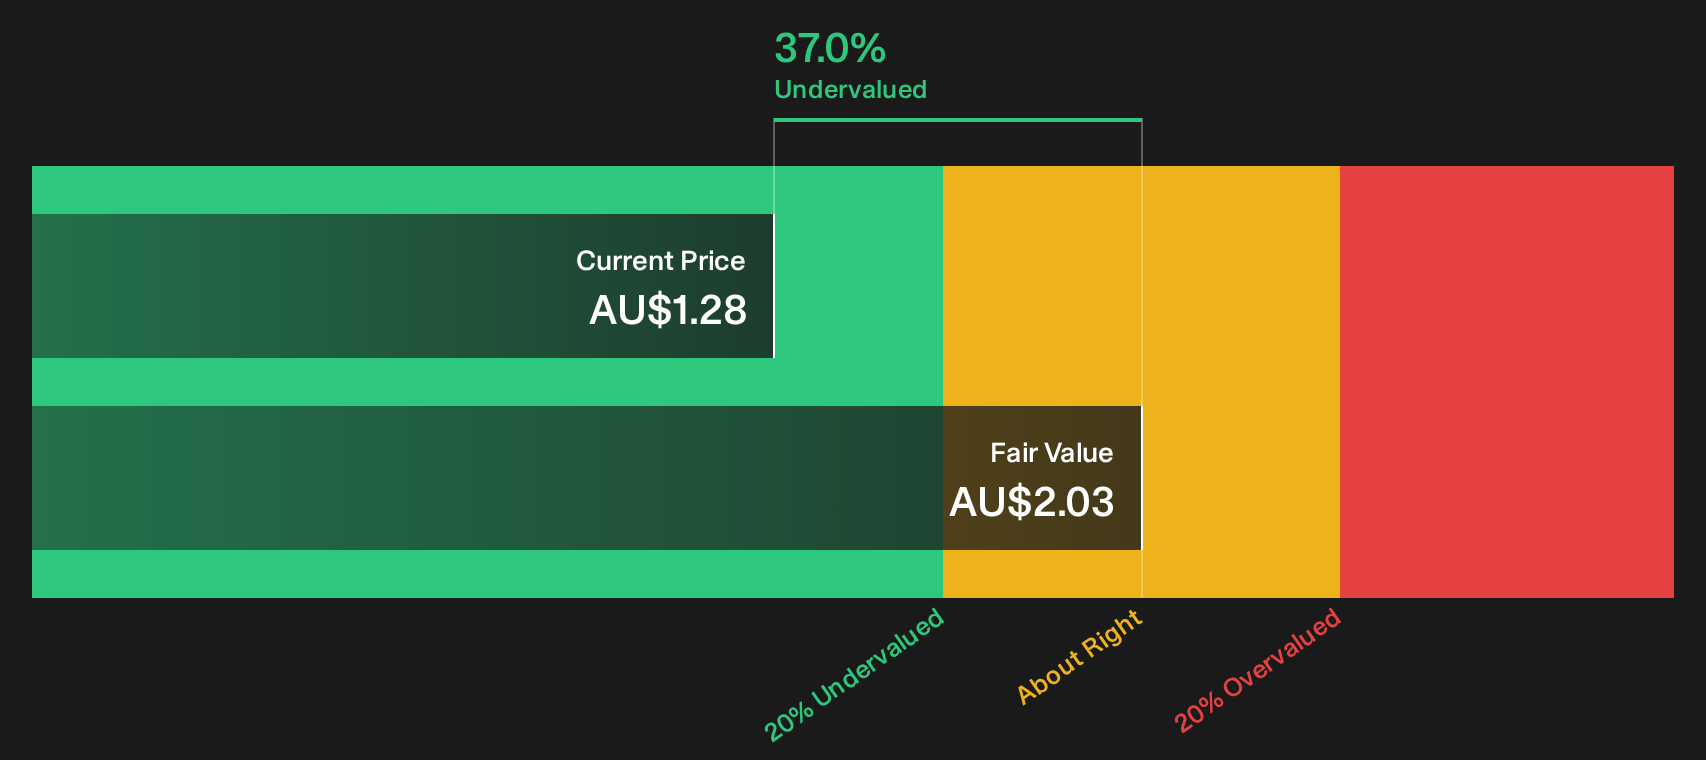
NobleOak Life links cleanly to the Undervalued Stocks Based On Cash Flows theme because its life and protection policies create recurring, contract-backed premium streams that feed into long-horizon cash flow models. The stock trades on an 8.4x P/E and around 37% below estimated fair value while earnings and margins improve, leaving one unresolved funding risk that could still reshape how durable those projected inflows really are.
That unresolved funding question is exactly where the opportunity could sit, so check the NobleOak Life financial health report to see how NobleOak Life’s balance sheet and cash engine line up.
Curious About Your Next Alternatives?
Fresh ideas move first. Breakout themes gain momentum while others get caught chasing what has already flown. Scan these under the radar picks before the crowd and act now.
- Target income streams by scanning a curated group of high yield payers through the 3 dividend fortresses while those payouts still look firmly supported.
- Look for resilient operators by zeroing in on a list of solid balance sheet and fundamentals (12 results) before rising rates or funding costs start sorting the durable from the fragile.
- Explore infrastructure opportunities by focusing on 40 power grid technology and infrastructure stocks while electrification spending remains under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com