


- Veidekke ASA reported that it won a design and build contract worth about NOK 190 million to deliver phase 4 of the Bryggebyen project in Arendal, adding 51 sea view apartments, parking and shared outdoor facilities to the long term urban development.
- The award introduces Veidekke to the Bryggebyen programme for the first time, expanding its residential construction workload with a multi year project scheduled to run until June 2028.
- This article will examine how Veidekke’s investment narrative is shaped by the NOK 190 million Bryggebyen phase 4 housing contract.
What Is Veidekke's Investment Narrative?
Owning Veidekke is really about believing that a construction and infrastructure group with high quality earnings, an outstanding 67.1% return on equity and a long record in Norway, Sweden and Denmark can keep turning a steady project flow into acceptable margins over time. The Bryggebyen phase 4 win slots neatly into that story. It expands the order backlog with a multi year residential project that leans on Veidekke's core building know how, without changing the basic thesis that execution discipline, pricing on complex work and careful use of capital matter more than any single contract.
In the short term, the NOK 190 million Bryggebyen contract looks additive rather than transformational. It lengthens visibility on workloads into 2028 and supports the existing narrative of moderate forecast revenue growth of 4.7% per year and earnings that analysts expect to rise, though not at very high rates. The bigger watchpoints still sit around project risk, a P/E of 17.2x that is above peer averages even if some models see a 6% discount to fair value, and a dividend yield of 5.26% that is flagged as not well covered by current earnings.
Even so, the cleaner growth story around Veidekke still runs into a single pressure point that could quietly reshape the whole appeal of the stock if ...
There's only one way to know the right time to buy, sell or hold Veidekke. Head to Simply Wall St's company report for the latest analysis of Veidekke's Fair Value.
Exploring Other Perspectives
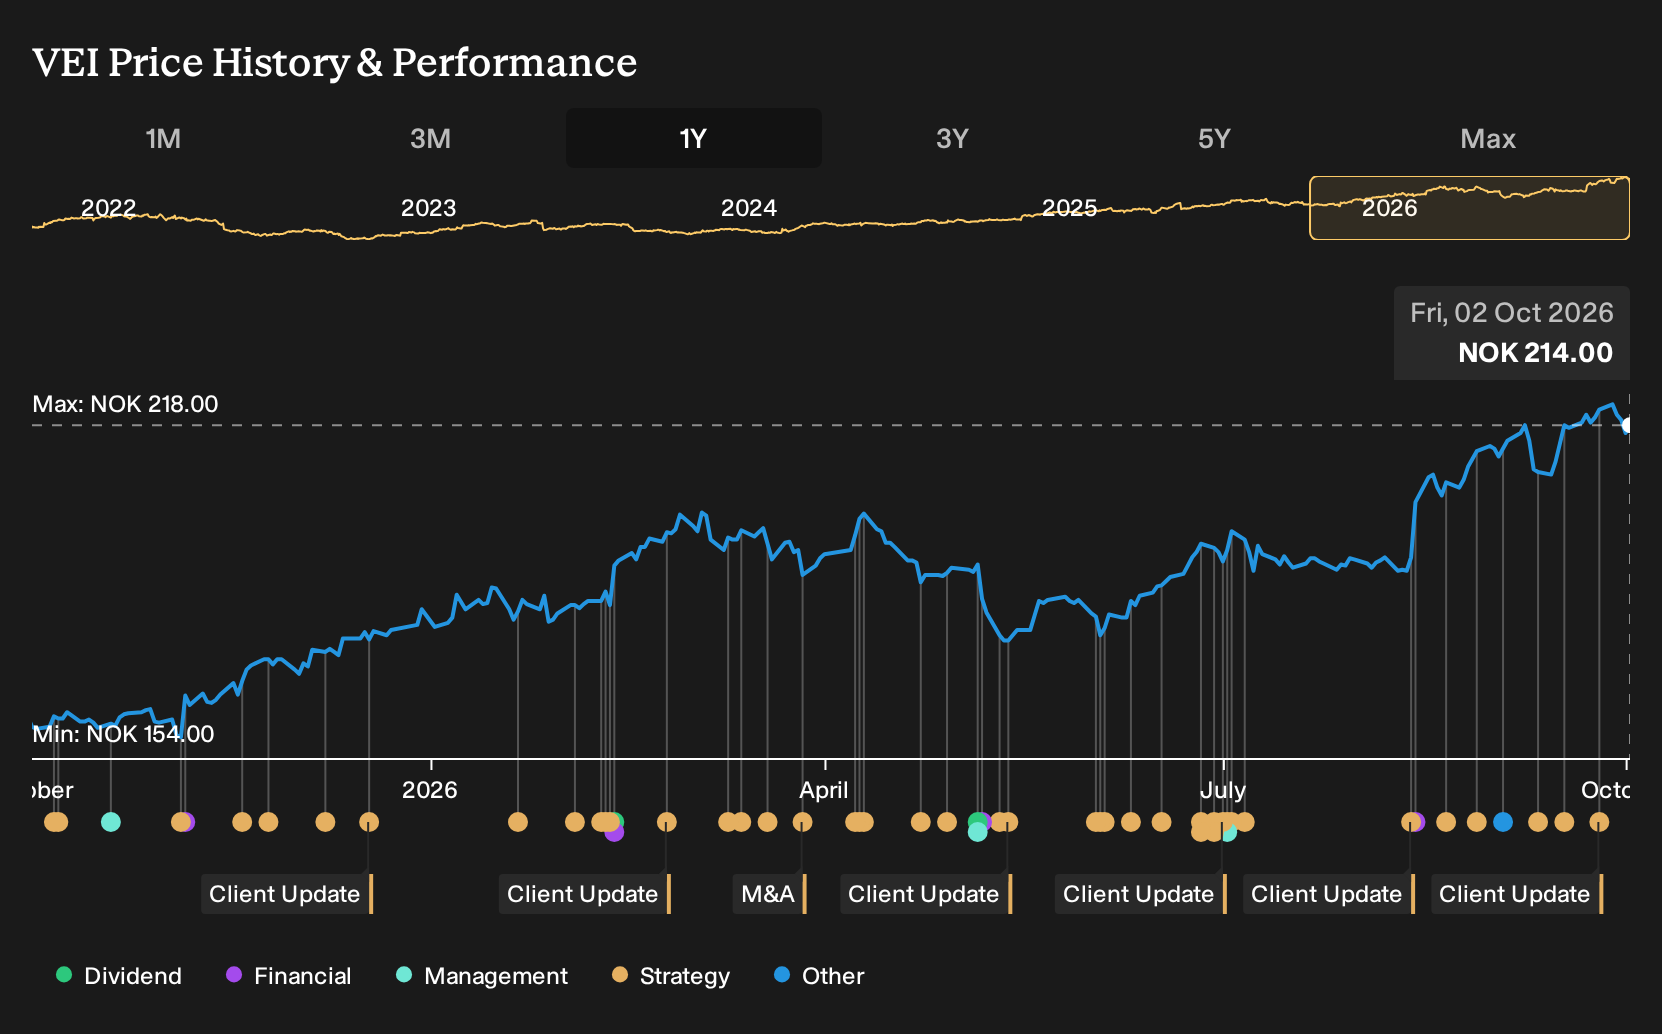
Two fair value estimates from the Simply Wall St Community cluster between NOK 210 and about NOK 228 per share, giving you a tight but still varied range of outcomes for Veidekke. Those views were formed before the Bryggebyen phase 4 award, so you are weighing them against a fresh, multi year contract that could reshape future workloads. Investor opinions can differ widely. It makes sense to explore several of these alternative viewpoints before forming your own stance.
Explore another Veidekke fair value estimate, including one that suggests up to 6% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Veidekke research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Veidekke. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veidekke's overall financial health at a glance.
Looking For More Ideas Beyond Veidekke?
If the Bryggebyen contract has you rethinking how project pipelines feed long term potential, it can help to line Veidekke up against a wider watchlist built from clear, rules based filters. The Simply Wall St Screener lets you do exactly that, so you can move from one company story to a full bench of ideas that all share the traits you care about.
- For income focused investing, assess companies that combine higher yields with the potential for resilience by reviewing the 168 dividend fortresses.
- If balance sheet strength is a priority, build a watchlist from our list of solid balance sheet and fundamentals (206 results) and focus on businesses that may be better equipped to handle tougher conditions.
- To widen the opportunity set, scan for smaller companies that still show solid fundamentals through the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com