


EnerSys (ENS) just put its Alpha XM Edge power platform in the spotlight, with Lightwave’s 2026 Diamond Technology Reviews giving the in-development system a 5.0 Diamonds Honoree Score in active network hardware.
EnerSys has attracted fresh attention on the back of these power platform updates, with the share price closing at US$196.30 after a 1-day share price return of 3.54% and a 7-day share price return of 9.73%, even though the 90-day share price return declined 7.97%.
Scan other grid and broadband power specialists that share EnerSys’s efficiency and infrastructure focus through our hand picked 40 power grid technology and infrastructure stocks
EnerSys has already delivered a strong 1-year run, yet the latest grid and broadband power headlines arrived only after a sharp recent move. Is most of the rerating already in the rear-view mirror, or is meaningful upside still ahead on valuation?
Most Popular Narrative: 3% Undervalued
On the latest numbers, EnerSys closed at $196.30, while the most widely followed fair value narrative anchors closer to $202.92. This frames today’s move against a slightly richer long term view that leans on Greenville, defense demand and data center projects.
The shift toward AI heavy data centers and higher energy density requirements could expose EnerSys to intense competition in lithium systems. If OEM validation, hyperscaler qualifications and supply chain set up for its new lithium data center product slip beyond the current fiscal 2028 revenue expectations, revenue growth and scale benefits in Energy Systems may disappoint.
See why 3 investors see EnerSys as 3% undervalued.
Result: Fair Value of $202.92 (UNDERVALUED)
Still, EnerSys could overturn this slightly bearish setup if record free cash flow, low leverage, and the defense-focused Greenville investment all support steadier earnings and valuation confidence.
Find out about the key risks to this EnerSys narrative.
Another View: EnerSys Through The Cash Flow Lens
The first fair value story for EnerSys leans on analyst targets and earnings multiples. A second angle comes from the SWS DCF model, which places future cash flow value at $186.02 while the share price trades at $196.30, implying the stock screens as slightly overvalued on this approach.
That gap is not huge in dollar terms, yet it raises a simple question for investors: Is it better to lean on analyst earnings scenarios or on the cash that EnerSys is expected to generate over time when judging today’s price?
Look into how the SWS DCF model arrives at its fair value.
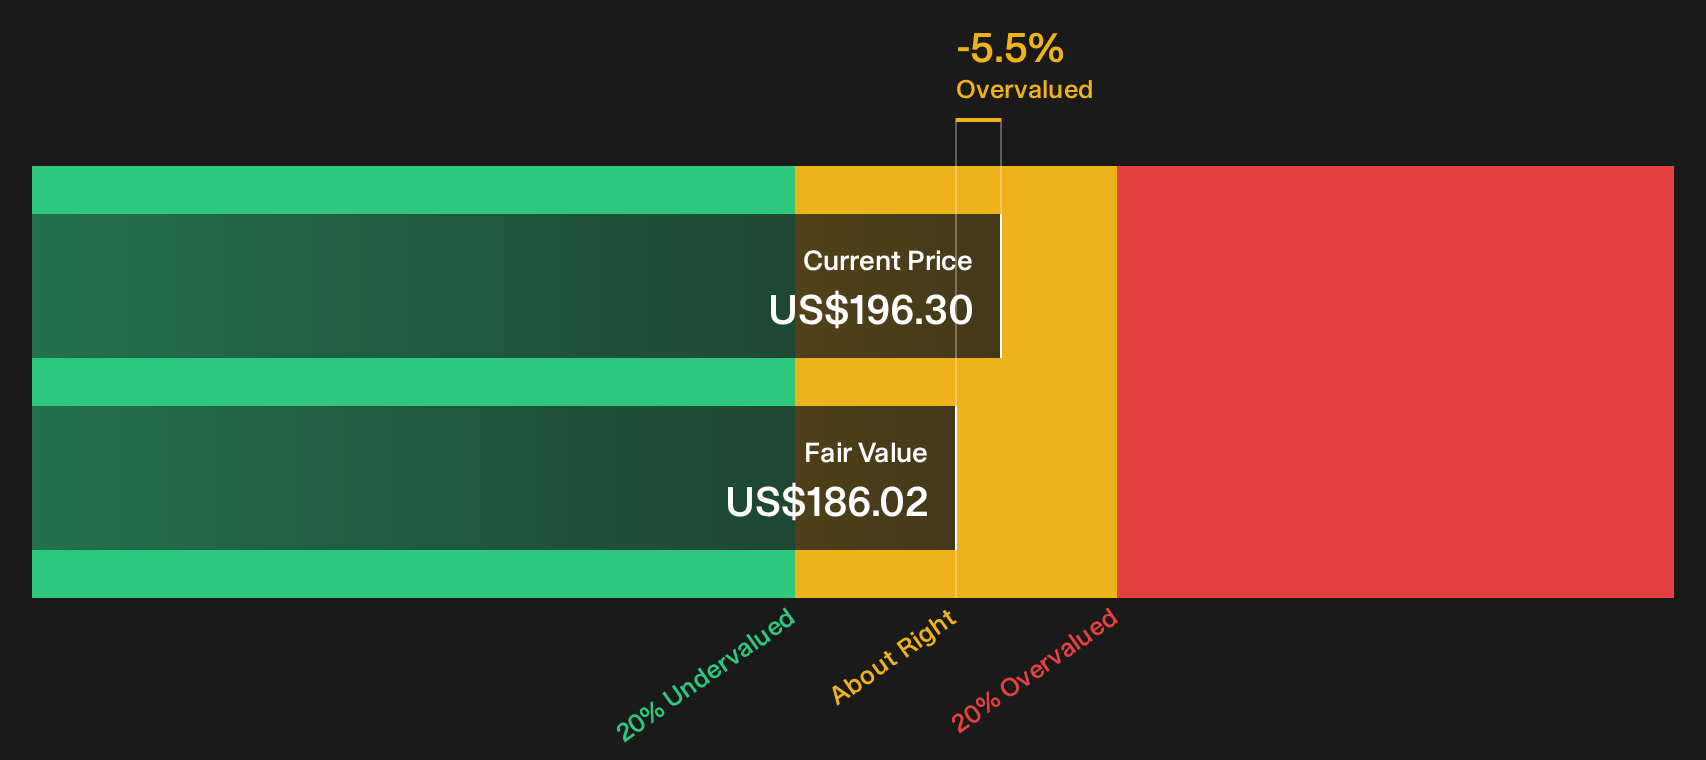
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EnerSys for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around EnerSys has been mixed in this piece, so consider acting promptly and stress test the numbers against your own approach. To see what the optimistic side of the ledger looks like in one place, review the 5 key rewards
Looking for more EnerSys-sized opportunities?
Do not stop with EnerSys. Use the Simply Wall Street Screener to quickly surface fresh ideas that fit your return goals and risk comfort before others move first.
- Target potential mispricings by hunting for quality businesses that trade below their estimated worth through the 31 high quality undervalued stocks.
- Lock in income-focused ideas by scanning for companies with strong payouts and resilient profiles using the 7 dividend fortresses.
- Dial down portfolio stress by concentrating on financially robust businesses with clean balance sheets via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com