


Argus recently raised its price objective for UFP Technologies (UFPT) to $334, putting fresh attention on how this medical packaging specialist is valued after a strong run in recent periods.
Recent trading has leaned in UFP Technologies' favour, with a 1-month share price return of 4.12% and a 90-day share price gain of 10.52%. This has contributed to a year to date share price return of 34.60% and a 1-year total shareholder return of 54.03%, indicating that momentum is still building rather than fading.
Scan other high-momentum healthcare manufacturers with solid business foundations using our curated list of solid balance sheet and fundamentals (25 results) as a starting point, alongside UFP Technologies.
UFP Technologies now trades around US$300 while Argus sees scope to US$334, and broader targets sit higher still. Is that gap a genuine discount, or is the market quietly flagging risk as expectations reset?
Most Popular Narrative: 15% Undervalued
On the most widely followed view, UFP Technologies screens as undervalued, with a fair value estimate of $355 against the last close near $300. That narrative leans heavily on the medical focus, margin profile, and the idea that recent investments can support higher earnings power over time.
The expansion of manufacturing capacity and product development centers in the Dominican Republic, along with new program launches for robotic-assisted surgery customers, sets the stage for sustained revenue growth tied to increased demand for sophisticated medical device components and packaging solutions.
Robust growth in multiple medical end markets, including patient services, interventional, surgical, and wound care, reflects the tailwind from a growing, aging population and rising prevalence of chronic diseases, which are likely to accelerate top-line growth as channel inventory destocking is now behind the company.
See why 4 investors see UFP Technologies as 15% undervalued.
Result: Fair Value of $355 (UNDERVALUED)
Still, UFP Technologies faces real pressure points, particularly its reliance on a few large medical customers and the potential for acquisition integrations to fall short of expectations.
Find out about the key risks to this UFP Technologies narrative.
Another View on UFP Technologies Valuation
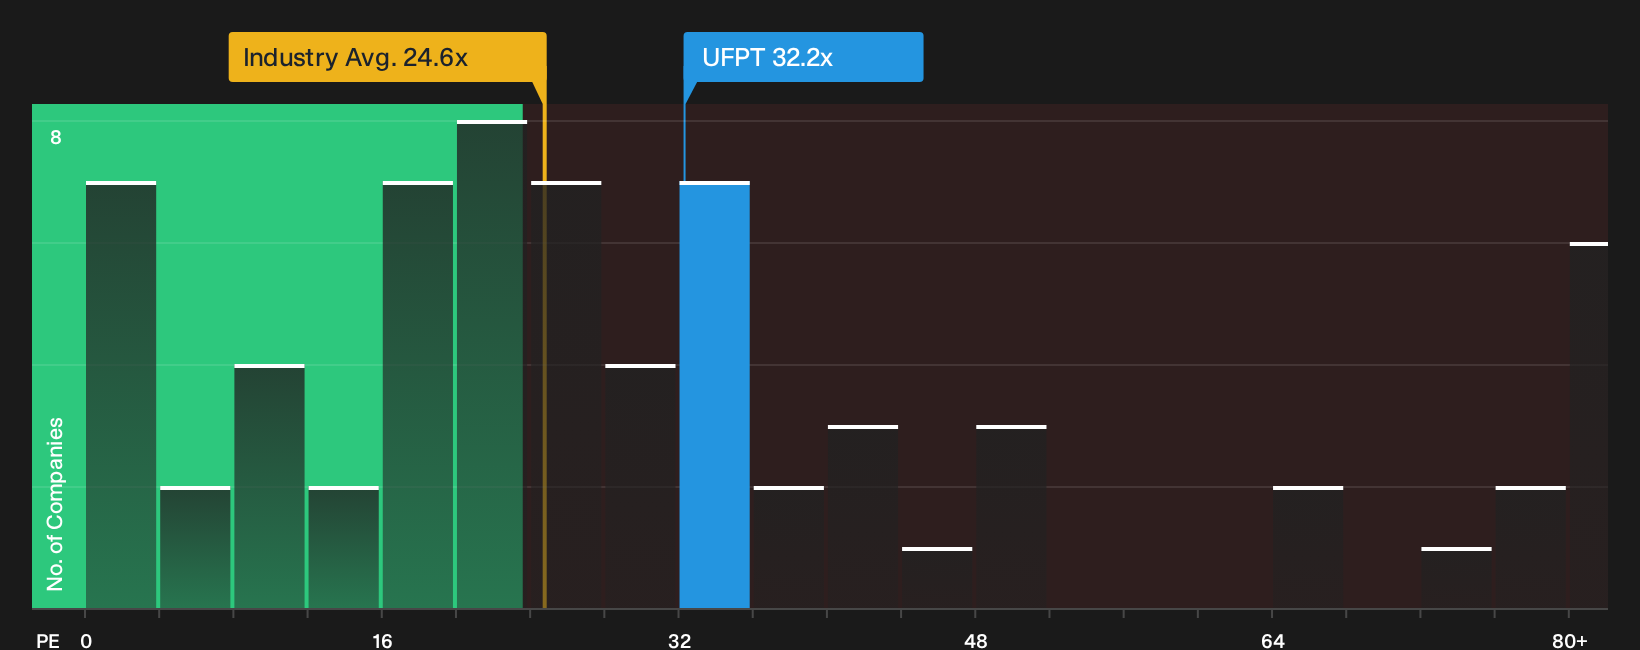
While the popular fair value story puts UFP Technologies at $355, the earnings multiple paints a tougher picture. The stock trades on a P/E of 32.2x compared with a fair ratio of 25.4x, the US Medical Equipment industry at 24.6x, and peers at 58.4x. Is that premium a comfort or a warning sign?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around UFP Technologies are clear, with optimism and concern sitting side by side. Move quickly, review the underlying data, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond UFP Technologies?
If you stop with UFP Technologies, you only see part of the opportunity set. Cast the net wider and let data do the heavy lifting for you.
- Target potential mispricing early by scanning a curated pool of underappreciated opportunities using the 19 high quality undiscovered gems.
- Prioritise resilience first by focusing on companies with stronger financial footing through the 31 resilient stocks with low risk scores.
- Zero in on quality paired with attractive entry points by working through the 31 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com