


Devon Energy has delivered a strong multi year share price run and is now in the spotlight after fresh activist pressure, which puts a sharper focus on whether the current valuation can be explained by its earnings power. With the stock back in focus and sector consolidation on the table, the core issue is how much of the recent enthusiasm is actually supported by the profit stream the business is generating today.
- Over the past 5 years, Devon Energy has returned 51.5%, which puts real weight on the question of whether the current price fairly reflects the earnings that underpin that performance.
- Calls from Toms Capital and other investors for Devon Energy to consider asset sales or even a full sale may reshape how investors think about the durability and timing of its future earnings and cash flows.
- There is a second opinion on Devon Energy worth weighing. See what analysts think Devon Energy's shares could be worth.
The stock's next move may depend on whether Devon Energy's current share price can be explained by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings based valuation question you are asking of Devon Energy across a wider set of companies, spend a few minutes with 31 high quality undervalued stocks.
Is Devon Energy Still Cheap on Earnings?
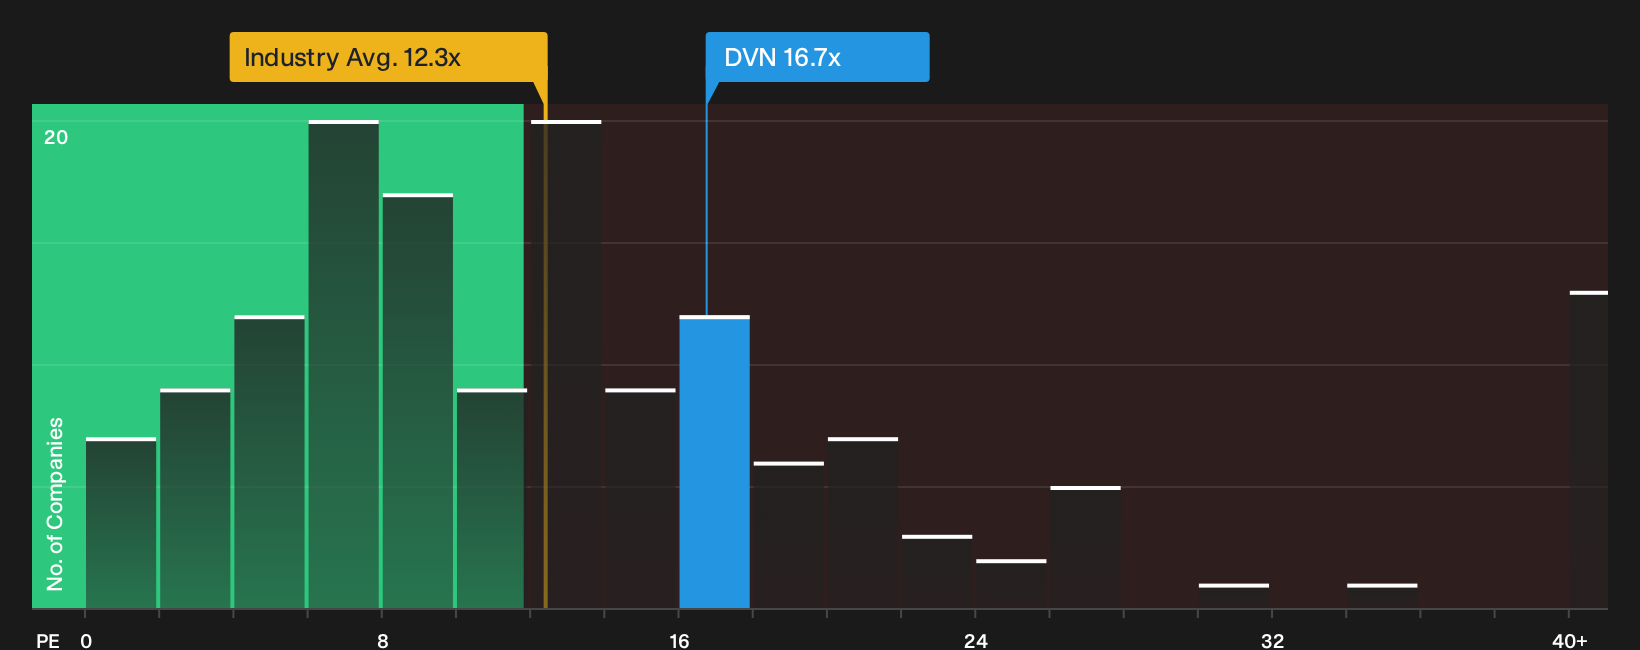
The P/E ratio is a useful lens for Devon Energy because earnings remain a central yardstick for oil and gas producers that already generate consistent profit. Devon Energy currently trades on a P/E of 16.7x, compared with an Oil and Gas sector average of 12.3x and a peer group at 16.9x, so the valuation clusters close to similar companies rather than at an extreme.
The Fair Ratio model, which estimates the multiple you might expect given Devon Energy’s size, risk profile and earnings quality, points to the stock changing hands below that tailored benchmark. As a result, the current P/E aligns more with a discounted earnings stream than a stretched one. Because Toms Capital is pushing for a potential sale or asset disposals, the market is already weighing whether the existing P/E leaves room for any deal premium or portfolio simplification to be reflected in the price. You can see how wide that gap is, and test the same P/E logic on other stocks, through. Explore the numbers behind Devon Energy's P/E valuation.
The Devon Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Devon Energy pick up exactly where this valuation puzzle leaves off, by spelling out which combinations of future growth, profitability and earnings power would need to play out for the stock to be worth meaningfully more or less than today. Rather than a single P/E or one model output, each narrative lays out the assumptions behind its view of fair value so you can track those expectations against Devon Energy's actual results as they are reported on the Community page.
One of the top community narratives on Devon Energy: 21% undervalued
"The ongoing company wide portfolio review that is targeting asset sales and simplification in what management describes as a strong market for quality assets…"
Discover why this Narrative puts Devon Energy at 21% undervalued.
One more Devon Energy check that belongs next to the share price
Before you stop at the multiples and activist noise, it is worth asking who is actually steering Devon Energy and how their pay packets line up with your interests. See who runs Devon Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com