


Executive reshuffle and what it might mean for Swedbank stock
Swedbank (OM:SWED A) is in the spotlight after announcing several senior leadership changes, including a new permanent Head of Group Business Support and an Acting Chief Compliance Officer, along with planned departures in key roles.
Investors have been digesting these leadership moves against a strong price backdrop, with Swedbank’s share price at SEK404.2 and a 30 day share price return of 4.74%. This contributes to a 24.22% year to date gain, while the 1 year total shareholder return of 55.08% signals powerful momentum built over several years, reflected in a 3 year total shareholder return of 161.31% and a 5 year total shareholder return of 235.93%.
See how Swedbank’s leadership reshuffle compares with other banks showing strong momentum and solid fundamentals in our hand picked list of solid balance sheet and fundamentals (206 results)
Bulls point to Swedbank’s strong recent shareholder returns and solid profit base. Bears focus on leadership turnover and a premium looking share price. Which side does the valuation actually support as of today?
Most Popular Narrative: 5% Overvalued
Swedbank last closed at SEK404.2, while the most followed narrative fair value sits at about SEK385.8, which points to a modest valuation premium and puts more weight on whether current momentum can be backed by future earnings and balance sheet strength.
The current valuation may not fully reflect the ongoing margin compression from lower interest rates in the region, with management explicitly noting policy rate cuts and downward repricing dynamics that will flow through both lending and deposit books, thus pressuring both net interest margins and earnings. Investors may be underestimating the potential for heightened regulatory and tax burdens, such as increased bank-specific taxes and rising corporate tax rates across the Baltics, which management flagged as likely to negatively impact profitability and lead to greater earnings volatility in future periods.
See why 21 investors see Swedbank as 5% overvalued.
Result: Fair Value of SEK385.81 (OVERVALUED)
Still, faster digital adoption or stronger Baltic demand could lift Swedbank earnings above current assumptions and challenge the slightly overvalued narrative.
Find out about the key risks to this Swedbank narrative.
Another view on Swedbank valuation
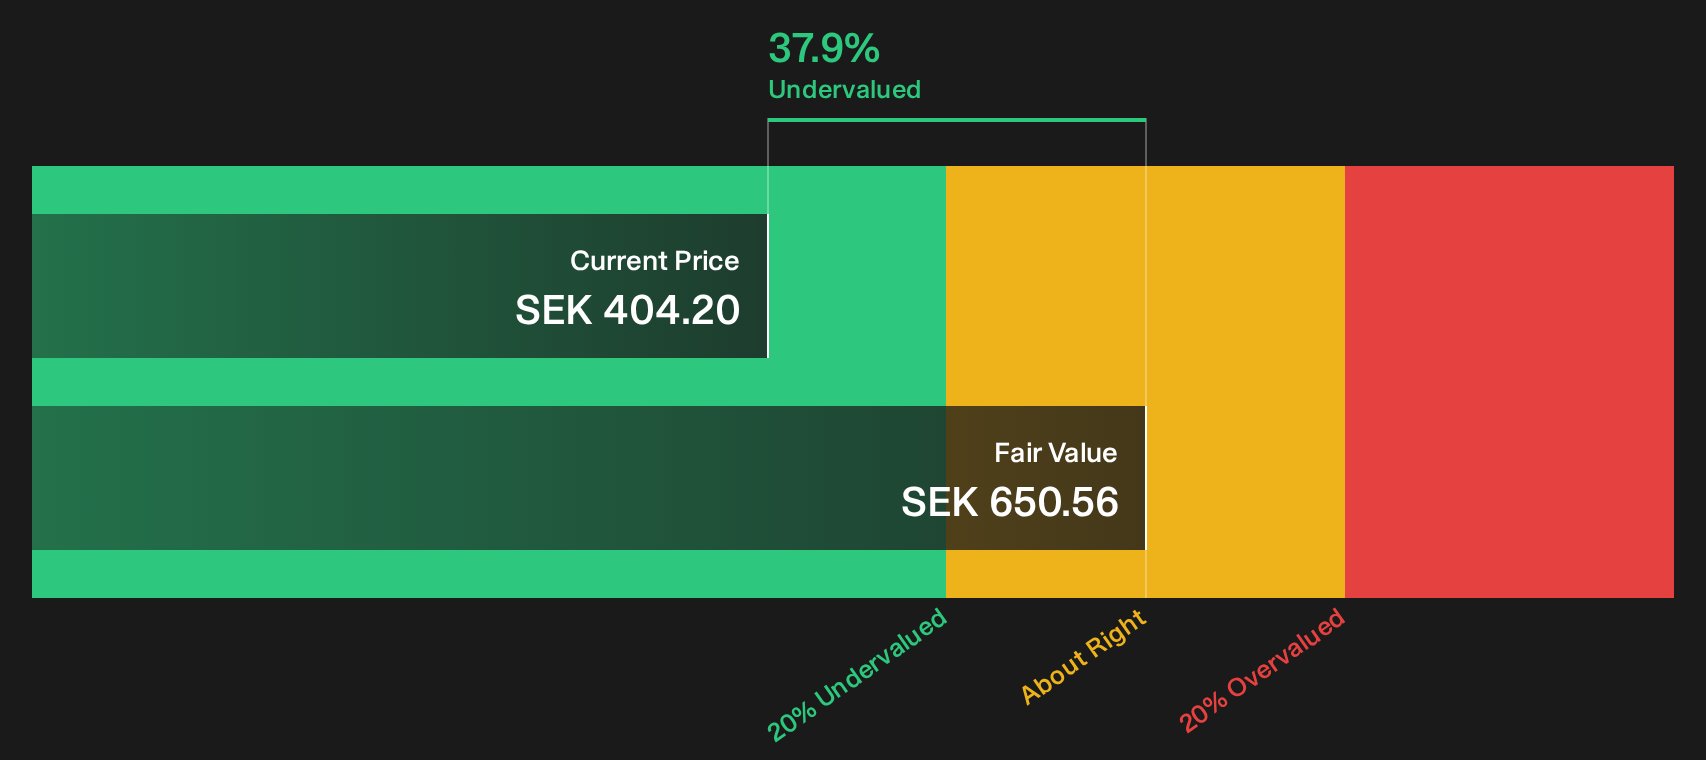
The earlier narrative framed Swedbank as modestly overvalued at around SEK385.8, based on analyst targets and earnings multiples. Our DCF model presents a different picture, with a cash flow based fair value near SEK650.6, which suggests the current SEK404.2 price could be materially lower than that estimate.
This gap between a P/E based fair value near SEK386 and a DCF outcome above SEK650.6 raises a simple question. Which set of assumptions around future cash generation do you find more realistic for Swedbank?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Swedbank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Swedbank valuation and leadership shifts can be hard to read, so move quickly, review the full risk reward balance, and decide where you stand with 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Swedbank?
If Swedbank has sharpened your focus, now is the moment to broaden your watchlist and compare it with other opportunities that fit different investing styles.
- Target resilient balance sheets and stronger fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (206 results).
- Hunt for potential value opportunities that combine quality and appealing pricing through the focused 192 high quality undervalued stocks.
- Prioritise income and stability by reviewing high yielding candidates in the curated 168 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com