


Corpay (CPAY) has expanded its suite of AI agents inside Corpay Complete, adding tools that analyze spend, automate coding, and handle expenses by voice, giving investors fresh information about its approach to enterprise payments technology.
Corpay’s latest AI rollout lands after a mixed few months for the ticker, with the share price down 5.23% over the past 30 days but up 10.50% on a 90-day share price return and delivering a 36.68% total shareholder return over the last year. This points to momentum that has cooled recently yet still reflects investors reacting positively over a longer stretch to product moves like these AI agents and shifting views on the company’s risk and growth profile.
Scan how Corpay’s AI push compares with other payment and fintech players already leaning into automation and machine intelligence by reviewing the curated 36 profitable AI stocks that aren't just burning cash.
Corpay is rolling out new AI agents just as the share price cools after a strong year, which leaves a practical question: Is it worth paying up today, or does patience for a lower entry make more sense?
Most Popular Narrative: 14% Undervalued
Corpay’s most followed narrative puts fair value at $461, above the recent $394.60 close, which frames the current AI rollout inside a broader multi year cross border and automation plan.
Corpay's continued expansion of its international cross-border platform, now supported by the migration of most Alpha volume onto a single global system and the addition of tokenized settlement rails through partners such as JPMorgan's Kinexys and BVNK, is expected to widen addressable payment flows and support future revenue and margin growth.
See why 14 investors see Corpay as 14% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, the thesis around Corpay can weaken quickly if the proposed US$100m U.S. Vehicle Payments settlement tightens pricing power, or if organic growth slows against analyst assumptions.
Find out about the key risks to this Corpay narrative.
Another View On Corpay’s Valuation
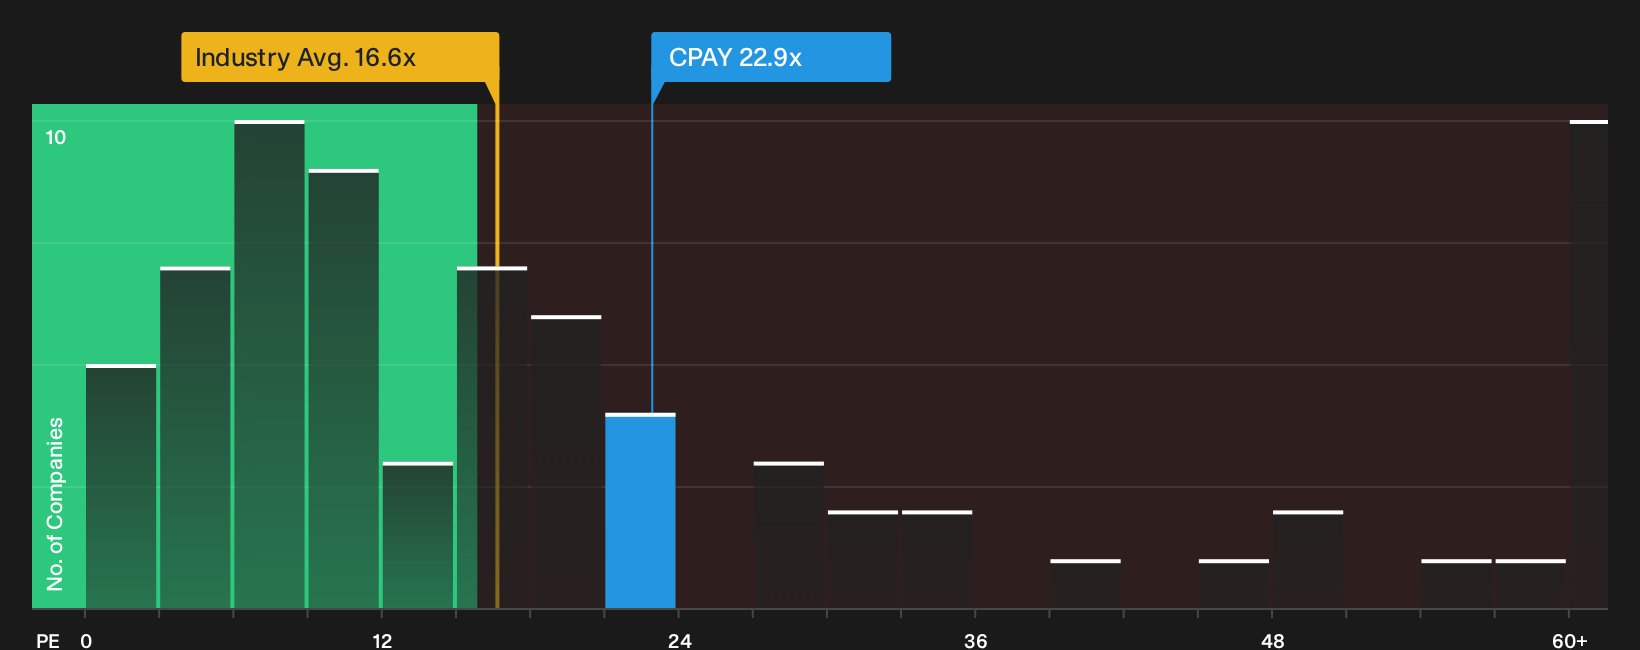
The first narrative leans on analyst targets and long term earnings forecasts to argue Corpay looks 14% below a $461 fair value. A different lens says something else. Corpay trades on a 22.9x P/E while the fair ratio is 16.8x and the US diversified financials group sits closer to 16.6x to 16.9x.
That gap means the market already pays a clear premium for Corpay relative to both peers and the fair ratio. Any slip in execution, AI monetisation or capital allocation could compress the multiple and hit returns, even if profits grow as expected. The question for investors is whether the extra price today matches the comfort level with that compression risk over the next few years.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Corpay’s valuation and AI rollout only matter if you act on them quickly and compare the figures with your own risk tolerance using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Corpay?
If Corpay’s story has you thinking about portfolio upgrades, this is the moment to widen your search and pressure test alternatives against the same standards.
- Target potential mispricing by scanning companies that screen as high quality yet out of favor using the 31 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that match your yield goals through the 7 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier balance sheets and resilient profiles with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com