


Valvoline (VVV) has caught investor attention after recent trading left the shares at $30.58, with mixed price performance over the past year and reported growth in both revenue and net income.
Recent trading has been choppy for Valvoline, with the share price falling 21.3% over the past 90 days after a 7.4% gain in the last week. The 1-year total shareholder return is down 12.5%, which points to fading longer-term momentum despite renewed short-term interest.
Scan beyond Valvoline's recent pullback and evaluate other service-focused businesses with choppy charts but solid fundamentals using our hand picked list of solid balance sheet and fundamentals (25 results).
Valvoline now trades well below the average analyst target, yet the recent pullback shows the market is not rushing in. Is that discount a genuine opportunity or a warning sign about quality and risk?
Most Popular Narrative: 29% Undervalued
Against the last close at $30.58, the most widely followed narrative anchors Valvoline’s fair value at $43.25, leaving a sizable valuation gap that only makes sense if the long term expansion and margin story holds together.
The consistent growth in same-store sales driven by both increased transactions and higher ticket sizes from premium service offerings remains in place, and recent guidance for system-wide same-store sales of 7.5% to 8% reinforces the view that Valvoline can keep translating resilient maintenance demand into revenue and earnings growth over time.
See why 2 investors see Valvoline as 29% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, the thesis around Valvoline can break if finished lubricant costs stay elevated and if weaker miles driven continue to pressure traffic and EBITDA margins.
Find out about the key risks to this Valvoline narrative.
Another View On Valvoline’s Valuation
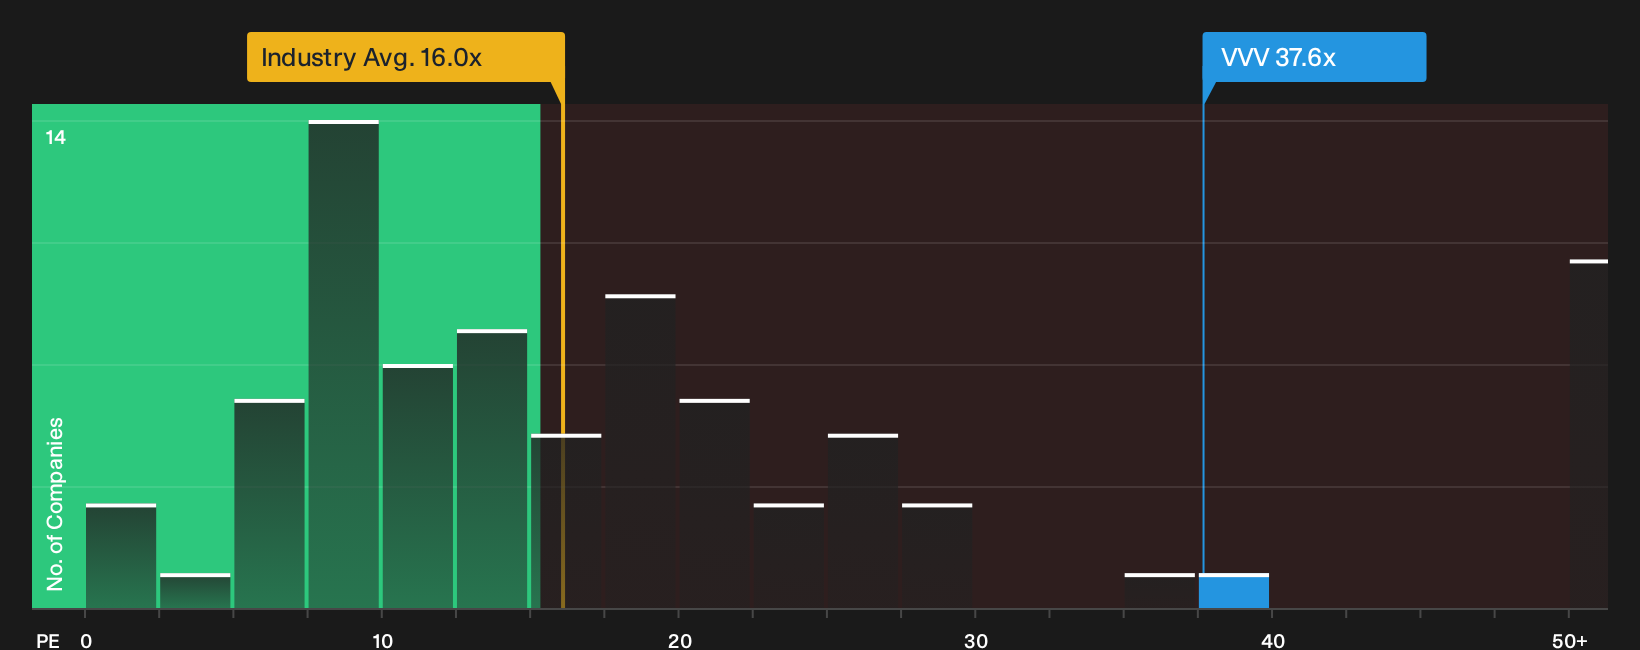
The first lens on Valvoline leans on analyst fair value at $43.25. A different check comes from its P/E. The stock trades on 37.6x earnings, versus 16x for the US Specialty Retail group and a fair ratio of 36.2x that our model suggests.
That premium hints at less margin for error if earnings or margins disappoint, even with a gap to analyst targets. This raises the question: does this richer multiple reflect quality, or does it simply raise the bar for what has to go right from here for Valvoline?
For a closer look at how this earnings multiple stacks up against peers over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around Valvoline leaves you torn, move quickly to weigh both sides of the story using our breakdown of 2 key rewards and 3 important warning signs
Looking for more ideas beyond Valvoline?
Do not stop at Valvoline. Use the Simply Wall Street Screener to uncover other opportunities that match your risk profile, return goals, and investing style.
- Target potential mispriced opportunities early and scan a focused set of 31 high quality undervalued stocks that combine appealing valuations with solid underlying financial profiles.
- Prioritize resilience over drama and filter for 31 resilient stocks with low risk scores that score well on financial strength and lower business volatility.
- Hunt for tomorrow's stories before they hit the headlines by reviewing 19 high quality undiscovered gems hiding in plain sight on the market's fringes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com