


Surging United States Treasury yields are shaking global borrowing costs and reminding investors that cheap capital is not guaranteed. When money becomes more expensive, attention often shifts toward founders who treat every pound as if it is their own and keep businesses resilient through cycles. This article looks at three London listed companies still run or chaired by their original founders and explains why that kind of stewardship can matter for long term shareholders today.
The founder led stocks covered below are only a small sample, since a broader screen surfaced 58 more companies with equally compelling stories that are not covered here.
If you want to identify and analyze founder run businesses for yourself, head straight into the Founder-Led Companies screener
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks is a founder-led mixer specialist, with co-founder leadership still shaping how the Fever-Tree brand develops across premium tonics, sodas and cocktail mixers sold in the UK, US, Europe and beyond. The group is valued at about £938 million.
Fevertree Drinks fits this founder-led theme because the people who built the Fever-Tree brand are still closely involved in how it grows, how the products evolve and how the story is told to customers.
"The partnership with Molson Coors is intended to secure U.S. profit growth, but an overreliance on one strategic partner may expose Fevertree to unfavorable contract renegotiations, possible margin dilution if guaranteed royalties fail to match rising costs, and slower-than-expected U.S. market penetration, all of which could weigh on future profits."
This raises the question of what might happen if one quiet pressure on Fevertree Drinks eventually forces management to choose between protecting margins and protecting growth.
That trade off is exactly what the full narrative for Fevertree Drinks unpacks, showing where Fevertree Drinks could accelerate, pause, or completely reframe its growth versus margin equation.

Computacenter (LSE:CCC)
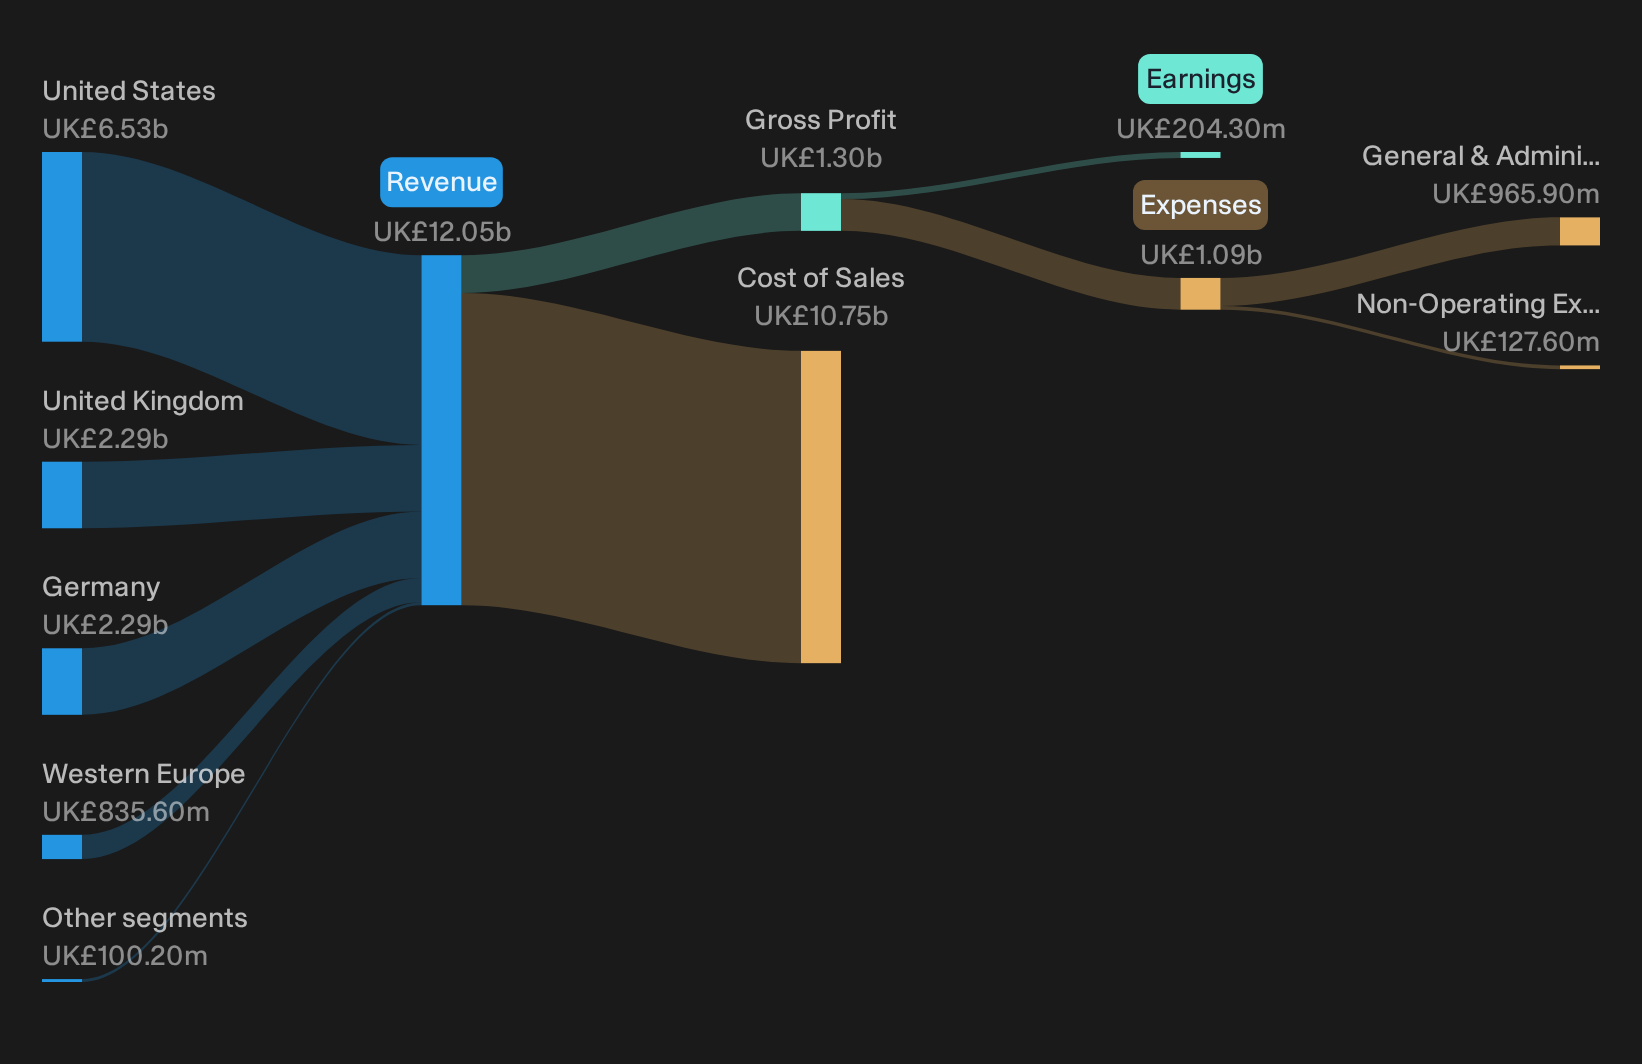
Computacenter is a founder-influenced IT services provider that runs procurement, managed services and workplace support across large organisations, generating about £12.1b from computer services and carrying a market value of roughly £5.7b.
Computacenter ties the founder-led idea directly into long-serving leadership, major insider ownership and a managed services model built on long contracts where clients trust the same team year after year. Investors watching this governance story will care how one unseen pressure eventually feeds through to margins and pricing power.
That pressure on pricing power makes it worth scanning the analysis report for Computacenter to see where Computacenter’s long contracts could still surprise the market.
W.A.G payment solutions (LSE:EWG)
W.A.G payment solutions runs a founder-led payments and mobility platform for truck fleets across Europe, with long-tenured leadership focused on integrated fuel, toll and fintech services. Most of its revenue, about €2.4b, comes from Payment Solutions, with Mobility Solutions contributing roughly €134 million, and the group carries a market value near £668 million.
For investors using this founder-led screen, W.A.G payment solutions is where long-term leadership meets a push to turn a sprawling fuel and toll network into a single, sticky payments platform for commercial fleets.
"The company's strategic shift towards an integrated, digital platform (Eurowag Office) is set to accelerate wallet share per customer via cross-selling and subscription bundling, enabled by rising demand for digitalization and end-to-end solutions in B2B mobility payments, which is likely to boost both recurring revenue and net margins as more customers migrate in 2025–2026."
What happens if one quietly growing cost of capital pressure collides with that plan to scale a richer, recurring earnings mix.
If that potential collision concerns you, read the full narrative for W.A.G payment solutions to see how W.A.G payment solutions could turn cost of capital pressure into accelerating platform leverage.

Seeking Alternatives Before The Crowd
Fresh ideas move first. The strongest themes can gain momentum while most investors are still watching old favourites. Scan new angles that are under the radar for now and look for opportunities early.
- Spot cash rich companies before momentum really starts by running the list of solid balance sheet and fundamentals (9 results), which filters for sturdy fundamentals while they are still being priced like afterthoughts.
- Focus on potential income workhorses instead of chasing falling yields by checking the 1 dividend fortresses, which highlights high payout candidates built around durability, not hype.
- Position ahead of potential infrastructure build outs by scanning the 40 power grid technology and infrastructure stocks, curated for businesses exposed to long term grid upgrades and electrification demand.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com