


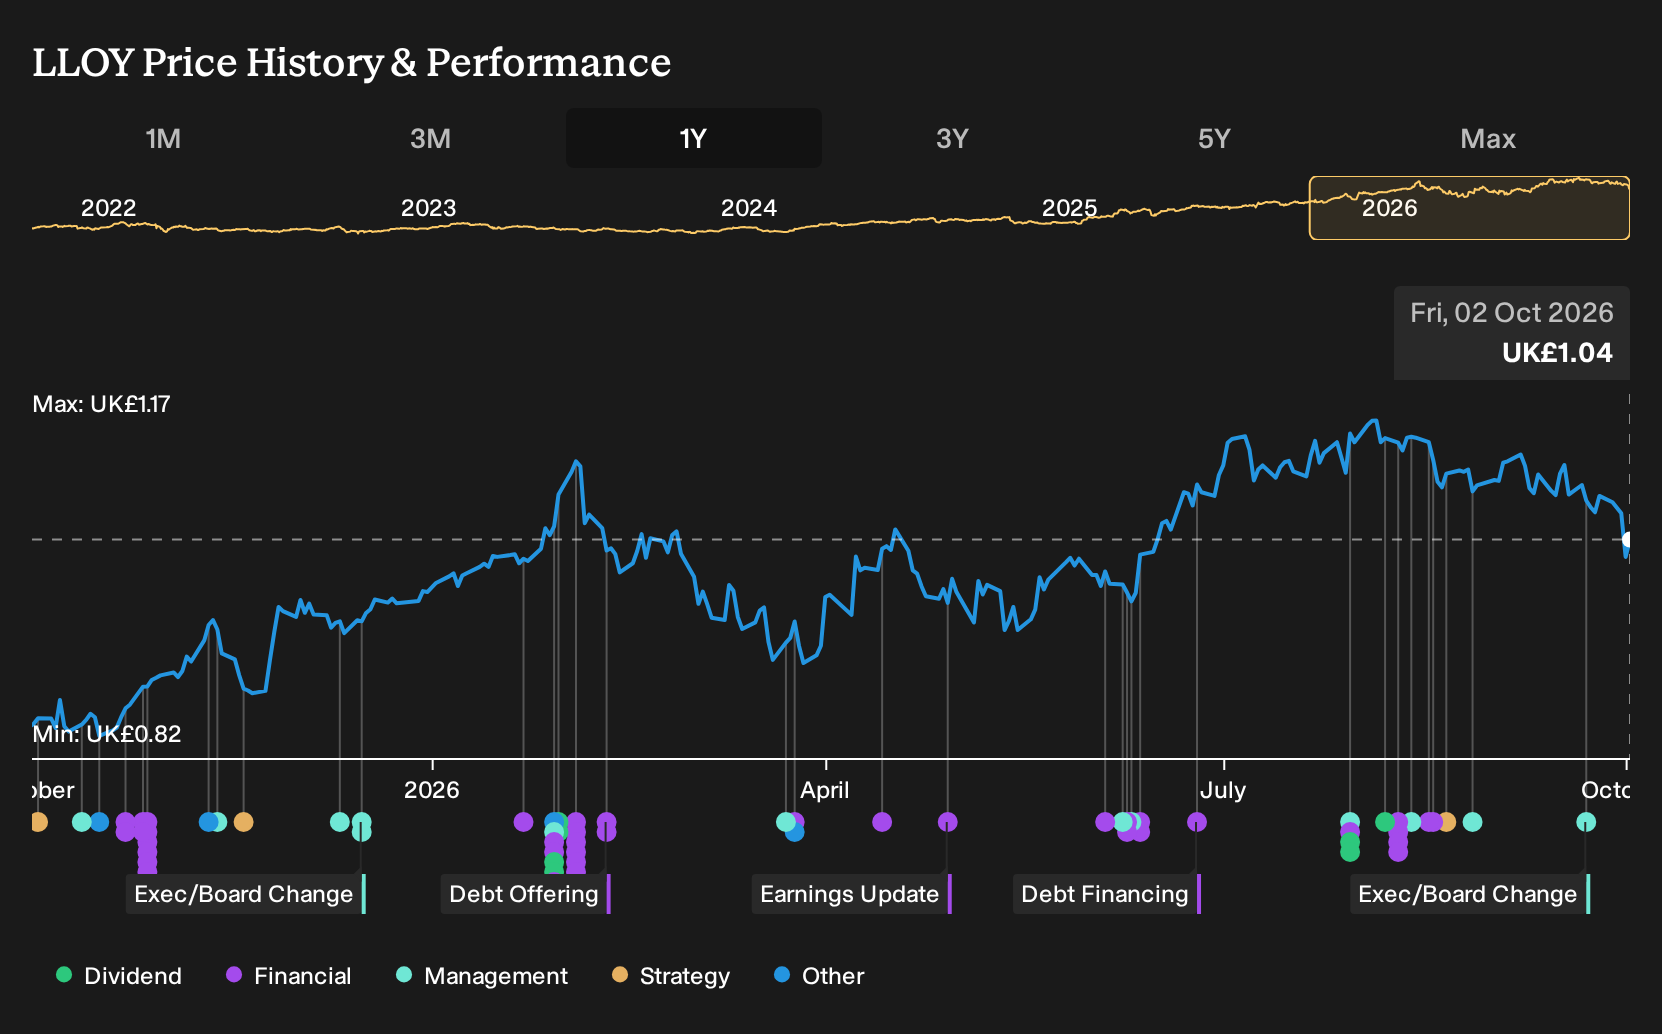
If you only glanced at the headlines on Lloyds Banking Group, the story looked finely balanced. Bulls talked up digital transformation and UK demographic tailwinds. Bears focused on mortgage exposure and rising IT and compliance bills. For Lloyds Banking Group shareholders, the return over the past year was 28.0%, including dividends. If you had been weighing those opposing views on 2 October 2025, what really tipped the scales for you?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Lloyds Banking Group. Zero in on 8 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Lloyds Banking Group
The shares cost £0.84 at the start of the period, and Lloyds Banking Group sat between two well argued stories about where the bank could head next.
On the optimistic side, the bull narrative put fair value at £0.89, based on assumptions that revenue could rise by 7.9% a year and profit margins might reach 25.8% within three years.
The bear case set fair value at £0.53, warning that heavy UK mortgage exposure and rising technology and compliance costs could restrict future profitability.
What The Results Changed For Lloyds Banking Group
Lloyds Banking Group reported Q2 2026 revenue of £5,120m and net income of £1,423m, both above Q2 2025 levels. That supported the optimistic case that expected stronger earnings. Net margin sat at 27.8%, matching the prior year figure, so the bullish argument for higher profitability per pound of sales was not yet confirmed. Overall, the evidence cut both ways.
The key assumption tested here was margin expansion. When you see a thesis built on rising profitability, check whether net margin is actually moving up in later filings instead of relying only on higher revenue or profit.
What Lloyds Banking Group's Price Already Assumes
Today Lloyds Banking Group trades at £1.04, and the selected Narrative’s Fair Value sits below that level. The Narrative argues that a lot of confidence is already baked in about the bank’s UK focus and its structural hedge earnings.
The key question now is what has to keep working for the current valuation to add up. A buyer at today’s price would need to judge whether Lloyds Banking Group can scale its AI led cost programmes without letting technology, compliance and hedge risks eat into future profitability.
"The main requirement is that Lloyds Banking Group scales its AI enabled transformation and cost saving programmes sufficiently to offset rising technology, compliance, regulatory and remediation costs, while maintaining efficiency targets beyond 2026."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Where Lloyds Investors Might Look Next
After thinking through Lloyds, you might wonder where a different banking mix could matter.
One large institution leans heavily on fee income from wealth and insurance, instead of relying only on classic lending spreads.
It also concentrates more of its effort in Asian markets, tying earnings to cross border capital flows and expanding affluent wealth.
Management is trimming smaller operations and recycling resources into these priorities, looking for a leaner base.
If clients keep seeking investment and protection products, that shift could leave this bank playing a distinct role in global finance.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 31% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com