


With Canada pushing to deepen trade and investment ties with India, local dividend payers suddenly matter more. Cross border deals can pull capital across markets, lift volatility and leave income focused investors craving something steadier. Reliable Canadian dividend stocks with yields above 3% and solid coverage offer that anchor. This article highlights three such dividend powerhouses and explains what income seekers may want to watch before committing fresh money.
The three dividend stocks covered below are only a sample of what income investors might find. The full screen surfaced 17 more companies with yields above 3% and similarly compelling income stories that are not discussed here.
If you want to identify and analyze those extra high yield opportunities with strong coverage, head straight to the Dividend Powerhouses (3%+ Yield) screener.
Canadian Tire Corporation (TSX:CTC.A)
Canadian Tire Corporation ties directly into the Dividend Powerhouses theme because its 3%+ yield leans on everyday retail spending, with store traffic, loyalty cards and financing all feeding the cash flows that support regular income for shareholders.
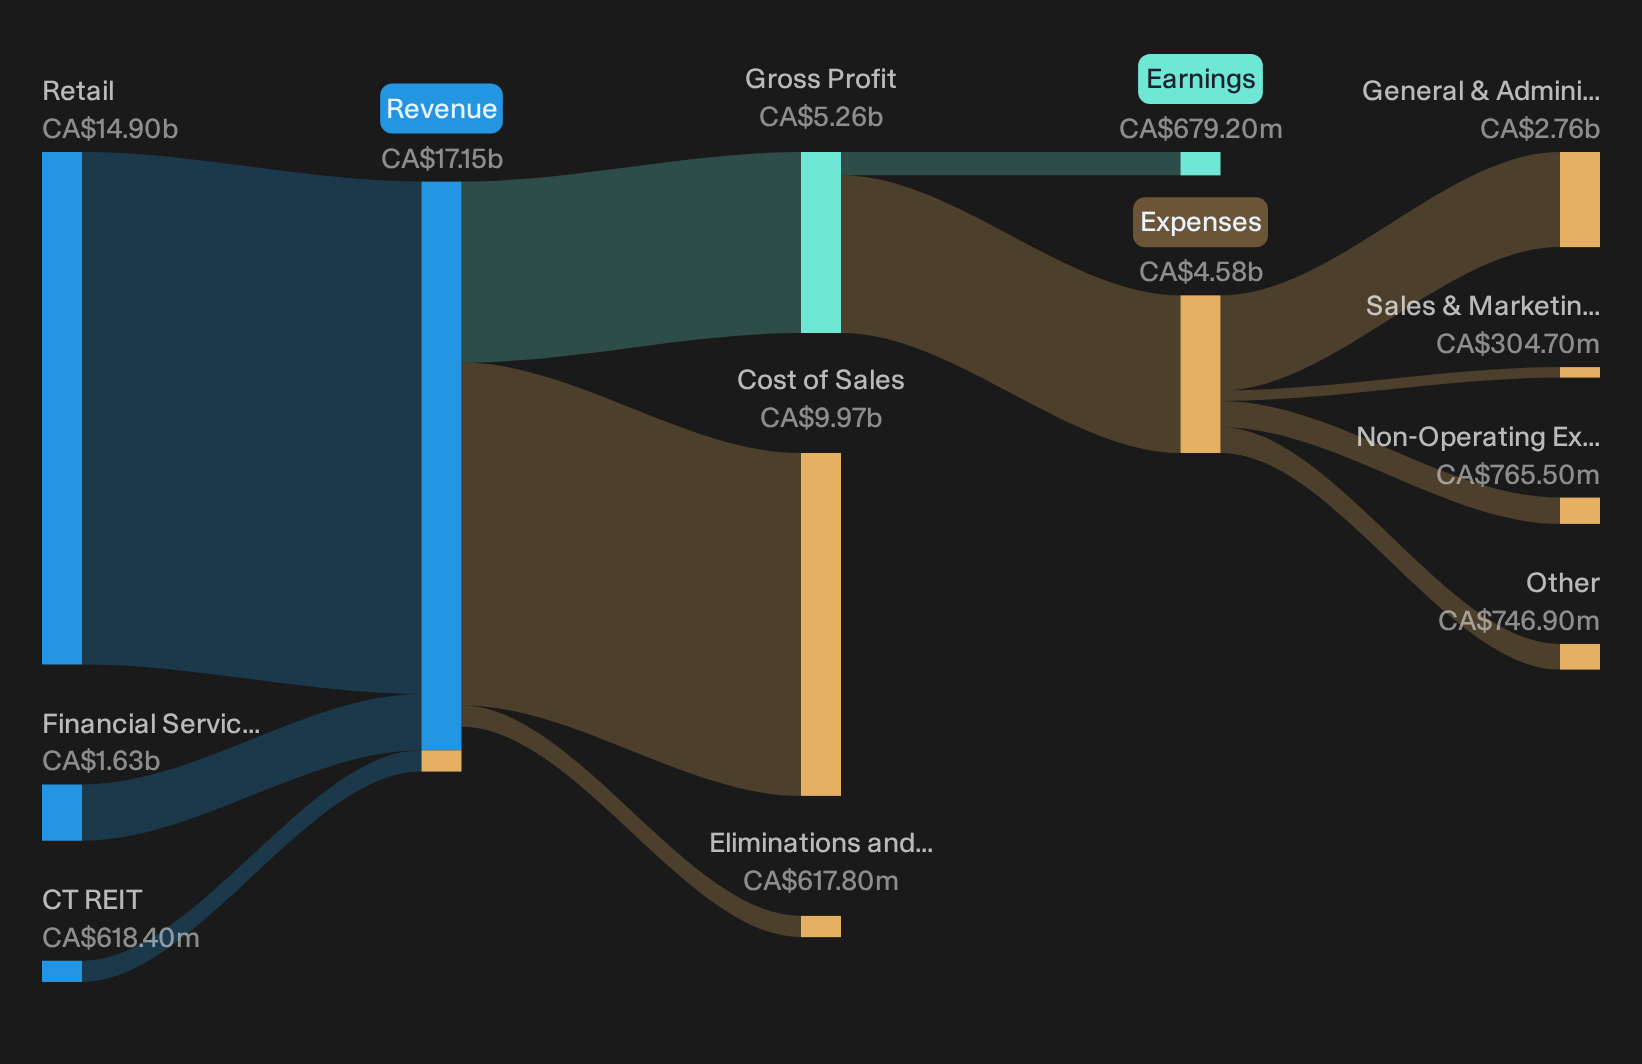
Canadian Tire is a diversified Canadian retailer and financial services group, with most of its revenue coming from the Retail segment at about CA$14.9b, plus CA$1.6b from Financial Services and CA$618m from CT REIT, and it carries a market value near CA$10.1b.
"Ongoing investments in store refreshes, loyalty programs, and supply chain optimization are expected to drive cost efficiencies over time. However, the current and projected increase in fixed and variable costs, combined with wage and utility inflation, could pressure net margins and delay anticipated operating leverage improvements."
For income focused investors in Canadian Tire, what happens if a single pressure point quietly reshapes how comfortable that dividend really feels?
If that pressure point matters to you, read the full narrative for Canadian Tire Corporation to see whether rising costs are masking a stronger long term income story.
Exco Technologies (TSX:XTC)
Exco Technologies is a mid sized CA$315 million tooling and auto parts group. It earns about CA$329 million from Automotive Solutions and CA$316 million from Casting and Extrusion, with its long term interior contracts helping underpin the 3%+ dividend theme.
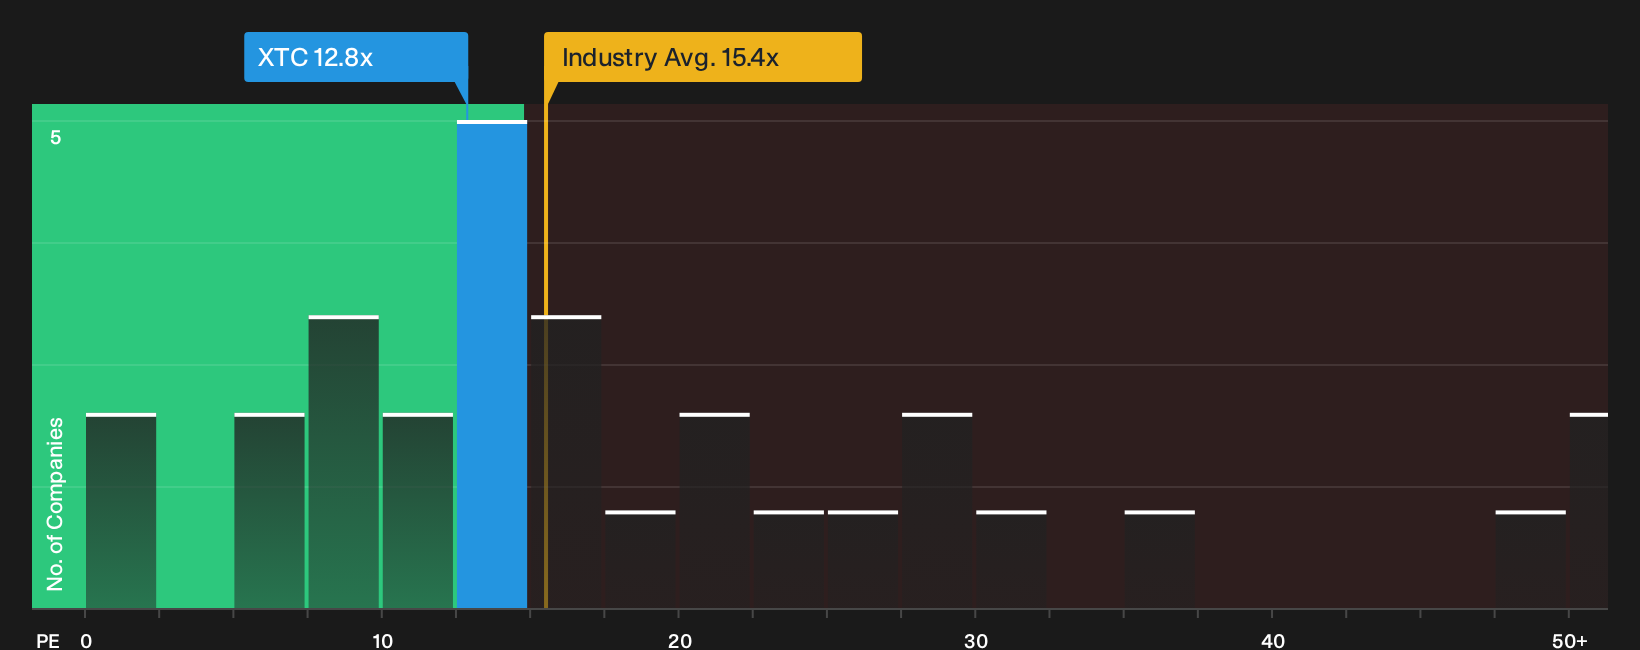
A 4.99% yield, Automotive Solutions cash flows backed by long term OEM contracts, and a P/E of 12.8x keep Exco Technologies firmly in Dividend Powerhouses territory. The income story leans on that steady order book, particularly given that a change in earnings quality could affect how secure that payout appears.
That earnings quality question is exactly why income investors often start with the 3 key rewards and 1 important major warning sign to see what might be quietly reshaping Exco Technologies' dividend profile.
Canadian Natural Resources (TSX:CNQ)
Canadian Natural Resources is a heavyweight in the Dividend Powerhouses screen, using its large upstream oil and gas production base and midstream assets to turn steady output into the kind of cash flow that can support a covered, income friendly payout.
Canadian Natural Resources runs a global oil and gas operation built around Canadian oil sands mining and upgrading, which generated about CA$20.8b, and North American exploration and production at roughly CA$21.3b, with smaller contributions from midstream and other segments, and the stock carries a market value near CA$142.4b.
"Recent accretive acquisitions have expanded production and reserves with minimal increase to the 2025 capital budget. This positions Canadian Natural for immediate cash flow growth and increased future revenues as these assets are developed."
What really tests that dividend profile is how one future shift in earnings power interacts with the current payout ambitions.
If that earnings shift is what you care about, read the full narrative for Canadian Natural Resources and see how Canadian Natural Resources could turn today’s cash engine into accelerating income power.

Seeking Fresh Alternatives Before They Fly
Some of the most interesting opportunities often move first and get talked about later. Scan fresh ideas with breakout potential that are under the radar for now, and act while they are still early in the conversation.
- Target lower-volatility upside by reviewing a curated 8 resilient stocks with low risk scores that keeps resilience front and center while the market chases whatever is flying this week.
- Hunt for under the radar growth by running the 9 high quality undiscovered gems before these quieter stories build momentum and attract wider attention.
- Position ahead of rising demand by using the 40 power grid technology and infrastructure stocks and track businesses tied to critical infrastructure upgrades while it still feels early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com