


Canada is pushing to deepen trade and investment ties with India through the proposed CEPA deal, with both countries aiming to grow bilateral trade significantly by 2030. That kind of long-term ambition keeps attention on Canadian companies that can turn steady cash generation into real value. This article highlights three Canadian stocks whose cash flows look underpriced today, based on discounted cash flow estimates, and explains why they may deserve a closer look.
The three stocks discussed next are just a sample from this idea, and the full screen surfaced 5 more companies with equally compelling cash flow stories that are not covered here. To identify and analyze the wider opportunity set right now, head straight to the Undervalued Stocks Based On Cash Flows screener
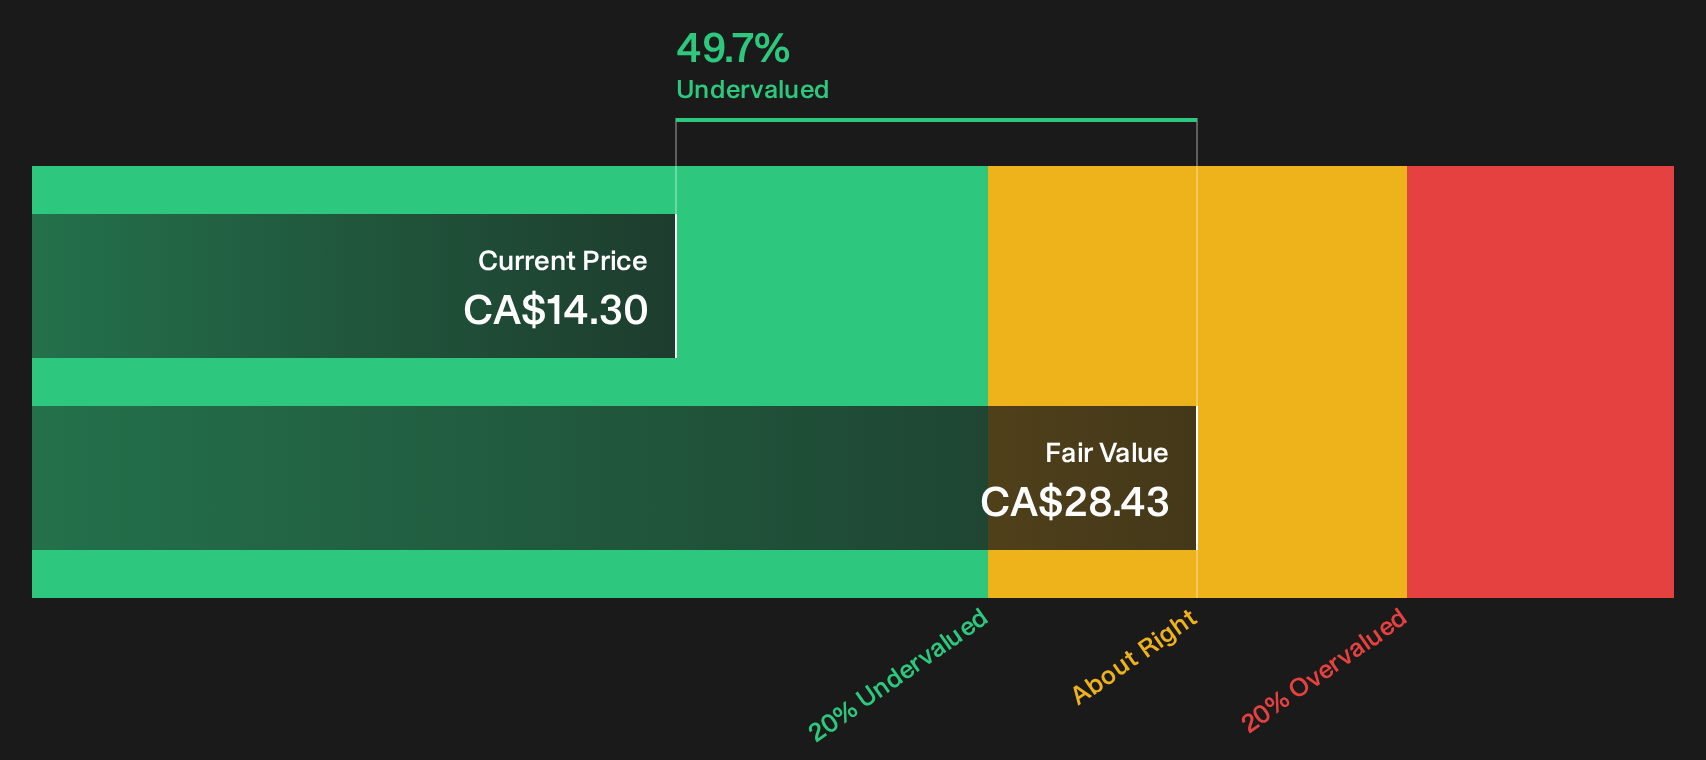
Groupe Dynamite (TSX:GRGD)
Groupe Dynamite runs the Dynamite and Garage fashion chains. A single apparel and accessories business drives the cash flows that anchor its DCF valuation within this screener’s theme.
Groupe Dynamite generates about CA$1.49b in annual revenue from retail apparel and accessories, spanning brick and mortar stores and e commerce. The stock carries a market value near CA$5.85b.
For investors tracking how cash flow can re rate a retailer, Groupe Dynamite offers a clear case study in what happens if a single key assumption breaks.
That hinge point is exactly where the story gets interesting, and the full narrative for Groupe Dynamite shows how that single break can either accelerate or quietly stall Groupe Dynamite.
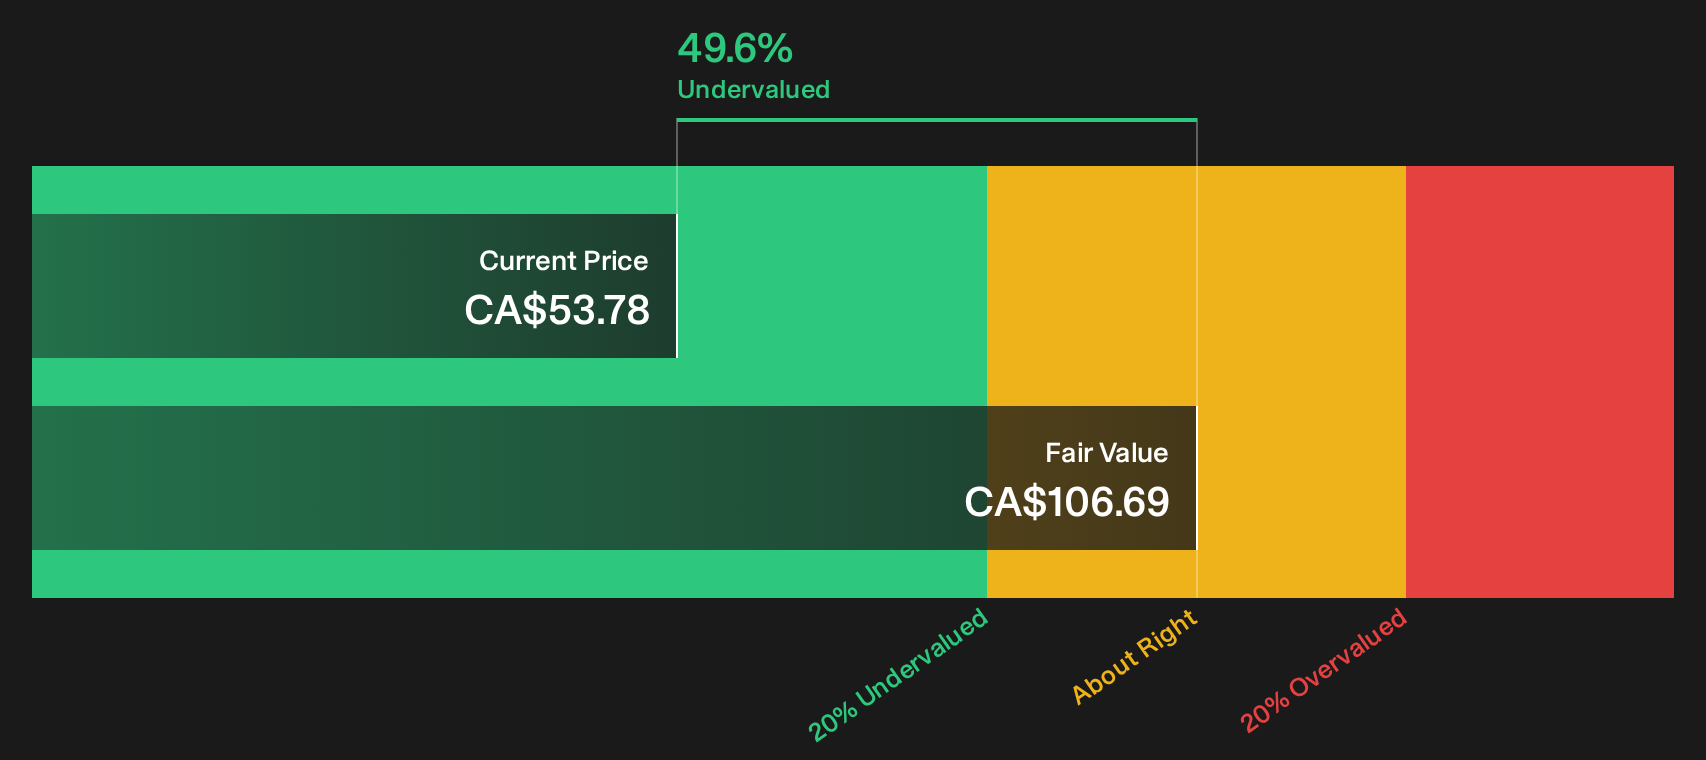
Suncor Energy (TSX:SU)
Suncor Energy is an integrated producer where long lived Oil Sands assets and the connected refining and marketing network anchor the cash flow story that puts it in this cash flow focused screen.
Suncor Energy generates about CA$26.9b from Oil Sands, CA$36.8b from Refining and Marketing, and CA$2.5b from Exploration and Production, with corporate eliminations offsetting CA$9.5b. The business has a market value near CA$116b.
For this screener, the appeal is that Suncor Energy ties together upstream cash generation with downstream pricing power. This gives you a single integrated play on how efficiently those cash flows can be turned into long term value.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
The real test for Suncor Energy is what happens if that one operating pressure quietly shifts in either direction for margins.
If that pressure point matters to you, the full narrative for Suncor Energy shows how reliability, capital choices and cash returns could be quietly accelerating or stalling Suncor Energy’s story.
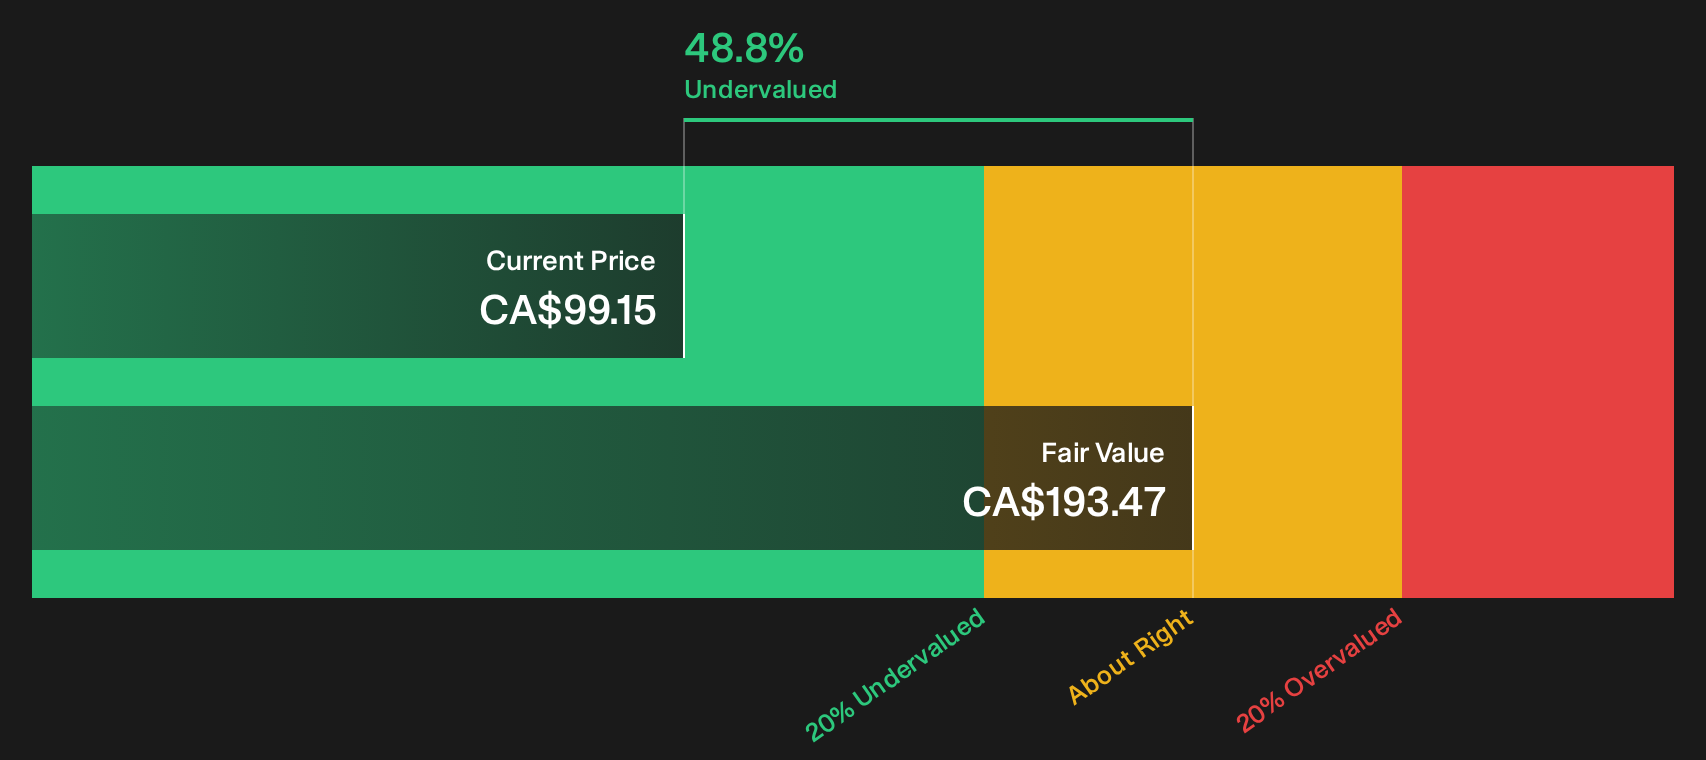
Chemtrade Logistics Income Fund (TSX:CHE.UN)
Chemtrade Logistics Income Fund runs a chemicals platform where the Sulphur and Water Chemicals segment supplies sulphuric acid and water-treatment inputs that support the cash-flow theme. The fund reports CA$738 million from Electrochemicals and CA$1.39 billion of segment adjustments, and carries a market value near CA$1.6 billion.
Chemtrade Logistics Income Fund fits into this cash flow focused screen as an industrial supplier whose sulphur and water treatment operations generate recurring demand across multiple end markets. This is where the potential mispricing of its future cash generation starts to get interesting.
"Chemtrade's expanding focus on water treatment solutions, reinforced by the Polytec and Thatcher acquisitions, positions the company to benefit from persistently rising demand from municipalities and food processing industries, supporting durable revenue growth and improved earnings stability as water scarcity and regulatory pressures intensify globally."
The key variable is what happens if a quiet shift in contract terms and customer mix subtly reshapes pricing power and margins in those projects.
If that shift is what you care about, the full narrative for Chemtrade Logistics Income Fund shows how Chemtrade Logistics Income Fund’s pricing power, contracts and cash generation could be quietly accelerating.
Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move first. By the time a breakout is obvious, early momentum is already flying and ideal entry points are dropping away. Scan these under the radar lists now and get in early.
- Target steadier compounding by reviewing a curated mix of resilient businesses through the 8 resilient stocks with low risk scores before the crowd chases their momentum.
- Ride the next wave in infrastructure demand by checking hand picked enablers of grid upgrades with the 40 power grid technology and infrastructure stocks while the story still flies under most radars.
- Track early leaders in automation by running through the focused list in the 89 robotics and automation stocks before valuations reflect a full robotics breakout.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com