


Rockwell Automation (ROK) is back in focus after its FactoryTalk and PlantPAx systems were integrated into PBS Biotech’s MiniPRO bioreactor platform, extending the company’s reach further into cell therapy manufacturing workflows.
Recent moves in the Rockwell Automation share price suggest buyers are leaning in. The stock has a 1-day share price return of 2.7% and a 7-day share price return of 5.4%, while the 90-day share price return shows a 3.1% decline that tempers the shorter-term momentum.
At a latest share price of US$454.35, the year-to-date share price return of 14.0% sits alongside a 1-year total shareholder return of 32.1% and a 3-year total shareholder return of 64.3%. Taken together, these figures indicate that rewards over longer holding periods have differed from those over the most recent quarter.
Partnerships such as PBS Biotech’s MiniPRO integration and the September collaboration with Tekna Automazione e Controllo and Prometeon Tyre Group provide examples of how Rockwell Automation is seeking to deepen its role in life sciences and tire manufacturing. These developments can influence how the market weighs growth opportunities against execution risk in the current valuation.
Scan Rockwell Automation’s peers riding similar factory digitization themes by checking the hand-picked 89 robotics and automation stocks that are also wiring their futures into critical industrial workflows.
After a sharp run that has lifted Rockwell Automation over the past week, while the 90 day return still shows a pullback, does the current setup still tilt the risk reward in buyers’ favour or not?
Most Popular Narrative: 5% Undervalued
On the prevailing narrative, Rockwell Automation’s fair value of $478.96 sits modestly above the latest close at $454.35, which puts the current enthusiasm in context rather than framing it as runaway optimism.
Additional adoption of connected devices, advanced analytics, and AI driven software is reflected in 18% organic growth in Software & Control and a 34.8% margin in Q3 2026. This supports the view that a richer software mix can lift blended net margins and earnings as these offerings scale further.
See why 41 investors see Rockwell Automation as 5% undervalued.
Result: Fair Value of $478.96 (UNDERVALUED)
Still, Rockwell Automation’s story can change quickly if delayed customer projects in key industries persist or if component cost inflation continues to squeeze operating margins.
Find out about the key risks to this Rockwell Automation narrative.
Another View: What Multiples Say About Rockwell Automation
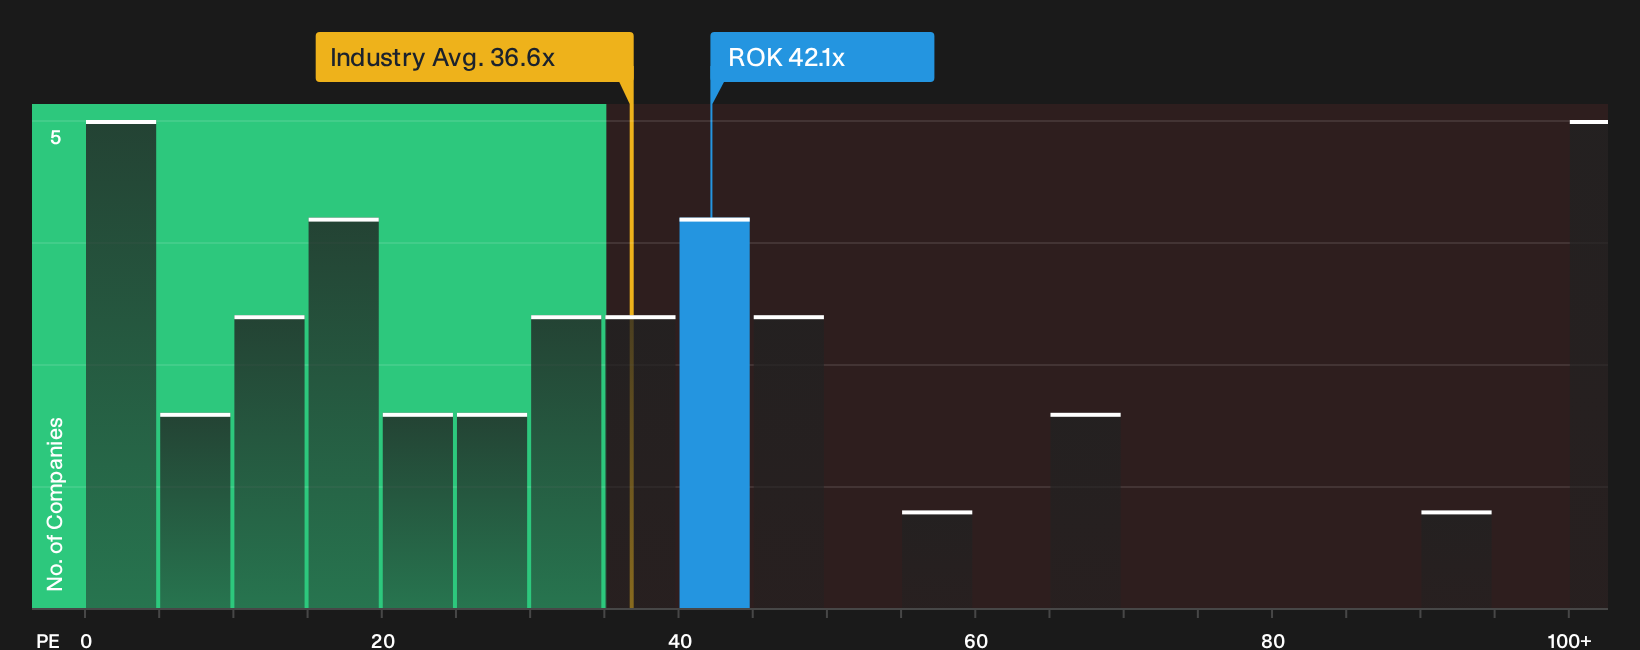
The fair value narrative leans on detailed earnings forecasts, yet Rockwell Automation’s current P/E of 42.1x tells a more demanding story. It sits above the US Electrical industry at 36.6x and above the 36.5x peer average, while the fair ratio of 27.2x points to a lot of optimism already in the price.
That gap suggests less margin for error if growth or margins undershoot analyst expectations, so the key question is whether you believe Rockwell Automation can keep justifying this richer multiple as conditions evolve.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the recent Rockwell Automation share performance and valuation can pull you either way, so move quickly, review the data carefully, and decide where you land after weighing the 1 key reward and 1 important warning sign.
Looking for more Rockwell Automation style ideas?
If Rockwell Automation has sharpened your focus on quality, now is the moment to broaden your watchlist before the next wave of opportunities moves without you.
- Target resilient compounding potential by scanning a 31 high quality undervalued stocks that combine quality fundamentals with prices that sit below their assessed worth.
- Strengthen your income plan by reviewing a 7 dividend fortresses built around higher yields that still keep an eye on sustainability.
- Protect your downside first by filtering a 31 resilient stocks with low risk scores where balance sheets and risk scores help you sleep at night.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com