


Why BlackBerry stock is back in focus
BlackBerry (TSX:BB) moved onto investor watchlists after raising full year revenue guidance to a range of $616 million to $636 million, alongside reporting stronger second quarter sales and net income on September 24.
Recent earnings and the raised guidance have coincided with a sharp shift in sentiment toward BlackBerry, with the share price up 24.34% over the past 30 days and a 153.45% year-to-date share price return, while the 1-year total shareholder return of 98.05% points to momentum that has been building over a longer stretch.
See how BlackBerry's renewed guidance compares with other software players showing strong balance sheets and fundamentals in our curated list of solid balance sheet and fundamentals (7 results).
After a move like BlackBerry's, some investors lean into the momentum while others wait for the chart to cool off. Is the current valuation already stretched, or does it still leave a margin of safety for new buyers?
Most Popular Narrative: 18% Undervalued
Against a last close of CA$13.23, the most followed narrative on BlackBerry pegs fair value at CA$16.22, which implies a meaningful gap that focuses attention on how durable its software economics really are, according to artoflosing.
The market is pricing BlackBerry as a maturing automotive software company. What it actually has is the safety infrastructure layer that physical AI cannot be commercially deployed without. The automotive royalty backlog took fifteen years to reach $950M. The physical AI backlog is starting from zero right now, in a faster growing market, with the same royalty model and the same impossibility of removal once embedded.
See why 22 investors see BlackBerry as 18% undervalued.
Result: Fair Value of CA$16.22 (UNDERVALUED)
Still, BlackBerry's story can be knocked off course if physical AI royalties arrive more slowly than expected or if major automakers push harder into in-house safety software.
Find out about the key risks to this BlackBerry narrative.
Another View on BlackBerry's Valuation
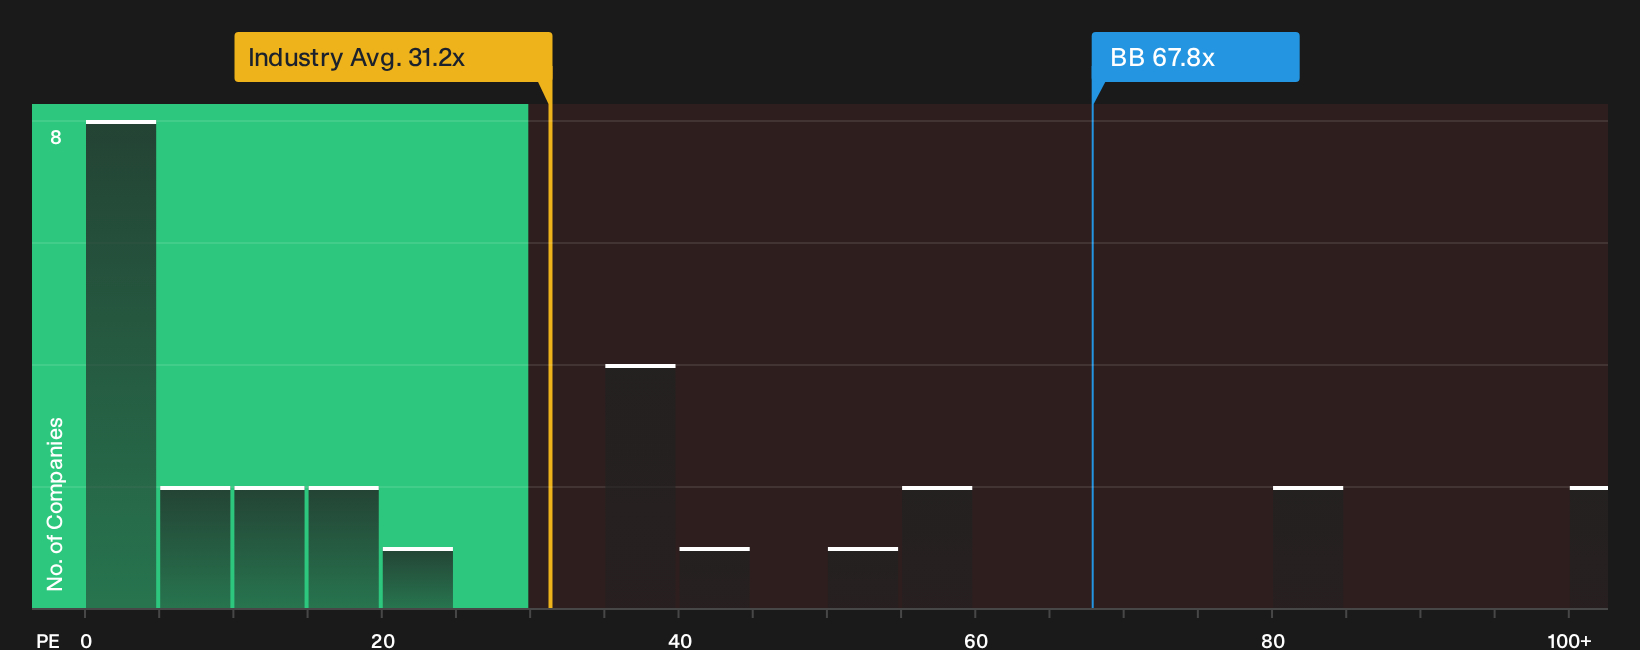
BlackBerry screens as slightly cheap against the SWS fair value, trading at CA$13.23 compared with an estimated fair value of CA$13.56, yet the current P/E of 67.8x is roughly double the 33.1x fair ratio and well above the 31.2x industry average. This raises the question of how much optimism is already in the price.
The gap between the actual P/E and the fair ratio points to meaningful re-rating risk if sentiment cools or earnings do not keep pace. It is therefore worth stress-testing your thesis against our valuation breakdown before deciding how much room for error you really have here See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
The mix of optimism and hesitation around BlackBerry is clear, and that kind of split view is exactly when you benefit most from checking the numbers yourself and moving quickly while sentiment is still unsettled. To weigh the upsides against the pressure points in one place, start with our breakdown of 3 key rewards and 1 important warning sign.
Looking for more BlackBerry sized opportunities?
If you want to keep sharpening your process beyond BlackBerry, do not stop here. The right watchlist today can shape your returns for years.
- Target potential mispricings confidently by scanning a curated pool of companies trading below their assessed worth using the 6 high quality undervalued stocks.
- Build a portfolio that can better handle rough markets by focusing on financially robust businesses through the 8 resilient stocks with low risk scores.
- Get ahead of the crowd by hunting for quality businesses that are still off most radars with the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com