


Why Redcare Pharmacy Raised Its 2026 Revenue Guidance
Redcare Pharmacy (XTRA:RDC) lifted its full-year 2026 total revenue growth guidance to a range of 16% to 18%, up from a prior outlook of 15% to 17%. That shift signals higher internal expectations for the online pharmacy operator’s top line.
At a share price of €70.25, Redcare Pharmacy has seen strong short-term momentum, with a 1-month share price return of 17.97% and a 7-day gain of 3.01%, even though the 1-year total shareholder return is down 19.30%. This points to improving sentiment after a tough stretch.
Scan beyond Redcare Pharmacy and compare this guidance upgrade with other high-growth prospects using our curated list of 187 high quality undervalued stocks.
After that sharp rebound and a higher 2026 revenue bar, the live question on Redcare Pharmacy is simple: Is most of the upside already in the share price, or is the recent move just the opening act for value?
Preferred Price-to-Sales of 0.4x for Redcare Pharmacy: Is It Justified?
Redcare Pharmacy trades on a P/S ratio of 0.4x, which the data flags as expensive relative both to its own fair P/S estimate and to peers, even with the recent share price at €70.25 and a DCF output that suggests a much higher future cash flow value.
The P/S multiple compares the market value of the equity to annual revenue and is often used for loss-making businesses where earnings are still negative. For Redcare Pharmacy, current sales of €3,217.4m sit against a reported net loss of €42.0m, so investors are effectively paying based on turnover while waiting for the forecast profit inflection.
Relative pricing paints a tougher picture. The stock is flagged as expensive versus the estimated fair P/S ratio of 0.2x, and also screens as pricey versus both the European Consumer Retailing average of 0.4x and a peer average of 0.2x. That combination suggests the current 0.4x level could have room to compress if sentiment or growth expectations soften, even though separate DCF work points to a future cash flow value of €348.27 per share.
Explore the SWS fair ratio for Redcare Pharmacy.
Result: Price-to-Sales of 0.4x (OVERVALUED)
Still, weakness in long term shareholder returns and the ongoing net loss of €42.0m could quickly challenge the upbeat pricing story around Redcare Pharmacy.
Find out about the key risks to this Redcare Pharmacy narrative.
Another View On Redcare Pharmacy’s Valuation
The earlier P/S work presents Redcare Pharmacy as expensive on sales, yet the SWS DCF model points in the opposite direction. At €70.25, the stock is described as trading about 79.8% below an estimated future cash flow value of €348.27. On that basis, it appears heavily undervalued.
That kind of gap suggests either the DCF inputs are too optimistic or the market is heavily discounting the path to the forecast profit recovery. The question for you is simple: which side of that disconnect feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
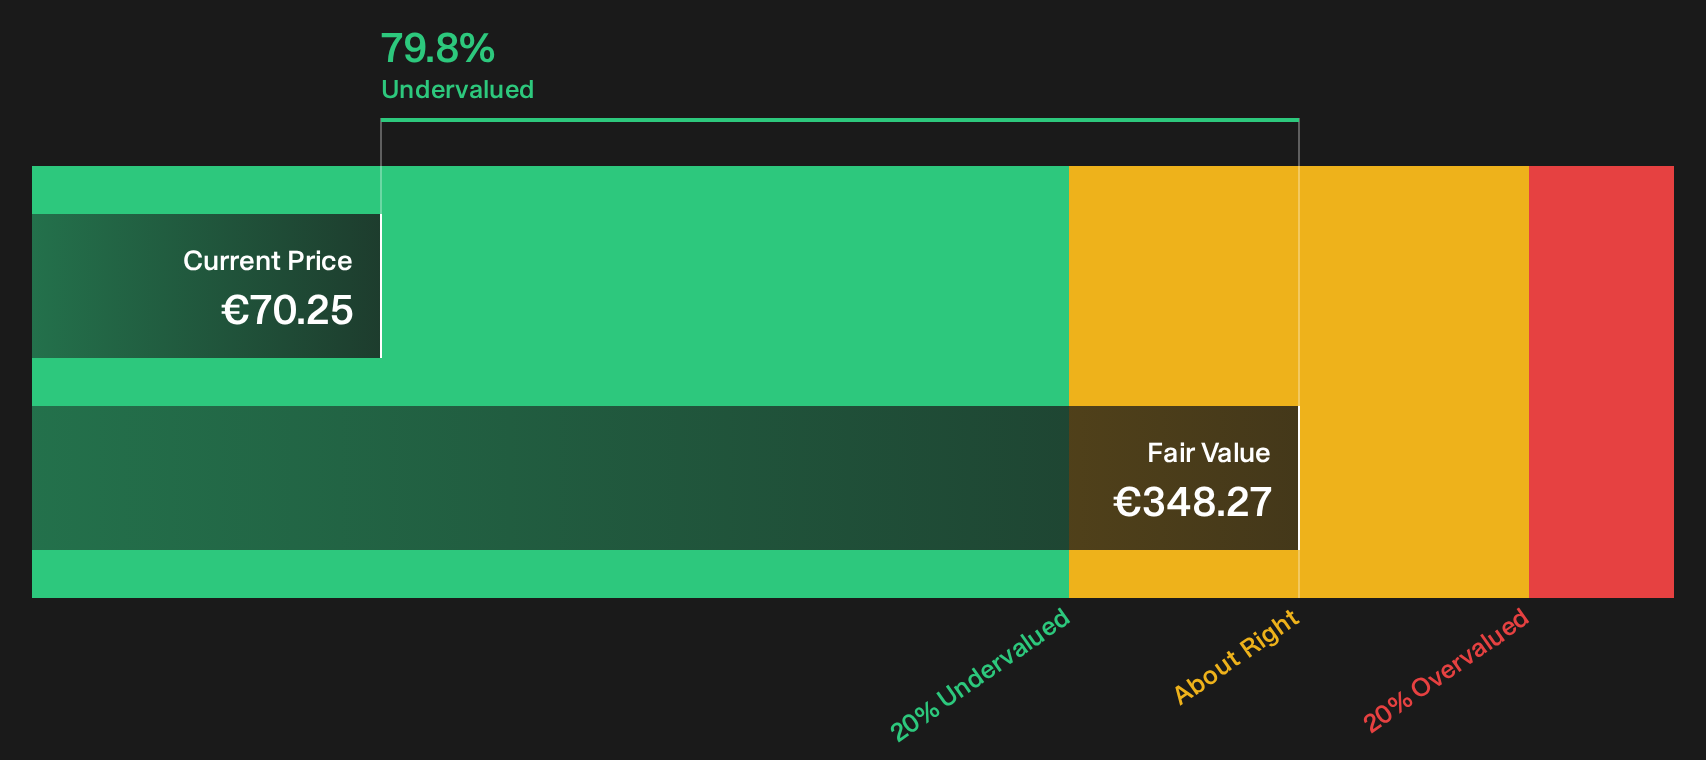
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Redcare Pharmacy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 187 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like this rarely stay unresolved for long. Treat this as your cue to review the numbers directly and reach your own judgement using the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Redcare Pharmacy?
If Redcare Pharmacy has sharpened your focus on pricing and growth, do not stop here. Fresh opportunities rarely wait around for investors who stay on the sidelines.
- Target resilient cash generators by scanning companies with strong financial footing using the list of solid balance sheet and fundamentals (207 results).
- Hunt for potential mispricings by reviewing companies that combine quality fundamentals with attractive pricing through the 187 high quality undervalued stocks.
- Zero in on income-focused ideas by checking out higher yielding opportunities in the 163 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com