


Executive change puts CTS Eventim KGaA in focus
CTS Eventim KGaA (XTRA:EVD) drew investor attention after announcing that long serving finance chief Dr. William Willms stepped down on 30 September 2026, and that Dr. Philipp Knigge assumed interim CFO responsibilities.
For context, CTS Eventim KGaA shares closed at €55.45, with a 1-day share price return of 3.55% but a year-to-date share price decline of 28.73%, while the 1-year total shareholder return is down 31.03% and the 3-year total shareholder return is up 5.20%, pointing to pressure in the recent trend after a modestly positive longer record.
Compare how CTS Eventim KGaA’s recent share price pressure and CFO transition stack up against other hand picked businesses by scanning the 615 high quality undiscovered gems for potential alternatives in similar situations.
After a sharp year to date slide but a positive reaction to the CFO change, CTS Eventim KGaA now faces a simple timing question. Is this the moment to commit fresh capital, or does patience offer a better entry point as the valuation picture unfolds next?
Most Popular Narrative: 37% Undervalued
On the most followed narrative, CTS Eventim KGaA screens as undervalued, with a fair value of €88.63 versus the €55.45 close, which puts the focus firmly on how future execution might bridge that gap.
The company continues to see accelerating growth outside its core German market, with international ticketing revenues up 56% year-on-year, reflecting global expansion into higher-growth regions and underpinned by rising consumer spending on live entertainment, which supports strong future revenue growth.
Ongoing digital transformation projects, which include unifying platforms and leveraging proprietary technology across new markets, are set to improve operating leverage, reduce costs, and enhance upselling/cross-selling opportunities, which should positively impact both top-line revenue and margin profile.
See why 9 investors see CTS Eventim KGaA as 37% undervalued.
Result: Fair Value of €88.63 (UNDERVALUED)
Still, the CTS Eventim KGaA story can break if integration costs at recent acquisitions stay elevated, or if oversupply in smaller festivals keeps Live Entertainment profitability under strain.
Find out about the key risks to this CTS Eventim KGaA narrative.
Another view on CTS Eventim KGaA valuation
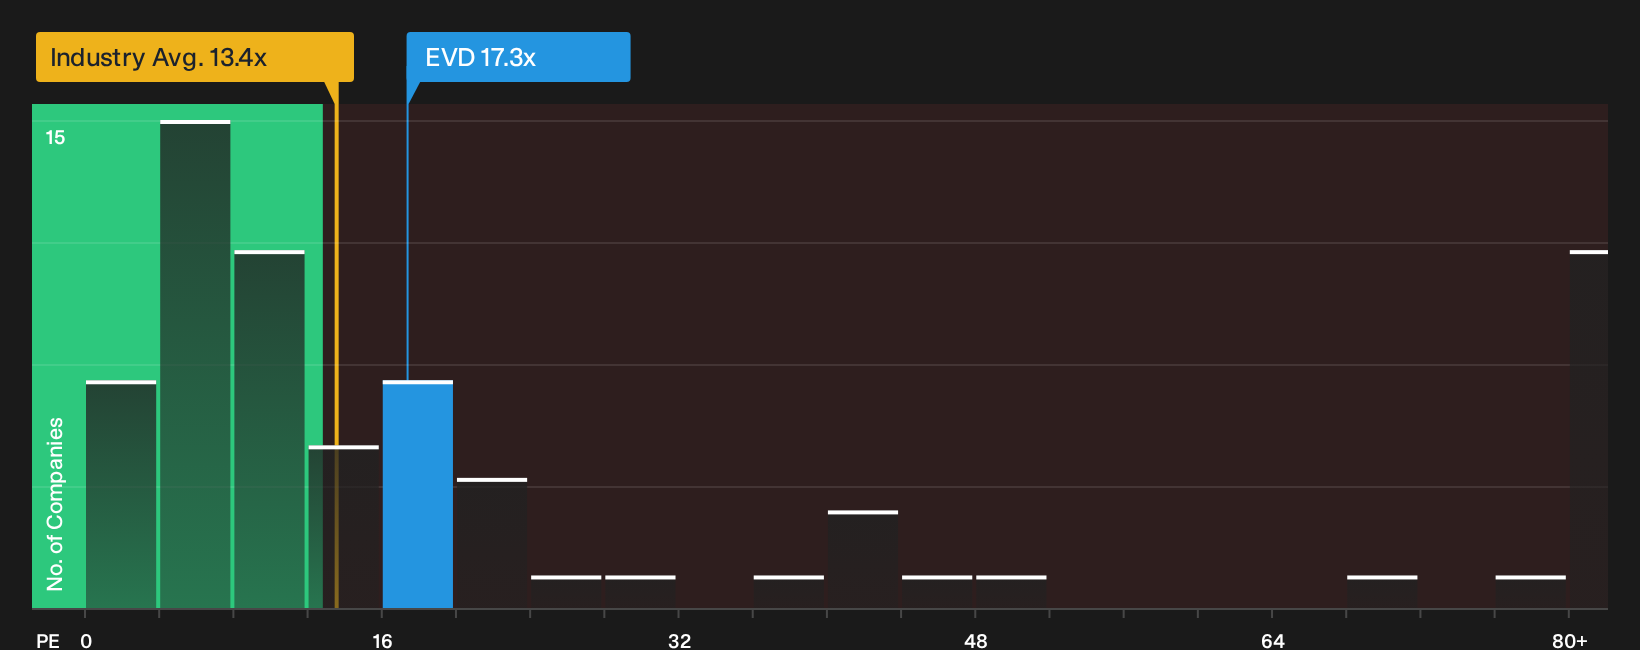
That 37% discount to fair value leans heavily on analyst forecasts and a discounted cash flow view. From a simpler perspective, CTS Eventim KGaA trades on a P/E of 17.3x, which is higher than the European Entertainment average of 13.4x, yet below its own fair ratio of 18.6x.
This mix of slight value support versus peers, but a premium to the wider industry, raises a practical question. Is the current price compensating you enough for execution risks around integration, live events volatility and management change, or is the margin of safety thinner than the headline discount suggests?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed messages on CTS Eventim KGaA so far and plenty for you to weigh up. If you want to see both sides clearly, review the 3 key rewards and 1 important warning sign.
Looking for more CTS Eventim KGaA style investment ideas?
Do not stop your research with CTS Eventim KGaA. Broadening your watchlist with other clear, data led ideas can sharpen your next investing move.
- Target potential mispricings by scanning the 187 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Focus on resilience by filtering for a list of solid balance sheet and fundamentals (207 results) that can better withstand shocks and funding pressures.
- Hunt for early stage potential by reviewing the 113 elite penny stocks with strong financials that pair smaller market caps with stronger financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com