


With a market cap of $12.3 billion, Ireland-based Allegion plc (ALLE) is a global security and access solutions company that designs and manufactures products that protect people, buildings, and assets. Its portfolio spans mechanical and electronic locks, access-control systems, door closers, exit devices, doors and frames, and security software and services. Its major brands include Schlage, CISA, Von Duprin, LCN, SimonsVoss, and Interflex.
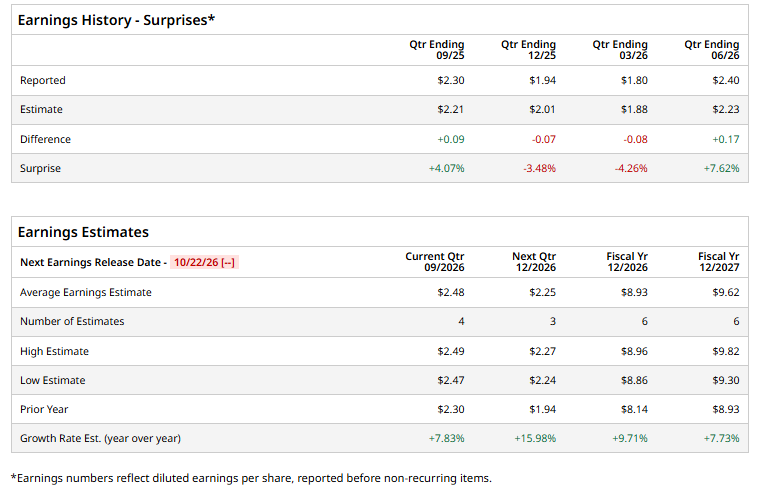
The company is expected to release its fiscal Q3 2026 results soon. Ahead of this event, analysts project Allegion to report an adjusted EPS of $2.48, a 7.8% rise from $2.30 in the year-ago quarter. It has exceeded Wall Street's bottom-line estimates in two of the last four quarters while missing on two other occasions.
For fiscal 2026, analysts forecast the security device maker to report adjusted EPS of $8.93, up 9.7% from $8.14 in fiscal 2025.
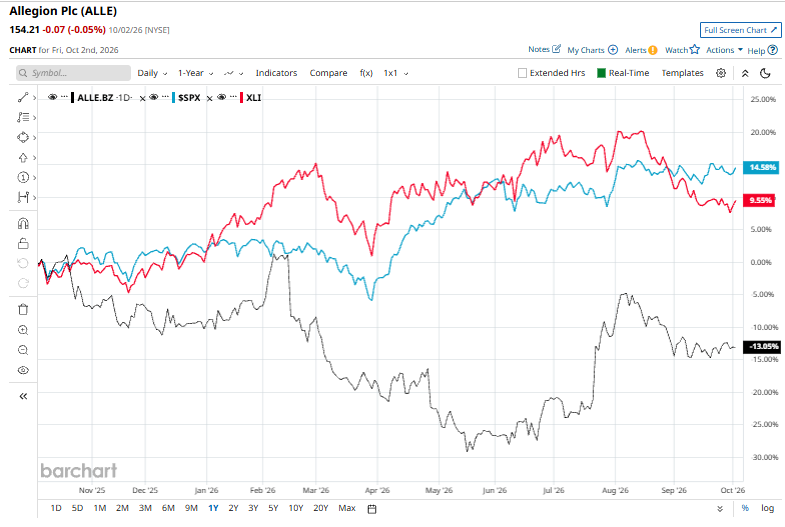
Over the past 52 weeks, Allegion has declined 13.2%, underperforming the broader S&P 500 Index's ($SPX) 15% return and the State Street Industrial Select Sector SPDR ETF's (XLI) 10.2% gain over the same period.
On Sept. 2, ALLE shares popped 2.1% after the company declared a quarterly dividend of $0.55 per ordinary share, maintaining the company’s quarterly payout at the same level as the previous quarter. The dividend was payable on Sept. 30 to shareholders of record as of Sept. 15. The declaration highlights Allegion’s continued commitment to returning capital to shareholders, supported by its recurring cash generation and established position in the security and access-solutions market. With four quarterly payments of $0.55, the current annualized dividend stands at $2.20 per share.
Analysts' consensus view on Allegion stock is cautiously optimistic, with a "Moderate Buy" rating overall. Among 12 analysts covering the stock, four suggest a "Strong Buy," and eight give a "Hold." The average analyst price target is $169.75, indicating a potential upside of 10.1% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.