


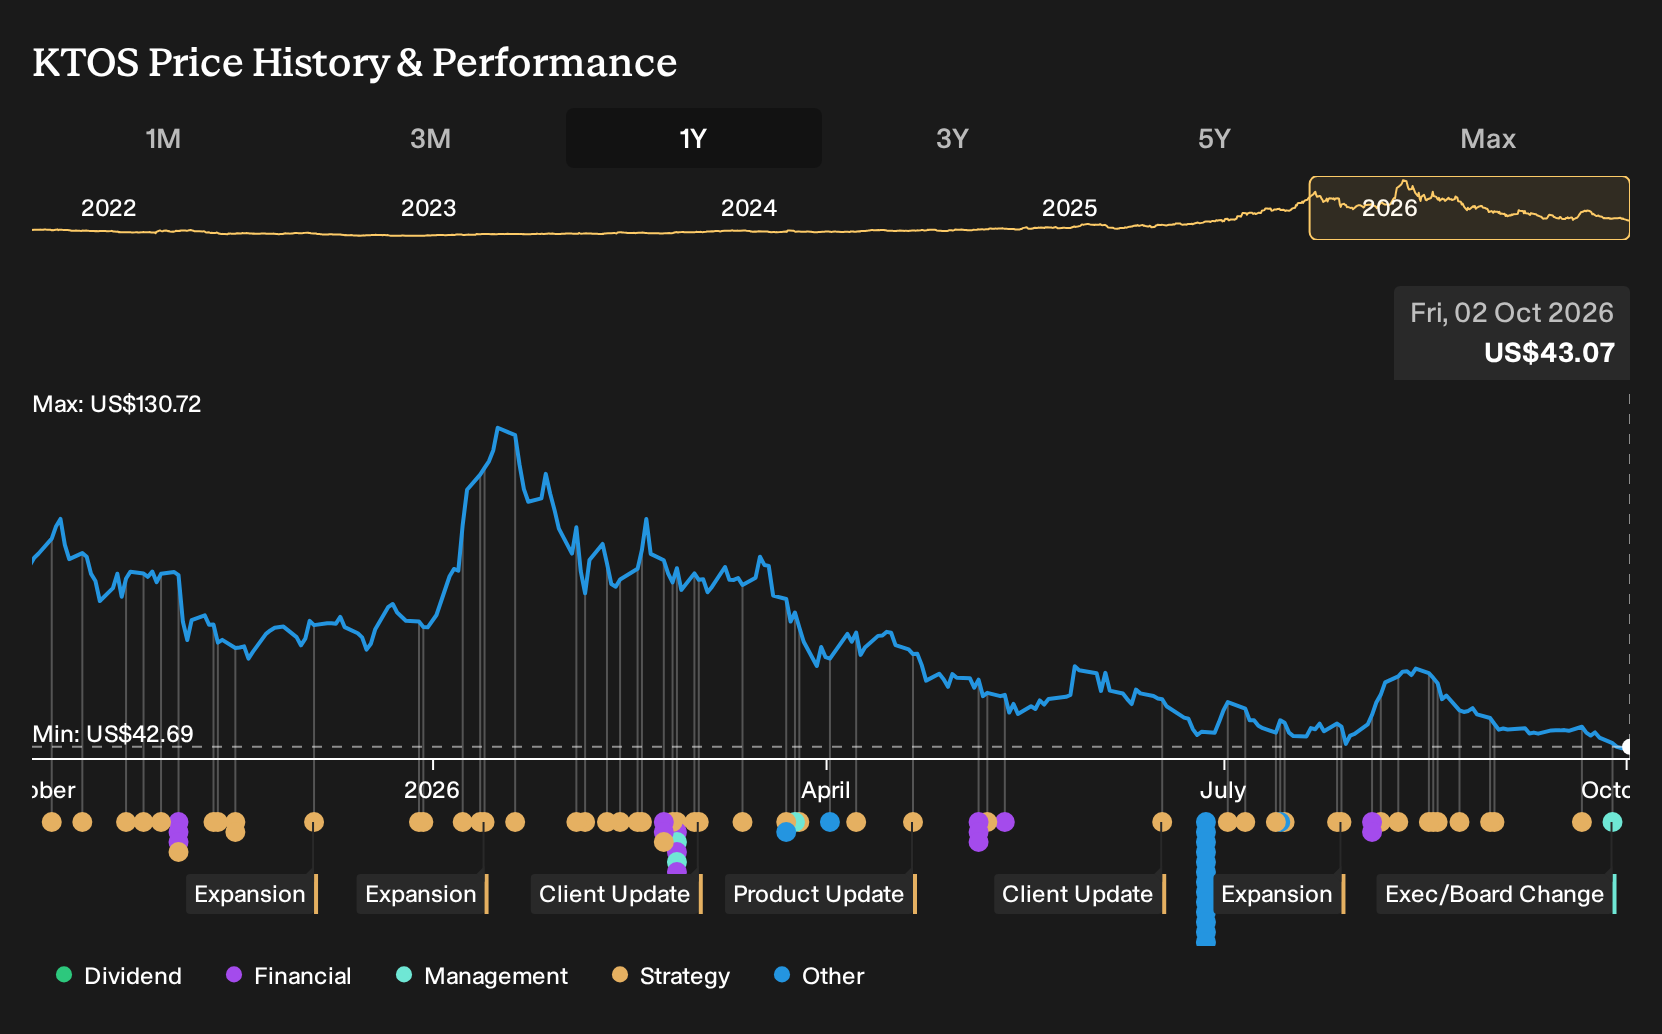
- Kratos Defense & Security Solutions reported a successful ignition test of the GEK800 turbofan, now designated F143, developed with GE Aerospace for long range cruise missile applications, and also appointed long time executive Bill Wilson as President of its C5ISR Systems Division.
- The GEK800 milestone signals execution progress on an affordable, high performance propulsion program that targets demand for rapid, attritable strike capability, while Wilson’s promotion concentrates deep financial and operational experience in a division central to Kratos’ mil spec hardware and mobility systems work.
- We will now look at how Kratos Defense & Security Solutions' F143 propulsion milestone could reshape the longer term investment narrative.
Scan how Kratos Defense & Security Solutions compares with other contractors building for the next wave of high performance defense hardware in our hand picked 90 AI infrastructure stocks.
Kratos Defense & Security Solutions Investment Narrative Recap
For a shareholder in Kratos Defense & Security Solutions, the core belief is that heavy spending on unmanned systems, missile engines and specialized C5ISR hardware eventually turns into steadier earnings and better cash generation. In the near term, a key swing factor is how quickly awarded programs move into volume production instead of being delayed and keeping free cash flow under pressure.
The biggest risk is still the mismatch between upfront investment and the timing of government orders. The new F143 engine milestone and Bill Wilson’s promotion support execution credibility, but they do not remove exposure to contract delays, supplier bottlenecks or uneven cash conversion over the next few years.
The F143 propulsion milestone is the clearest operational proof point linked to the current story. It ties directly to the GEK missile engine program that analysts already identify as a key contributor to potential future revenue growth. Successful ignition on schedule supports the view that Kratos Defense & Security Solutions can move complex hardware from development into scalable production lines.
For you, the question is whether that technical progress arrives quickly enough to offset near term strains from capital expenditures, working capital and dependence on a few critical suppliers. If F143 moves into volume builds on time, it can help absorb fixed costs, ease margin pressure and partially balance the risk that other unmanned or hypersonic programs ramp more slowly.
What The F143 Milestone Means For Kratos Defense & Security Solutions' Forecasts
Forward looking models that already incorporate programs like GEK and F143 point to a steep ramp for Kratos Defense & Security Solutions if things stay on track. Analysts are working with revenue growth assumptions of 24.7% a year over the next three years and a move in profit margins from 2.0% today to 6.4% in that same window. This sets a high bar for execution across unmanned systems, propulsion and C5ISR hardware.
The earnings bridge that underpins this view is even more demanding. Consensus expects profit to reach US$188.7 million by 2029 compared with US$30.9 million today. This implies earnings would need to grow by roughly 6x off the current base even before factoring in that analysts see shares outstanding climbing 7.0% per year. For investors, the basic story is not just about winning contracts but about turning those wins into materially higher net income on a much larger equity base.
On these assumptions, the future valuation math also stretches traditional sector yardsticks. To align with the analyst narrative, Kratos Defense & Security Solutions would need to generate about US$3.0b in annual revenue and US$188.7 million in profit by 2029 while trading on a P/E multiple of 156.7x, compared with a current P/E of 259.3x and a sector level closer to 35.3x. That kind of multiple still embeds a strong belief in long term earnings power even after some compression from today’s level.
Kratos Defense & Security Solutions' narrative projects US$3.0b revenue and US$188.7 million earnings by 2029. This implies 24.7% yearly revenue growth and an earnings increase of roughly 6x from US$30.9 million today.
Uncover how Kratos Defense & Security Solutions' fair value indicates a 137% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on cash strain rather than the F143 or Bill Wilson’s promotion. The most cautious analysts were modeling only 20.2% yearly revenue growth and about US$115.0 million in earnings by 2029, which is well below consensus. This highlights how far opinions on Kratos Defense & Security Solutions can differ and why you may want to compare several pre news scenarios yourself.
Explore 6 other Kratos Defense & Security Solutions fair value estimates, including one that suggests it could be worth just $43.27.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kratos Defense & Security Solutions research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kratos Defense & Security Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kratos Defense & Security Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kratos Defense & Security Solutions?
If the Kratos Defense & Security Solutions story has you thinking about where to look next, a broader watchlist can help you spot other opportunities with different risk and return profiles.
- For investors who want potential mispricing combined with quality fundamentals, start by scanning our 31 high quality undervalued stocks that may warrant a closer look on your watchlist.
- If resilience is your priority and you care about balance sheet strength, consider screening for companies in the list of solid balance sheet and fundamentals (25 results) to compare alongside Kratos Defense & Security Solutions.
- For those hunting for future standouts earlier in their journey, review the 19 high quality undiscovered gems and see which profiles fit your own investment playbook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com