


Readers hoping to buy Ennis, Inc. (NYSE:EBF) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. The ex-dividend date is one business day before the record date, which is the cut-off date for shareholders to be present on the company's books to be eligible for a dividend payment. The ex-dividend date is important as the process of settlement involves a full business day. So if you miss that date, you would not show up on the company's books on the record date. In other words, investors can purchase Ennis' shares before the 9th of October in order to be eligible for the dividend, which will be paid on the 6th of November.
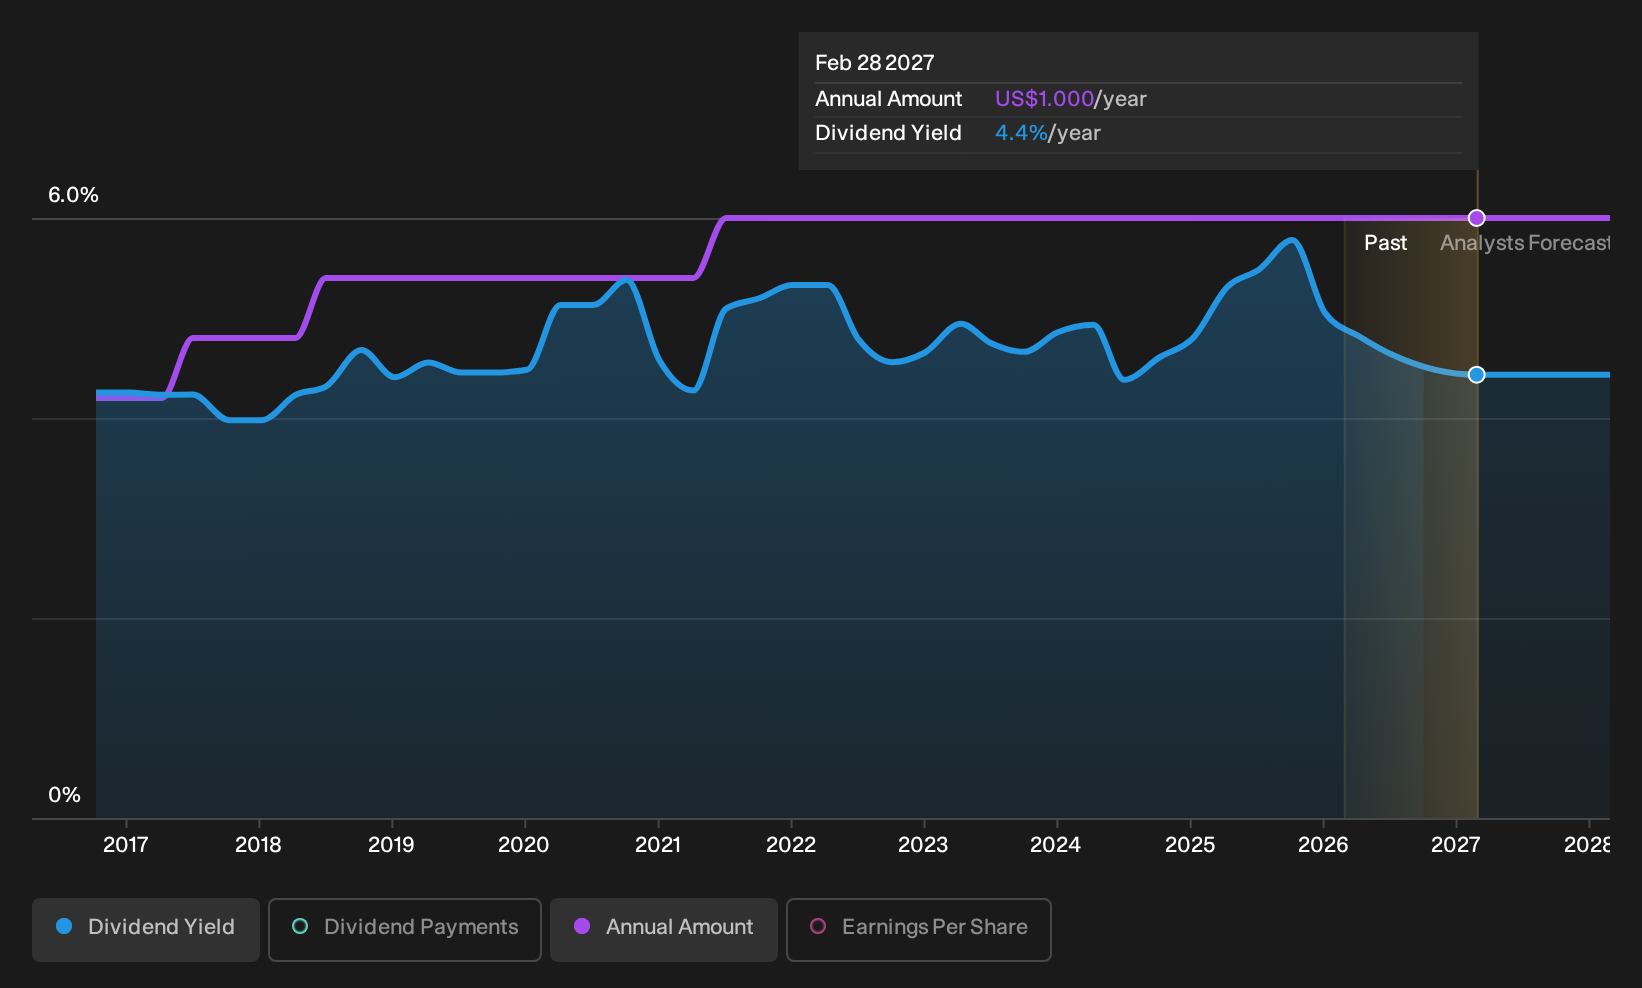
The company's next dividend payment will be US$0.2625 per share, on the back of last year when the company paid a total of US$1.05 to shareholders. Calculating the last year's worth of payments shows that Ennis has a trailing yield of 4.7% on the current share price of US$22.56. If you buy this business for its dividend, you should have an idea of whether Ennis's dividend is reliable and sustainable. So we need to investigate whether Ennis can afford its dividend, and if the dividend could grow.
Dividends are typically paid out of company income, so if a company pays out more than it earned, its dividend is usually at a higher risk of being cut. Ennis is paying out an acceptable 66% of its profit, a common payout level among most companies. Yet cash flows are even more important than profits for assessing a dividend, so we need to see if the company generated enough cash to pay its distribution. Thankfully its dividend payments took up just 46% of the free cash flow it generated, which is a comfortable payout ratio.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
See our latest analysis for Ennis
Click here to see how much of its profit Ennis paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Stocks in companies that generate sustainable earnings growth often make the best dividend prospects, as it is easier to lift the dividend when earnings are rising. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. For this reason, we're glad to see Ennis's earnings per share have risen 11% per annum over the last five years. Ennis is paying out a bit over half its earnings, which suggests the company is striking a balance between reinvesting in growth, and paying dividends. Given the quick rate of earnings per share growth and current level of payout, there may be a chance of further dividend increases in the future.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the past 10 years, Ennis has increased its dividend at approximately 4.1% a year on average. Earnings per share have been growing much quicker than dividends, potentially because Ennis is keeping back more of its profits to grow the business.
Final Takeaway
Is Ennis an attractive dividend stock, or better left on the shelf? We like Ennis's growing earnings per share and the fact that - while its payout ratio is around average - it paid out a lower percentage of its cash flow. Overall we think this is an attractive combination and worthy of further research.
Want to learn more about Ennis's dividend performance? Check out this visualisation of its historical revenue and earnings growth.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.