


Bond markets are back in the driver’s seat, with climbing government yields, louder talk of spending cuts, and European election noise all tugging on equity valuations at once. That mix is punishing some stocks and rewarding others that investors see as steadier cash generators. This article walks through three large cap value and high dividend stocks exposed to these forces and explains how each might fit, or not, in a yield obsessed market.
The stocks covered below are only a first pass, and the full screen surfaced 14 more large cap value and high dividend companies with equally compelling stories that are not profiled in this article. To identify and analyze your own highest conviction ideas around balance sheet strength, income potential, and pricing, head straight to the Global Large-Cap Value and High-Dividend Stocks screener.
A2A (BIT:A2A)
A2A is a large Italian utility that fits the screener’s focus on sizeable, income oriented European stocks, with a mix of regulated energy, district heating and circular economy assets that can appeal to investors watching bond yields and looking for relatively steady cash generation.
A2A generates most of its revenue from Generation and Trading at about €10.4b, with additional contributions from the Circular Economy segment at roughly €2.3b, Smart Infrastructures at around €1.2b, and other market and corporate activities, and the group carries a market value of roughly €7.0b.
"A2A's accelerated investment in electricity grids and smart infrastructure, following large-scale integration of Enel's assets and rapid CapEx deployment, positions it for outsized gains from the ongoing electrification of cities and sectors (including rising baseline electricity demand in urban areas and transport); this bolsters both revenue growth and regulated EBITDA margins in future years."
What really matters now is how one quiet pressure on A2A’s funding costs shapes the trade off between income today and future margin resilience.
That funding squeeze is exactly what the full narrative for A2A unpacks, showing how A2A’s grid push, regulation and payouts could be pulling in different directions.

Vinci (ENXTPA:DG)
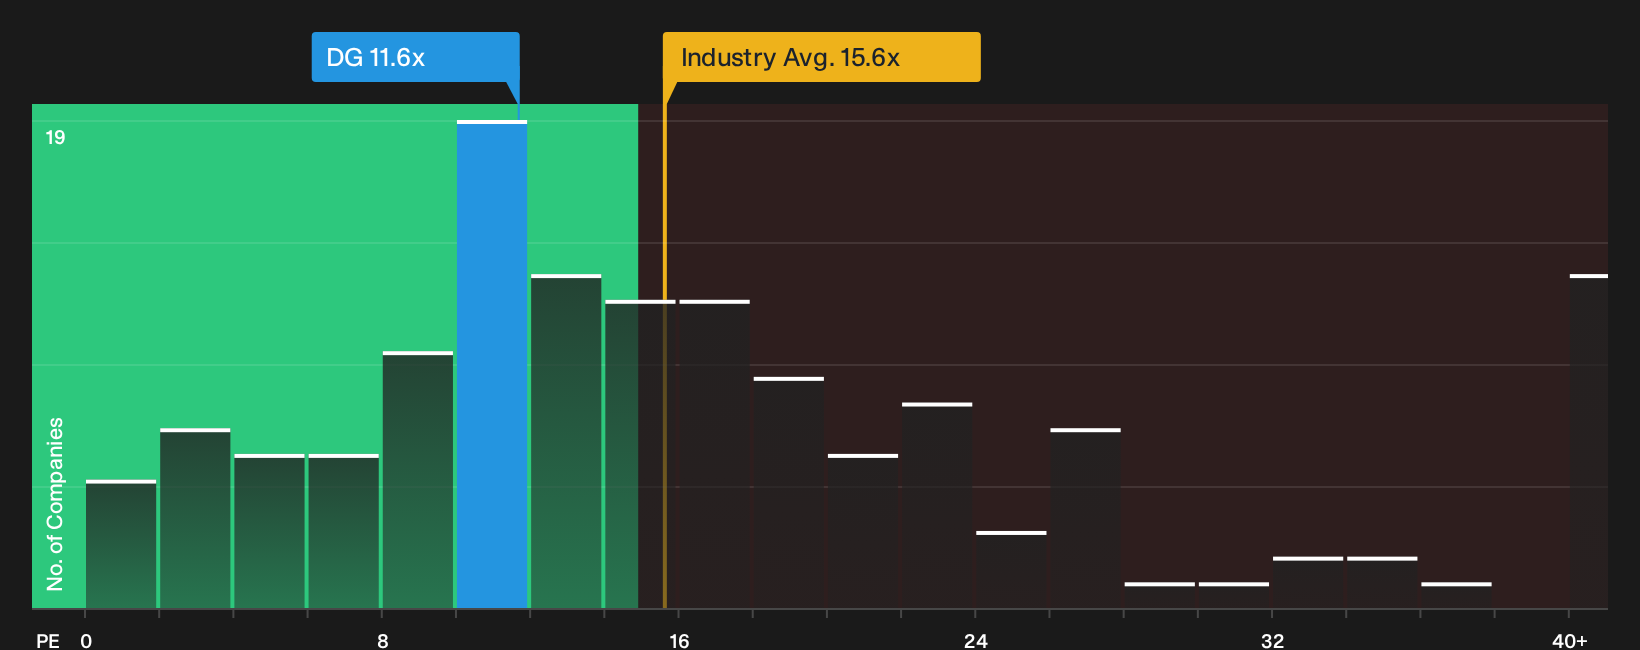
Vinci fits the Global Large-Cap Value and High-Dividend Stocks theme as a €59.2b French infrastructure group. It combines motorway and airport concessions with large energy services operations and construction activities, where Energy Solutions and Construction generate the bulk of revenue in the tens of billions of euros.
For income focused investors watching bond yields, Vinci matters because it blends long-dated infrastructure concessions with an established dividend profile and a value style P/E. This creates a different type of ballast compared with pure utilities or banks.
"Vinci operates with solid margins above 10%, with good capital allocation given its ROIC higher than the estimated cost of capital."
What could really move the story now is how one unresolved pressure on financing costs interacts with those long concession contracts and future payout choices.
Those financing pressures are exactly what the full narrative for Vinci unpacks, revealing how Vinci’s concessions, cash returns and balance sheet could be quietly decoupling from headline bond moves.
Omega Healthcare Investors (OHI)
Omega Healthcare Investors brings the Global Large-Cap Value and High-Dividend Stocks theme into the long term care real estate world, with a REIT structure that focuses on skilled nursing and assisted living cash flows rather than rapid capital gains.
Omega Healthcare Investors is a US based REIT that owns skilled nursing and assisted living facilities across the US, UK and Canada, fitting the screener’s tilt toward large, income focused businesses. It generates about US$1.3b from investments in healthcare related real estate properties and has a market value of roughly US$14.5b.
Income oriented readers watching bond yields often look at Omega Healthcare Investors as a way to tap into aging demographics through property backed rent streams, which fits cleanly with a value leaning, dividend heavy portfolio tilt.
"Ongoing aging of the baby boomer population, together with limited new skilled nursing facility construction in many states, is expected to keep demand firm for Omega Healthcare Investors’ properties and support occupancy and rent coverage."
What investors really need to watch now is how one quiet constraint on future cash generation shapes the balance between today’s payout and tomorrow’s resilience.
That trade off is exactly what the full narrative for Omega Healthcare Investors unpacks, showing how aging demand, rent coverage trends and balance sheet choices could be quietly reshaping Omega Healthcare Investors’ yield story.

Seeking Alternatives Before The Crowd
Fresh ideas often move first. Breakout themes, quiet momentum, and quality stocks can get caught once attention floods in. Scan what is still under the radar for now and consider acting before it becomes crowded.
- Look for resilient balance sheets before they start gaining broad attention by scanning the curated list of solid balance sheet and fundamentals (207 results) that filters for quality fundamentals while it still matters.
- Identify income-focused candidates while yields remain compelling by reviewing the hand picked 164 dividend fortresses built for investors who want payouts backed by real cash flows.
- Follow potential upgrade cycles early by scanning the focused 90 AI infrastructure stocks that highlights key suppliers to AI-related demand before interest becomes widespread.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com