


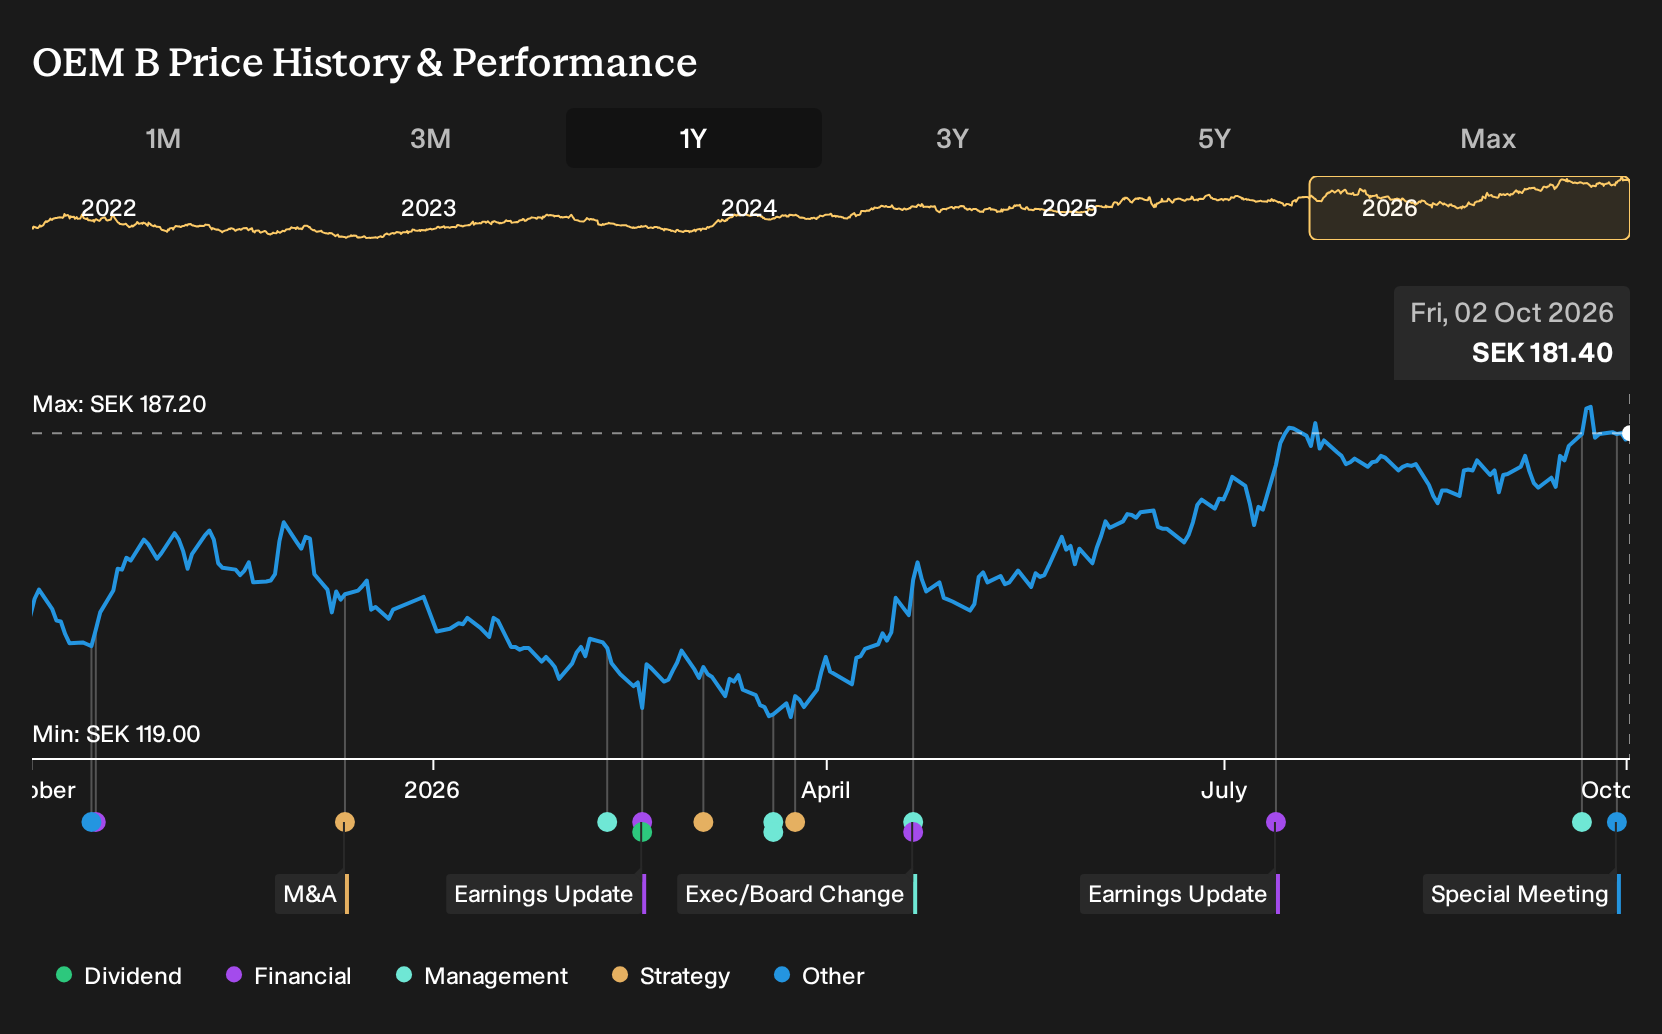
- OEM International announced that Chair of the Board Christopher Norbye informed the Board in September 2026 that he intends to step down, with an Extraordinary General Meeting planned for mid October 2026 and his tenure continuing until that meeting.
- This leadership transition concentrates attention on OEM International's governance continuity, including how the Board refresh process, Chair succession planning and oversight approach might influence execution on operational priorities.
- We will now examine how OEM International's investment narrative could be influenced by the planned departure of its long serving Board Chair.
Compare how OEM International’s leadership transition stacks up against other businesses going through governance change by scanning our hand-picked 226 resilient stocks with low risk scores for potential alternatives with steadier profiles.
What Is OEM International's Investment Narrative?
To own OEM International, you need to be comfortable with a fairly straightforward story. This is a technology trading group that lives or dies on execution in distribution, consistent industrial demand and the ability to price its automation components sensibly against competitors. Recent figures show SEK 5,639.4m in revenue and SEK 667.7m in net income, together with high return on equity at 22.5% and profit margins of 11.8%. That combination points to a business model that currently converts sales into earnings efficiently, even if revenue and earnings forecasts are described as growing but not significantly.
The bigger question is whether the machinery keeps running smoothly as governance evolves. Earnings are forecast to grow 10.3% per year, faster than the wider Swedish market, and analysts see only a modest gap between the current SEK 181.4 share price and their SEK 198.33 target. That hints that the Chair’s planned exit may not change near term demand, pricing power or capital intensity in a visible way, especially with an already independent board. Where it might bite is around a relatively new board and management team being asked to keep delivering at a P/E of 37.7x in a funding mix that relies entirely on external borrowing.
Yet alongside that seemingly solid setup sits one awkward issue that keeps popping up in the numbers and boardroom data that ...
There's only one way to know the right time to buy, sell or hold OEM International. Head to Simply Wall St's company report for the latest analysis of OEM International's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight SEK 188.10 to SEK 198.33 band, so retail views on OEM International sit close to the current market price. These opinions were formed before the Chair’s planned exit in October 2026, so use them as a starting point and cross check against newer board and governance updates.
Explore another OEM International fair value estimate, including one that suggests up to 9% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OEM International research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for OEM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OEM International's overall financial health at a glance.
Looking For More Investment Ideas Beyond OEM International?
Once you have an informed view on OEM International, it can help to widen the lens and compare it with other businesses that fit different risk, income and value profiles. The Simply Wall St Screener gives you curated sets of stocks so you can pressure test your thesis against a broader watchlist.
- If capital protection is front of mind, consider reviewing a curated 226 resilient stocks with low risk scores that may appeal if you prefer steadier volatility profiles and more conservative balance sheets.
- Income focused investors can scan a focused 163 dividend fortresses if you want to see which companies currently pair higher yields with consistency in shareholder payouts.
- For those hunting for potential mispricing, you can search through a targeted 187 high quality undervalued stocks that may help surface candidates to research alongside OEM International.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com