


- Qiagen reported that U.S. labs now have access to the full QIAstat-Dx bloodstream infection portfolio after FDA clearance of the BCID GN Plus AMR Panel, which delivers approximately one-hour detection of 13 gram-negative pathogens and 18 resistance markers, alongside the existing gram-positive and fungal panel.
- The firm also introduced QIAmini, a compact research-use-only sample preparation instrument aimed at small-batch academic and research labs, targeting an estimated market of more than 100,000 potential placements and extending Qiagen’s push into connected automation alongside QIAsprint Connect and QIAsymphony Connect.
- This development provides a basis to examine how Qiagen’s investment narrative around automation and infectious disease menus is influenced by broader QIAstat-Dx coverage.
Scan other lab automation and diagnostics stocks that could be building similar momentum to Qiagen with our curated list of list of solid balance sheet and fundamentals (25 results).
Qiagen Investment Narrative Recap
Qiagen may appeal if you think its mix of QIAstat Dx syndromic testing, automation and higher value consumables can offset pressure in more cyclical areas like research funding and QuantiFERON immigration testing. The big short term swing factor remains how quickly newer platforms convert into recurring test usage, especially as revenue growth expectations sit in the mid single digit range.
The bloodstream infection portfolio news expands the infectious disease menu but does not radically change the near term story on its own. Key risks still center on soft capital budgets and delayed upgrades, which could slow margin progress if labs keep legacy systems in place for longer than anticipated.
The most relevant update is the FDA cleared QIAstat Dx BCID GN Plus AMR Panel. Together with the earlier gram positive and fungal panel, this lifts coverage to 33 pathogens and 28 resistance markers with about one hour turnaround. That supports the idea that QIAstat Dx can function as a broader infectious disease workhorse rather than a narrow menu system.
For catalysts, attention may focus on whether this broader bloodstream and meningitis, respiratory and gastrointestinal menu encourages hospitals to add instruments or increase test volumes on existing ones. Execution risk lies in training, workflow integration and competing platforms, so actual pull through on consumables will likely matter more than the headline of menu expansion itself.
What The Current Qiagen Forecasts Assume
Qiagen's narrative projects US$2.5b in revenue and US$563.2m in earnings by 2029. This lines up with analyst assumptions of 6.0% yearly revenue growth and an earnings increase of about US$153.9m from US$409.3m today.
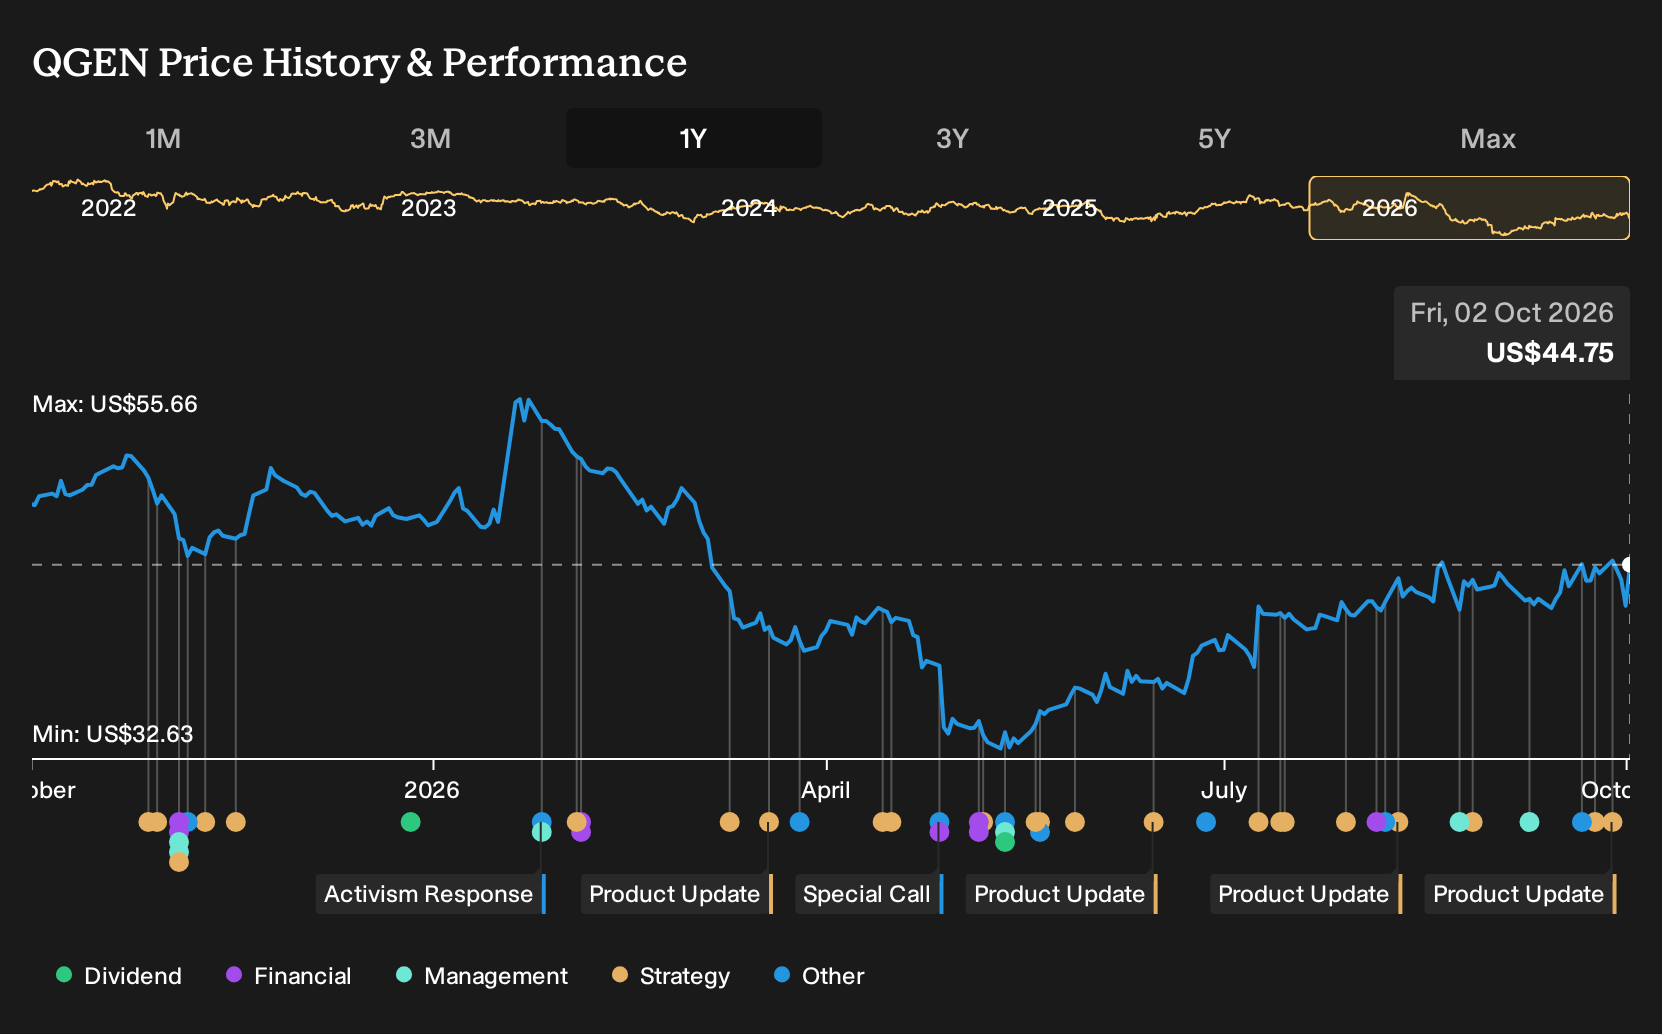
Uncover why Qiagen's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One contrasting angle around Qiagen is QIAstat-Dx utilization. The most cautious analysts worry that hospital budgets and tough respiratory testing comparisons could keep panel use subdued. They were only pencilling in roughly 4.6% annual revenue growth and about US$2.4b of sales by 2029 before this news. Your view on whether the expanded bloodstream menu shifts that story can reasonably differ a lot from theirs. It therefore helps to explore several of these pre news scenarios before deciding how meaningful this launch could become.
Explore 4 other Qiagen fair value estimates, including one that indicates as much as 10% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Qiagen?
If the Qiagen story has you thinking about portfolio gaps, it can help to line it up against other companies with different strengths. The Simply Wall St Screener lets you filter for traits that match your priorities, whether that is resilience, income, or underappreciated quality.
- For investors who want steadier profiles and lower perceived risk, scan a curated group of 31 resilient stocks with low risk scores that may better fit a capital-preservation mindset.
- If the focus is on strong finances and durable balance sheets, compare Qiagen with a wider list of solid balance sheet and fundamentals (25 results) that share similar financial discipline.
- Those hunting for underfollowed quality stories can review a 19 high quality undiscovered gems that combine robust fundamentals with less attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com