


Why Evercore’s New Frankfurt Hire Matters For Investors
Evercore (EVR) just added Philip von Malsen-Plessen as a senior managing director in its investment banking unit, placing him in Frankfurt to focus on the DACH region.
He arrives from UBS after nearly three decades in European corporate finance, which gives Evercore deeper local relationships and sector knowledge. For shareholders, this kind of senior hire raises fresh questions about how the European advisory franchise could influence longer term earnings power and the current share price profile.
Evercore’s share price has retreated sharply despite this senior hire and its upcoming Evercore ISI Storage Symposium in New York, with a 30-day share price return down 12.16% and year to date down 25.50%, even as the 3-year total shareholder return is up 102.71%. This signals longer term momentum that contrasts with recent weakness and sets the backdrop for how investors may frame today’s $261.68 level.
Scan Evercore’s peers and explore how other advisory-focused financials are setting up for their next move with our curated list of 19 high quality undiscovered gems.
Evercore shares have slipped while revenue and net income still show positive annual growth. This leaves a simple tension: has most of the easy upside already played out, or is the market underpricing what investors are getting at $261.68?
Most Popular Narrative: 28% Undervalued
Evercore’s most followed valuation story points to a fair value of $363.90 against the recent $261.68 close, so the current share price sits well below what that framework suggests the business could be worth.
The increasing role of non-M&A areas such as Private Capital Advisory, Private Funds Group, restructuring and liability management, ECM, equities and wealth management, which together provided more than 40% of revenues over the last 12 months, gives Evercore more ways to monetize client activity and can smooth revenue and earnings across deal cycles.
The build-out of Evercore’s European advisory franchise through the integration of Robey Warshaw, new offices in markets such as Stockholm and Paris, and additional senior hires in Frankfurt and London is already feeding into record EMEA revenue periods and positions the firm to capture a larger share of fees from cross border and European large-cap mandates, supporting advisory revenue and operating leverage.
See why 19 investors see Evercore as 28% undervalued.
Result: Fair Value of $363.90 (UNDERVALUED)
Still, the Evercore story can break if non-compensation expenses stay elevated, or if recent hiring leaves compensation ratios high while fee activity cools.
Find out about the key risks to this Evercore narrative.
Another View On Evercore’s Valuation
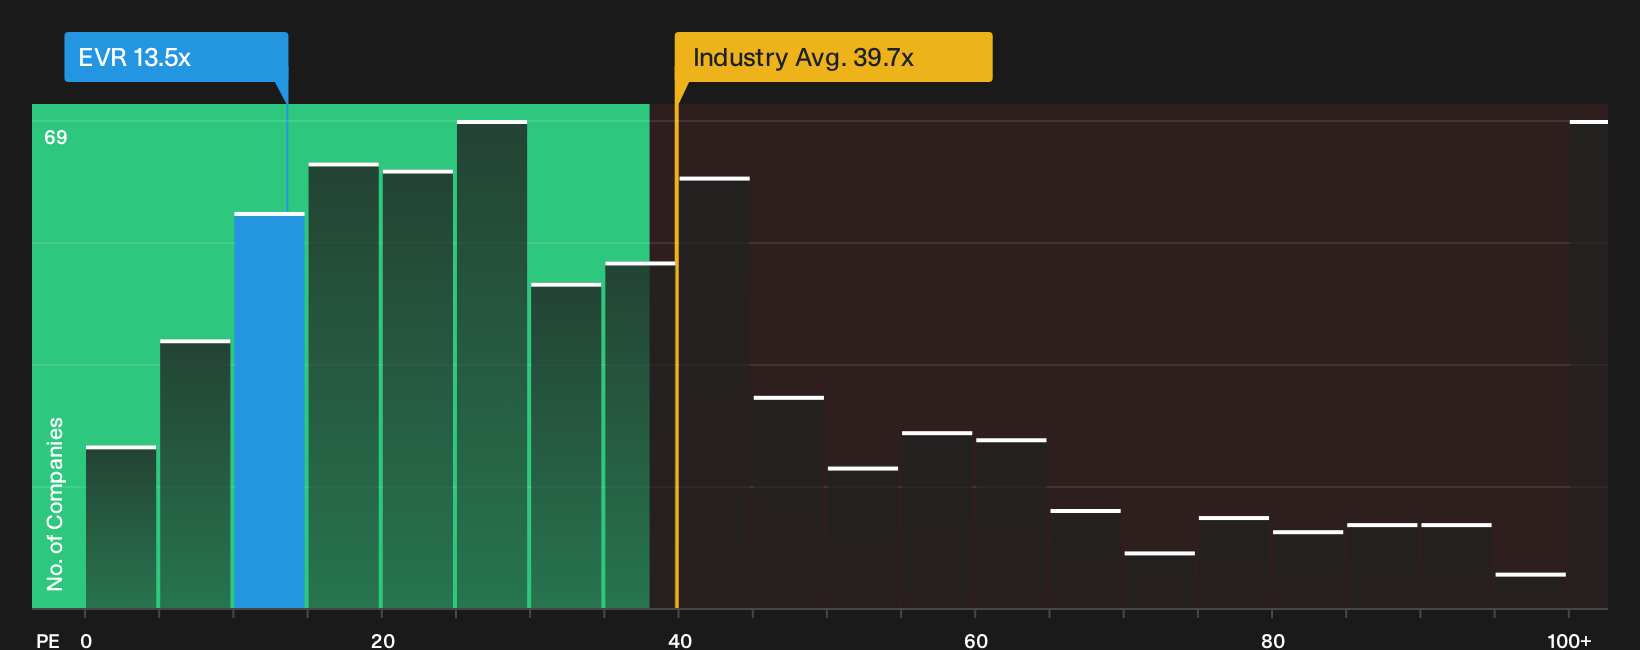
The first story paints Evercore as 28% undervalued on a fair value of $363.90. A different lens tells a cooler story. At a P/E of 13.5x, the stock trades cheaper than the US Capital Markets industry at 39.7x and peers at 27.2x, yet slightly richer than its 12x fair ratio. That gap hints at some valuation risk if earnings stumble, even with a discount to the sector.
To see how the numbers stack up in detail, including where the market could shift toward that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Evercore leave you unsure, consider acting while sentiment remains divided and review the upside drivers behind 3 key rewards
Looking For More Investment Ideas Beyond Evercore?
You do not need to stop at Evercore. Broaden your watchlist now and give yourself more ways to react when the next opportunity appears.
- Target potential upside by scanning a curated set of quality companies that trade at a discount using our 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing yield-focused opportunities screened for payout appeal through the 7 dividend fortresses.
- Protect your downside by focusing on businesses filtered for resilient financial profiles using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com