


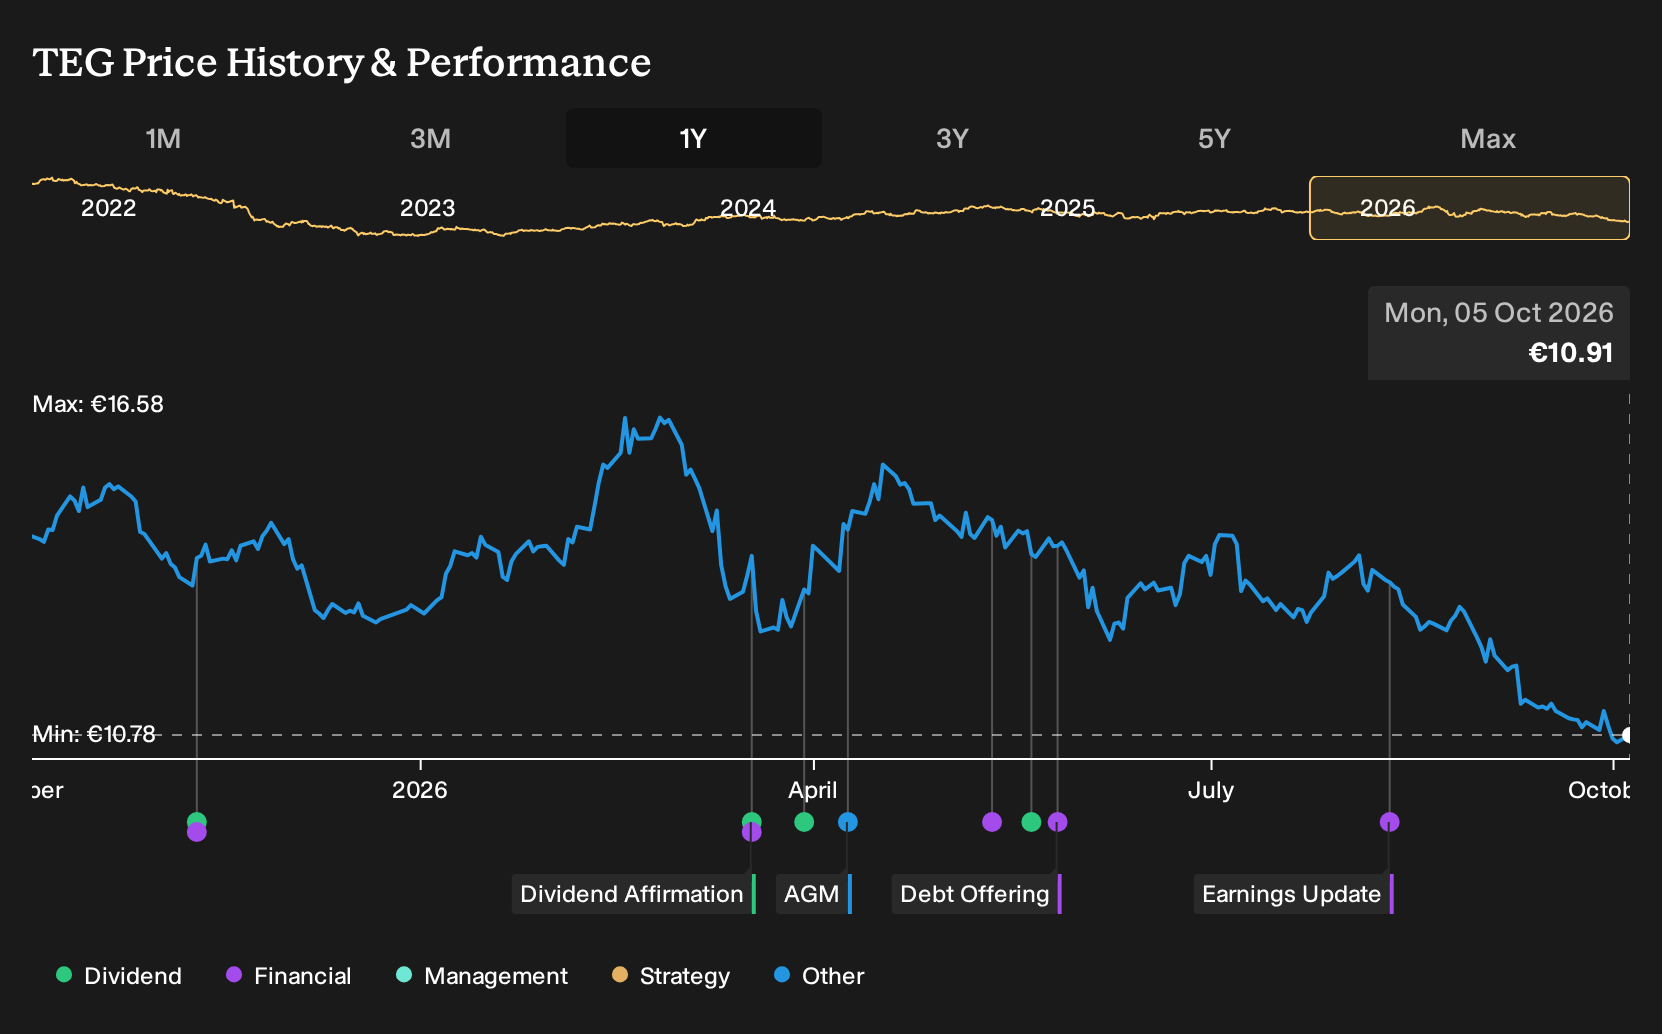
If you had decided on 2 October 2025 to hold TAG Immobilien rather than sit out the argument between bullish growth hopes and bearish demographic worries, the outcome would have been painful. Holding TAG Immobilien over the past year would have meant a 23.1% loss, including dividends. That headline number is clear. The real puzzle is which early clues, from valuation uplift assumptions to leverage and Poland timing risks, deserved closer scrutiny before committing capital.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind TAG Immobilien. Zero in on 187 high quality undervalued stocks for companies trading below our estimates.
The Two TAG Immobilien Stories Investors Had In Front Of Them
The shares cost €14.5 at the start of the period, and anyone looking at TAG Immobilien then had to pick between two very different yet plausible stories.
The bullish narrative put Fair Value at €18.15, which was 25% above the start price. This assumed TAG Immobilien could work through a revenue decline of 24.0%, with profit margins reaching 82.5% and a future P/E of 11.4x, supported by Poland expansion and portfolio modernization.
The bearish view pointed to a Fair Value of €13.7, which was 6% below the start price. This assumed revenue fell 29.5% while profit margins rose to 89.8% on a future P/E of 10.6x, with demographic and regulatory pressures weighing on German and Polish housing demand.
What The Results Changed For TAG Immobilien
The clearest new fact was TAG Immobilien’s Q2 2026 figures. Revenue moved to €213.6m while net income fell to €76.4m and net margin declined from 53.5% to 35.8%. That challenged the optimistic profitability ramp, even as Q1 2026 FFO rose 10% and rental growth in Germany and Poland supported the bull story on demand. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on future margin expansion, it is important to track net margin and FFO together against the original forecast, rather than just watching rental growth headlines.
What TAG Immobilien’s Lower Price Now Assumes
TAG Immobilien trades today at €10.78 after a 23.1% loss over the past year. The selected Narrative’s Fair Value sits above the current price, based on a mix of rental momentum, asset revaluations, and balance sheet strength offset by demographic and regulatory pressure.
For the fall to look like an opportunity rather than a warning, a buyer would need to believe robust rental growth, valuation uplifts, and Polish expansion can outweigh occupancy, regulation, and cost risks over time.
"The company is experiencing robust like-for-like rental growth both in Germany (2.9 percent in H1 2025) and Poland (3.3 percent in H1 2025), supported by consistent demand fundamentals, which is likely to drive sustainable growth in revenue and operating cash flow in the coming years. Strong valuation uplifts were recorded in both German and Polish portfolios, with German residential properties increasing in value by 1.4 percent in H1 2025 and the Polish rental portfolio seeing a step-change uplift linked to increased sales prices; these trends could support continued growth in EPRA NTA per share and overall asset values."
The price and this Narrative do not agree. → Uncover what this Narrative says TAG Immobilien is actually worth
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 44% below our estimate - builds multi-year housing and infrastructure projects that secure recurring technical service contracts.
- Company 2 - 27% below our estimate - expands a unified cybersecurity platform as customers adopt additional AI-driven protection modules.
- Company 3 - 40% below our estimate - brings higher-grade ore through its mills to increase output and reduce unit operating costs.
Three companies from the same screener. Open the full list of 207 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com