


Coeur Mining (CDE) has put exploration spending in the spotlight after outlining a record US$158 million program for 2026, centered on its New Afton and Rainy River assets in Canada.
The exploration update lands after a volatile stretch for Coeur Mining, with the 1-month share price return down 16.86% even as the 90-day share price return is up 10.10%. Over a longer horizon, total shareholder return has declined 8.58% over the past year but remains very large at roughly 7x over three years and almost 3x over five years. This suggests earlier optimism has been tempered recently as investors reassess both growth potential and risk around execution on projects like New Afton and Rainy River.
Compare Coeur Mining's exploration driven story with a curated set of other producers targeting resource growth by reviewing the 36 elite gold producer stocks in one place.
Cœur Mining now pairs a record exploration budget with a share price that has cooled in the past month. Is that combination a strong business on sale, or a story already fully reflected in today’s US$17.66 quote?
Most Popular Narrative: 26% Undervalued
Coeur Mining's most followed narrative pegs fair value at $23.95, well above the recent $17.66 close. This puts the spotlight on how mine ramps, exploration and cash flow assumptions feed into that gap.
Aggressive brownfield exploration and land package expansion at existing sites are likely to extend mine life and expand reserves, supporting sustained long-term production and reducing future earnings volatility.
See why 84 investors see Coeur Mining as 26% undervalued.
Result: Fair Value of $23.95 (UNDERVALUED)
Still, the Coeur Mining story can change quickly if the timing of mine ramp-up slips further or if higher regulatory and permitting hurdles extend project schedules.
Find out about the key risks to this Coeur Mining narrative.
Another View: Coeur Mining Through Earnings Multiples
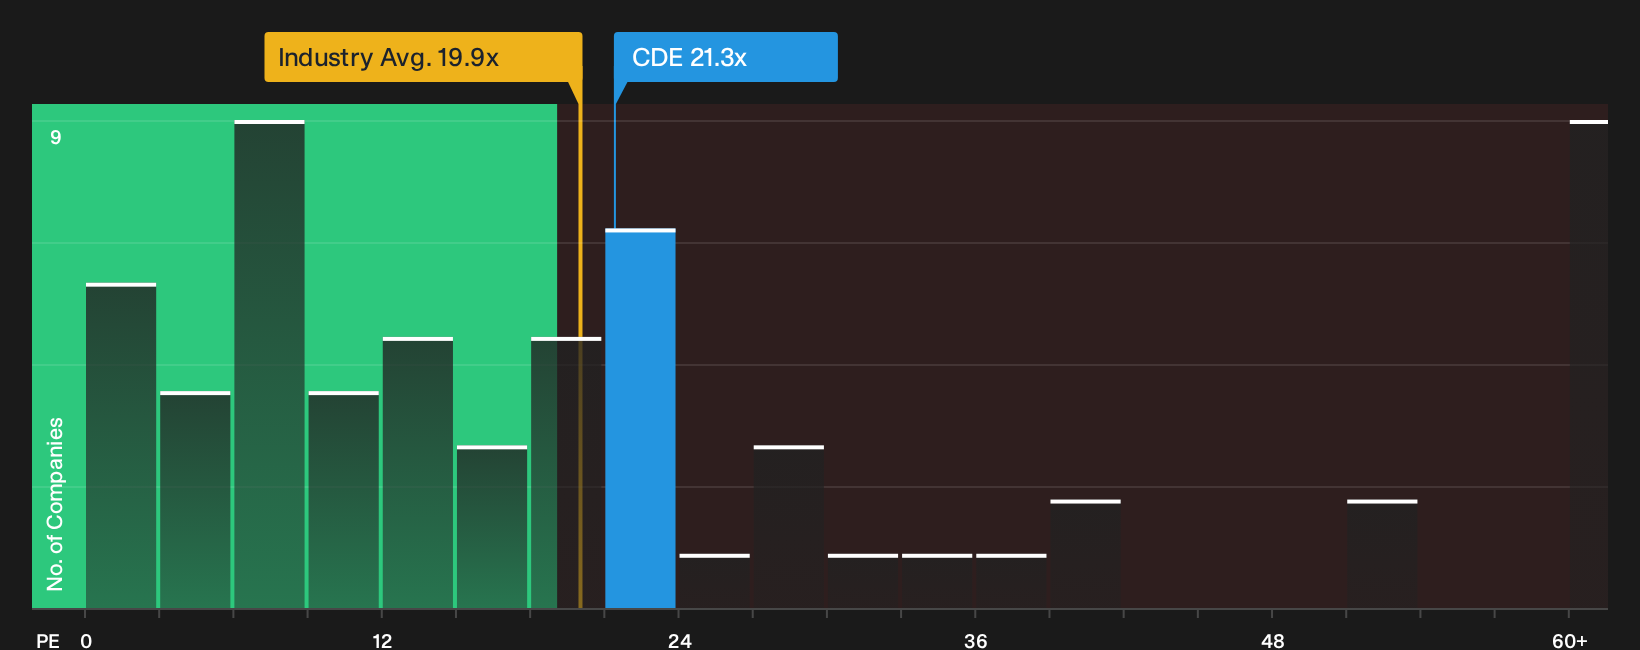
There is a different lens on Coeur Mining when shifting from fair value models to simple earnings comparisons. The stock trades at a P/E of 21.3x, which is higher than both US Metals and Mining peers at 19.9x and its own fair ratio estimate of 25.8x.
That mix is interesting. On one hand, Coeur Mining looks expensive beside sector averages. On the other hand, the gap between the current P/E and the higher fair ratio highlights a difference the market may reassess if earnings match existing expectations. For long term holders, this can be viewed either as a form of valuation cushion or as a premium that leaves less margin for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Coeur Mining so far. If you want to move quickly and base your stance on the numbers, weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Coeur Mining?
If Coeur Mining has your attention, use that momentum. Put the same discipline to work across other opportunities that share the quality and risk profile you want.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks when conditions change quickly.
- Hunt for mispriced potential and let the valuation work for you through a curated set of 31 high quality undervalued stocks.
- Lock in income-focused opportunities by filtering for companies in the 7 dividend fortresses that meet your yield and stability criteria before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com