


Government bond markets are sending loud signals about inflation and public debt, which has pushed many investors toward smaller, financially healthier UK-listed penny shares that are not as tied to big index swings. That creates an opening for you to look at low-priced businesses where the balance sheet does more of the talking than the hype. This article walks through three financially robust penny stocks screened for stronger fundamentals.
The three penny stocks highlighted next are a starting sample only, since the full screen surfaced 249 more UK listed businesses with similar financial profiles and narratives that are not covered here.
If you want to go beyond this short list, head straight into the Financially Fit Penny Stocks screener to filter, analyze and identify the financially fitter penny shares that best match your own risk profile.
Luceco (LSE:LUCE)
Overview: Luceco designs and supplies wiring accessories, LED lighting and portable power products, with its energy efficient LED lighting directly linking it to the Financially Fit Penny Stocks electrification theme.
Operations: Luceco generates £135.3 million from Wiring Accessories, £80.6 million from LED Lighting and £72.4 million from Portable Power, mainly across the UK and international markets.
Market Cap: £310.2 million
Luceco gives you direct exposure to energy saving lighting and electrification products, while still sitting firmly in UK penny stock territory prized for stronger balance sheet characteristics.
"Luceco's new product launches, particularly in the EV charger segment, including commercial AC chargers and the forthcoming Home Energy Management System, are expected to drive revenue growth by tapping into expanding markets for residential and commercial EV solutions, as well as integrated energy management."
What happens to Luceco’s earnings profile if a single pressure point quietly reshapes how much profit each extra unit of sales delivers?
If that pressure point matters to your thesis, read the full narrative for Luceco to see how Luceco’s margin potential, cash profile and risks all connect beneath the headline story.

Stelrad Group (LSE:SRAD)
Overview: Stelrad Group manufactures and sells low cost steel panel and electric or hybrid radiators, plus related heating radiators and towel warmers.
Operations: Stelrad Group generates about £267 million from manufacturing and distributing radiators, with reported regional data spanning Europe, Turkey and international markets.
Market Cap: £185 million
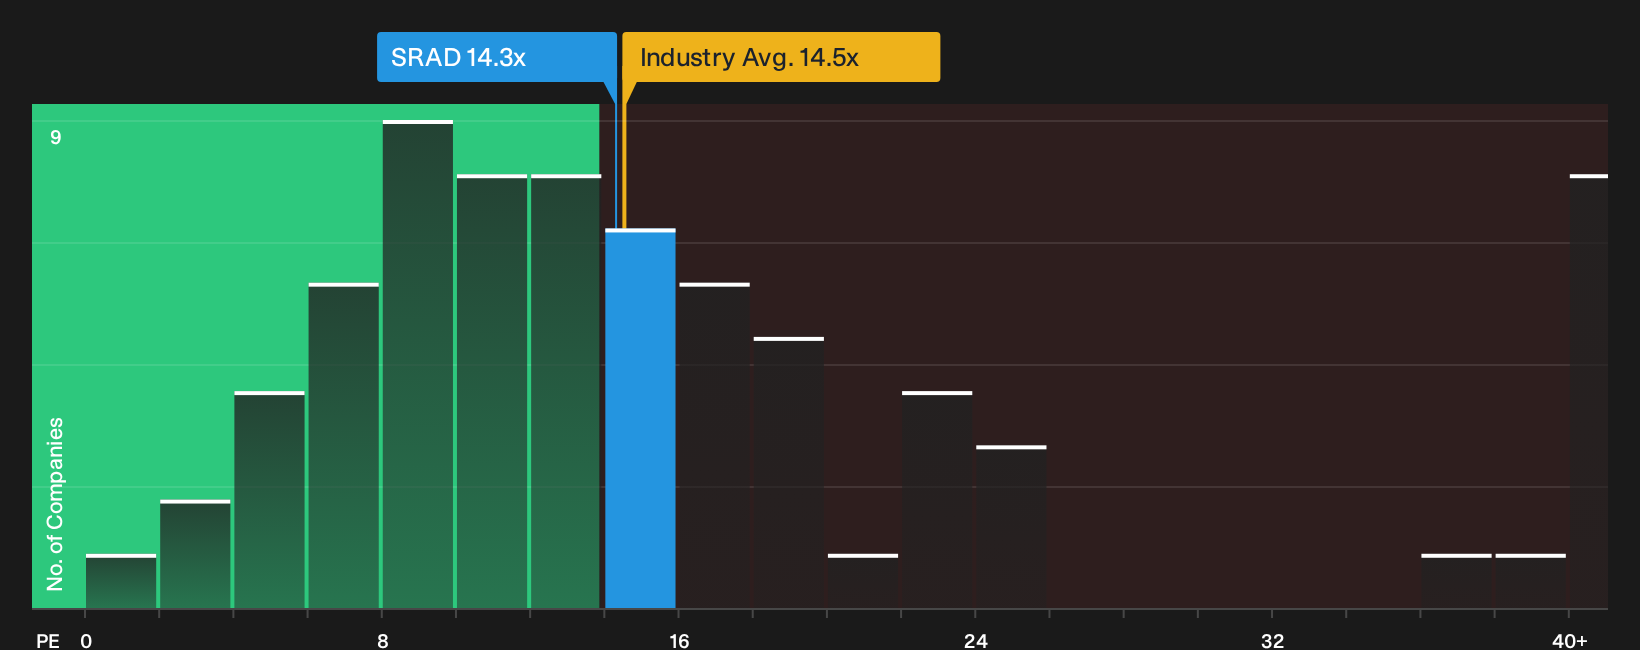
Stelrad Group fits the Financially Fit Penny Stocks theme because it focuses on affordable radiators, reports improving earnings and trades on a modest P/E. It still carries higher debt and insider selling, which could matter if one key funding pressure shifts against it.
If that funding risk is on your mind, go straight to the 5 key rewards and 3 important warning signs to see how Stelrad Group’s debt load and earnings power compare.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages infrastructure and private equity funds that channel equity and credit into smaller, early-stage businesses worldwide.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, primarily across the UK and Australia.
Market Cap: £490.5 million
Foresight Group Holdings matters for the Financially Fit Penny Stocks theme because it is effectively the capital partner behind many smaller, early-stage companies that investors in this screener want exposure to, but with the added layer of diversified assets and professional oversight around them.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is described as a factor that could deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens if a single shift in fundraising momentum or fee mix quietly changes how much of that compounding actually reaches each share?
When that fundraising gearshift matters, read the full narrative for Foresight Group Holdings to see how fee mix, capital recycling and buybacks could be quietly reshaping Foresight Group Holdings.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, not last. Spot potential breakout stories while momentum is still building and information is under the radar for now. Act now.
- Ride early momentum in resilient operators by scanning the 4 resilient stocks with low risk scores before valuations fly and quieter quality stories get fully caught by the crowd.
- Chase accelerating themes in real-economy infrastructure by tapping into the 39 power grid technology and infrastructure stocks while capital is still dropping into under-followed grid and electrification plays.
- Target metal producers with fresh operational momentum using the curated 36 elite gold producer stocks before more investors rotate toward cash generative hard-asset exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com